Real Estate & Community News

March 29, 2026

The #1 Reason Buyers Walk Away (And How To Get Ahead of It)

The #1 Reason Buyers Walk Away (And How To Get Ahead of It)

You may have seen headlines on social saying the number of buyers backing out of their contracts is on the rise – and has recently reached a high not seen since 2017. That can sound intimidating. But it varies a lot by market.

And here’s the key thing to understand if you want to sell. A lot of the time, there’s one common cause. And it’s something you can actually control.

Here’s what you can do to get ahead of the biggest dealbreaker before it ever becomes a problem.

The Top Dealbreaker: Issues That Pop Up During the Inspection

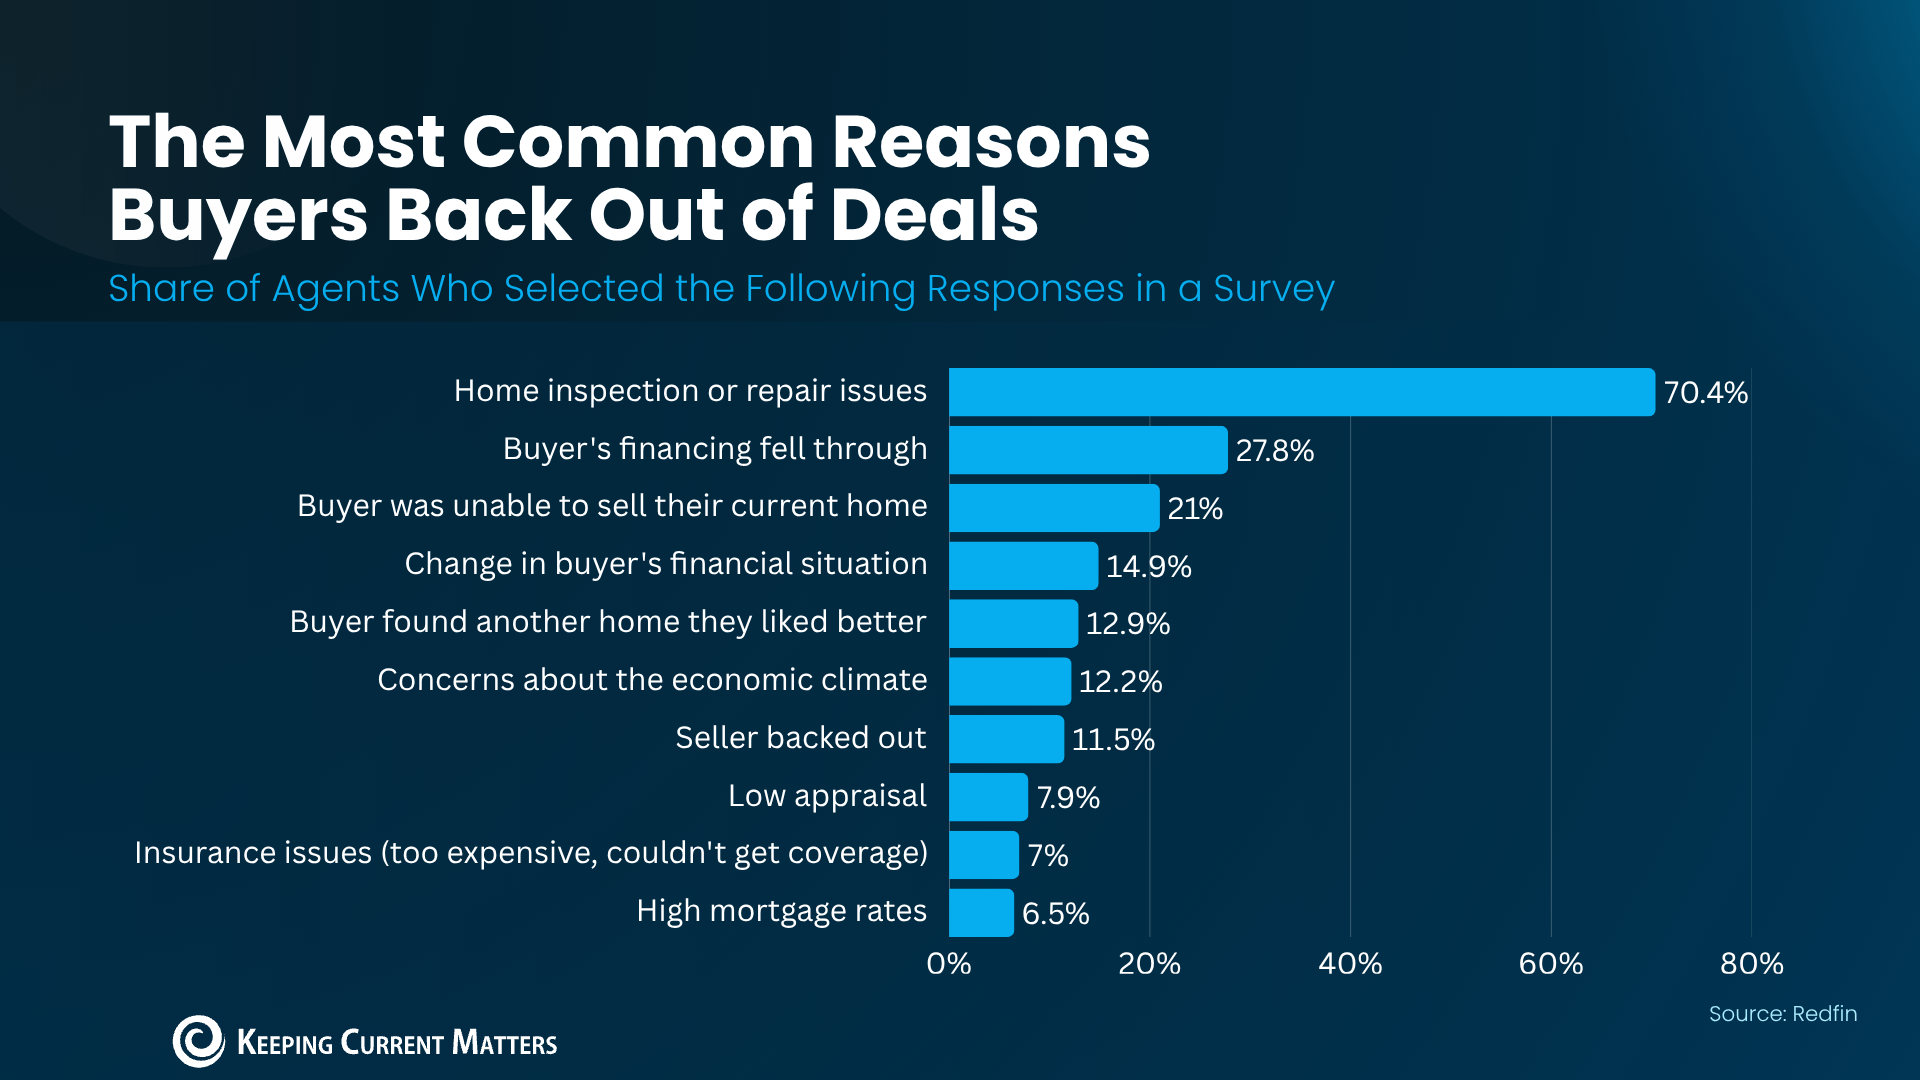
A Redfin survey shows over 70% of recently cancelled contracts happened because of issues during the home inspection (see graph below): 
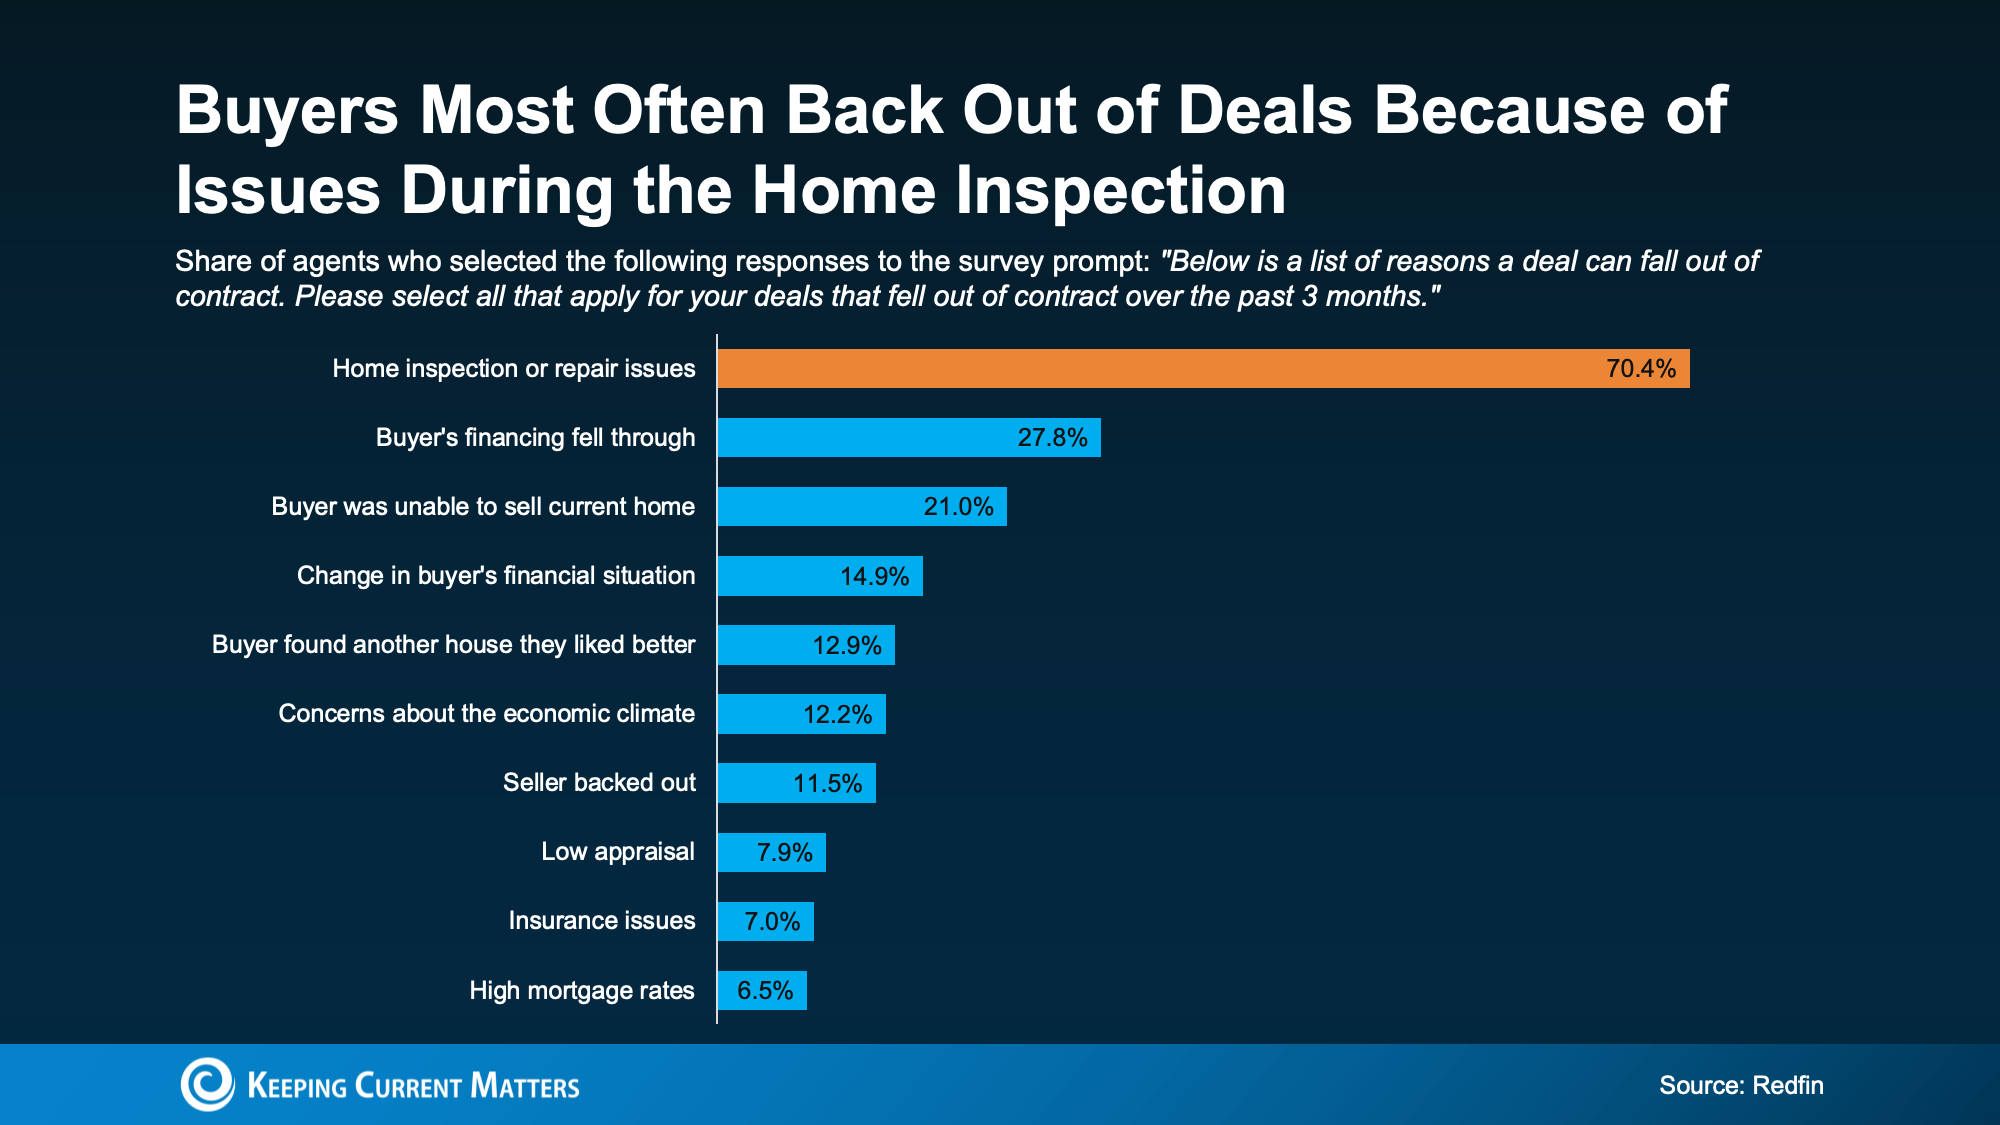
a screenshot of a survey

Why Fixing Things Before You List Matters More Today

A few years back, when buyers felt rushed or boxed in due to the limited number of homes for sale, they were more willing to overlook issues.

But in today’s market, skipping essential repairs is one of the fastest ways to lose a deal.

Now that there are more homes to choose from, buyers can be more selective. If a house feels risky, outdated, or like it’s hiding expensive surprises, they’re a lot more likely to walk away. So, what do you have to fix? Just ask an agent.

How Your Agent Can Help Give You the Edge

A local agent will be able to walk through your house and offer advice on what to tackle based on your specific home, your market, and what buyers are prioritizing in your area. They’ll also have first-hand knowledge about some of the biggest turnoffs for buyers today. And you can use that expertise to prevent future headaches.

For example, according to Zillow, these are some of the issues buyers will care the most about:

  • Roof leaks or damage: sagging, leaking, etc.
  • Plumbing problems: standing water, leaks, water damage, etc.
  • Electrical concerns: outdated or exposed wiring, missing GFCI outlets, etc.
  • HVAC issues: non-functioning units
  • Pest or insect damage: termite colonies, etc.
  • Hazardous materials: lead, mold, asbestos, etc.
  • Safety/code violations: missing smoke detectors, windows stuck closed, etc.
  • Structural problems: cracks in the foundation, sagging floors, etc.


Odds are not all of this even applies to your house. Maybe only 1-2 things do. Or maybe none of them do. It just depends. But an agent will have the tools and resources to help you figure it out and stay one step ahead.

The Benefits of a Pre-Listing Inspection

To buyers, these aren’t cosmetic issues. They’re trust issues. And that’s what you need to watch out for today. Once buyers start wondering “what else might be wrong,” it’s hard to recover momentum.

That’s why some agents are even recommending a pre-listing inspection as a sneak peek into what buyers will see on their own inspection. With that insight, you can:

  • Fix concerns before you list, or disclose issues upfront
  • Avoid having to respond or negotiate under pressure
  • Stop scrambling to find contractors with availability before your closing date

But remember, you don’t have to fix everything. You just have to be strategic about what you do tackle, so you and your buyer aren’t caught off guard.

And that’s why you need an agent who can:

  • Decide if a pre-listing inspection is worth it where you live
  • Recommend a trusted inspector (if you decide to get one)
  • Look at the results with you to identify true dealbreakers in your market
  • Help you decide what to fix or what to credit
  • Make sure you avoid over-spending or under-preparing

Bottom Line

One of the biggest dealbreakers for buyers today is inspection issues – and that’s something you can control. You just need to be proactive about high-impact repairs before you list.

If you want help figuring out where to focus, connect with an agent.
Posted in For Sellers
March 28, 2026

Renting vs. Buying: The Numbers Might Surprise You

Renting vs. Buying: The Numbers Might Surprise You

But then your rent goes up again. And again. And suddenly the thing that seemed flexible starts looking… expensive, especially considering you’re not building any equity. And once that happens, it’s easy to feel a little trapped in the cycle.

That’s because there’s so much chatter today about how buying a home isn’t affordable. But the truth is, the math may work out better than you’d expect based on what’s changed recently.

Buying Is More Affordable Than Renting in Many Areas 

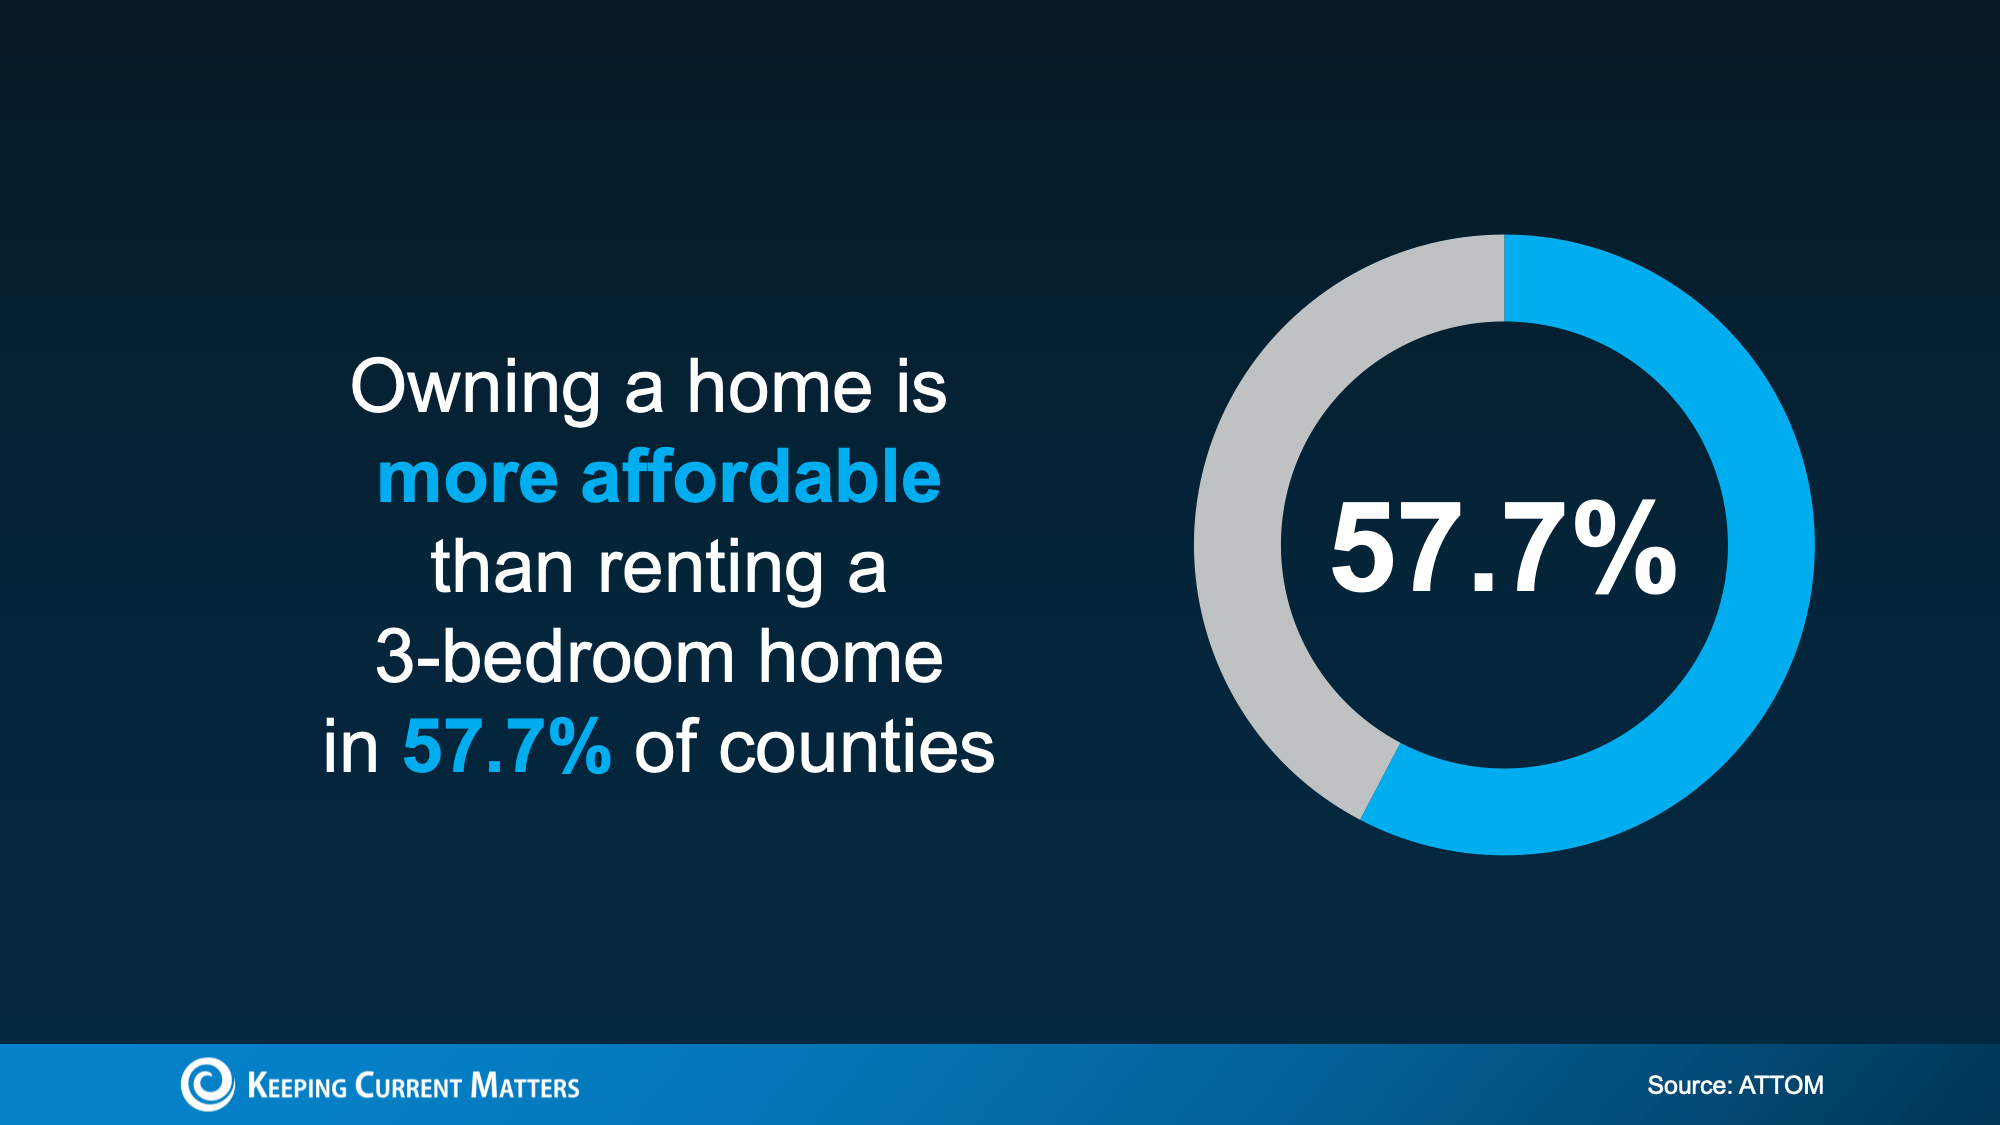
In a lot of places today, owning a home actually costs less each month than renting a 3-bedroom home. And recent data from ATTOM shows that’s true in nearly 58% of counties across the U.S. (see chart below).

And that’s after you factor in things like insurance and typical maintenance costs. 

a blue and grey circle with white textIn other words, even though it may feel like a bit of a shock, the numbers show rent often stretches monthly budgets more than owning does. That’s thanks to slower home price growth, more homes for sale, and monthly mortgage payments starting to ease as rates come down.

Affordability Still Varies by Region

Now, even though nationally the balance has shifted, that doesn’t mean buying is more affordable in every market or for every renter.

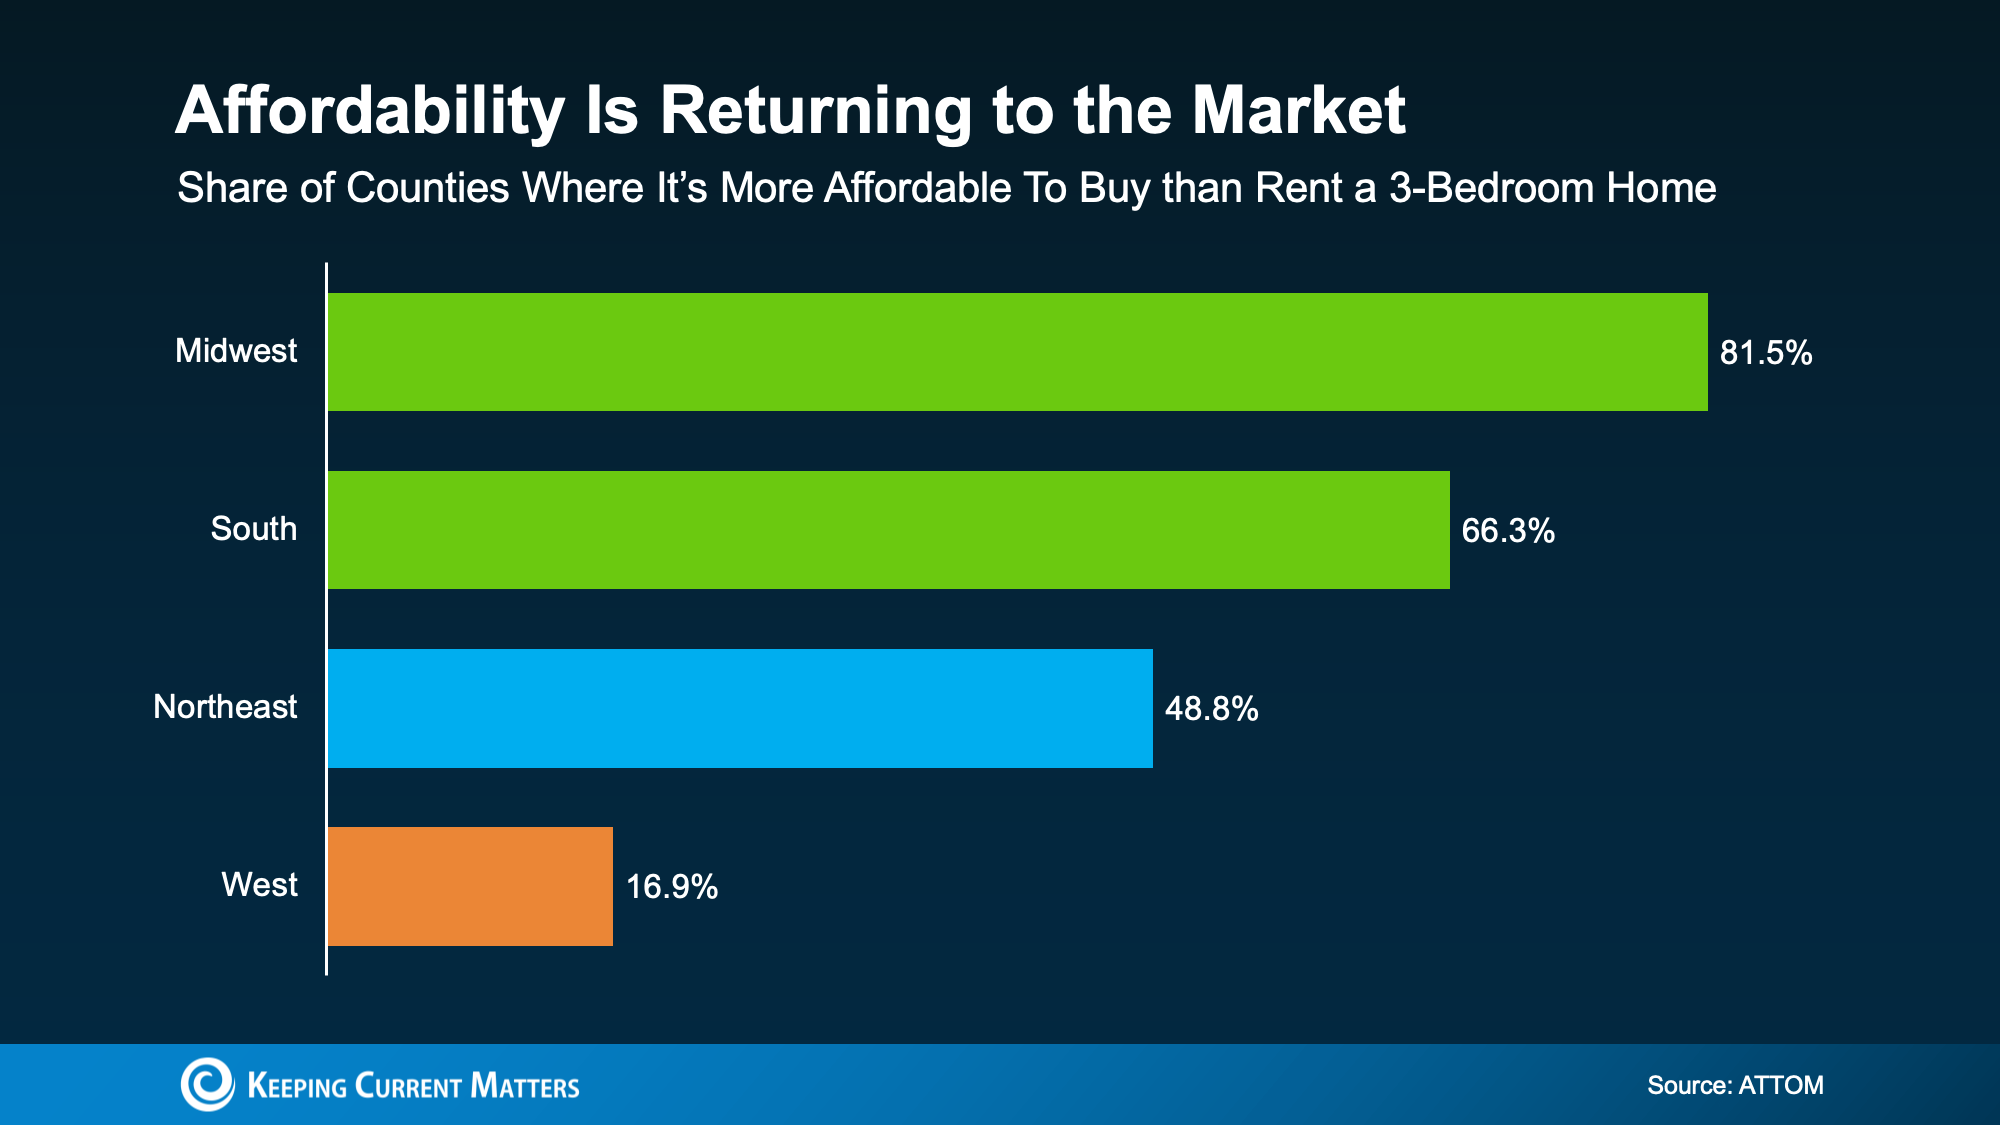
While buying is more affordable than renting in nearly 58% of counties nationwide, that share looks different depending on your region (see graph below):

a graph of a market

The biggest improvement is happening in the Midwest and South. But if you’re living in the West, things could still feel tight.

The takeaway? How affordable buying is really depends on where you live. And the only way to know how this plays out where you live is to look at the numbers locally.

So, What’s Still Holding Buyers Back? 

Maybe you’re nodding along so far but thinking, “Okay, but I still can’t afford the upfront costs.” If that’s your reaction, you’re not the only one.

For many renters, the biggest hurdle isn’t the monthly payment alone. It’s the down payment, too.

But you’re not out of options. Here’s the part most people don’t hear enough about: there are thousands of down payment assistance programs available across the country, and many buyers qualify without realizing it.

And the average benefit? Roughly $18,000.

That kind of support can help cover part of your down payment or closing costs, which means you may not need to save nearly as much as you think to get started.

When you combine that with monthly payments that may work better than expected, especially as rates continue to ease and prices cool, buying may feel far more realistic than it looks at first glance.

Bottom Line

The point isn’t that everyone should rush out and buy a home tomorrow.

It’s that renting isn’t always the more affordable option people assume it is – and buying may be more realistic than it feels once you look at the full picture.

If you’re renting and feeling stuck in the “someday” loop, it might be worth a simple conversation with a local real estate agent or lender. Just a chance to see what’s possible and whether it makes sense for you.

March 27, 2026

If Your House Isn’t Getting Offers, Read This.?

If Your House Isn’t Getting Offers, Read This.

If Your House Isn’t Getting Offers, Read This.

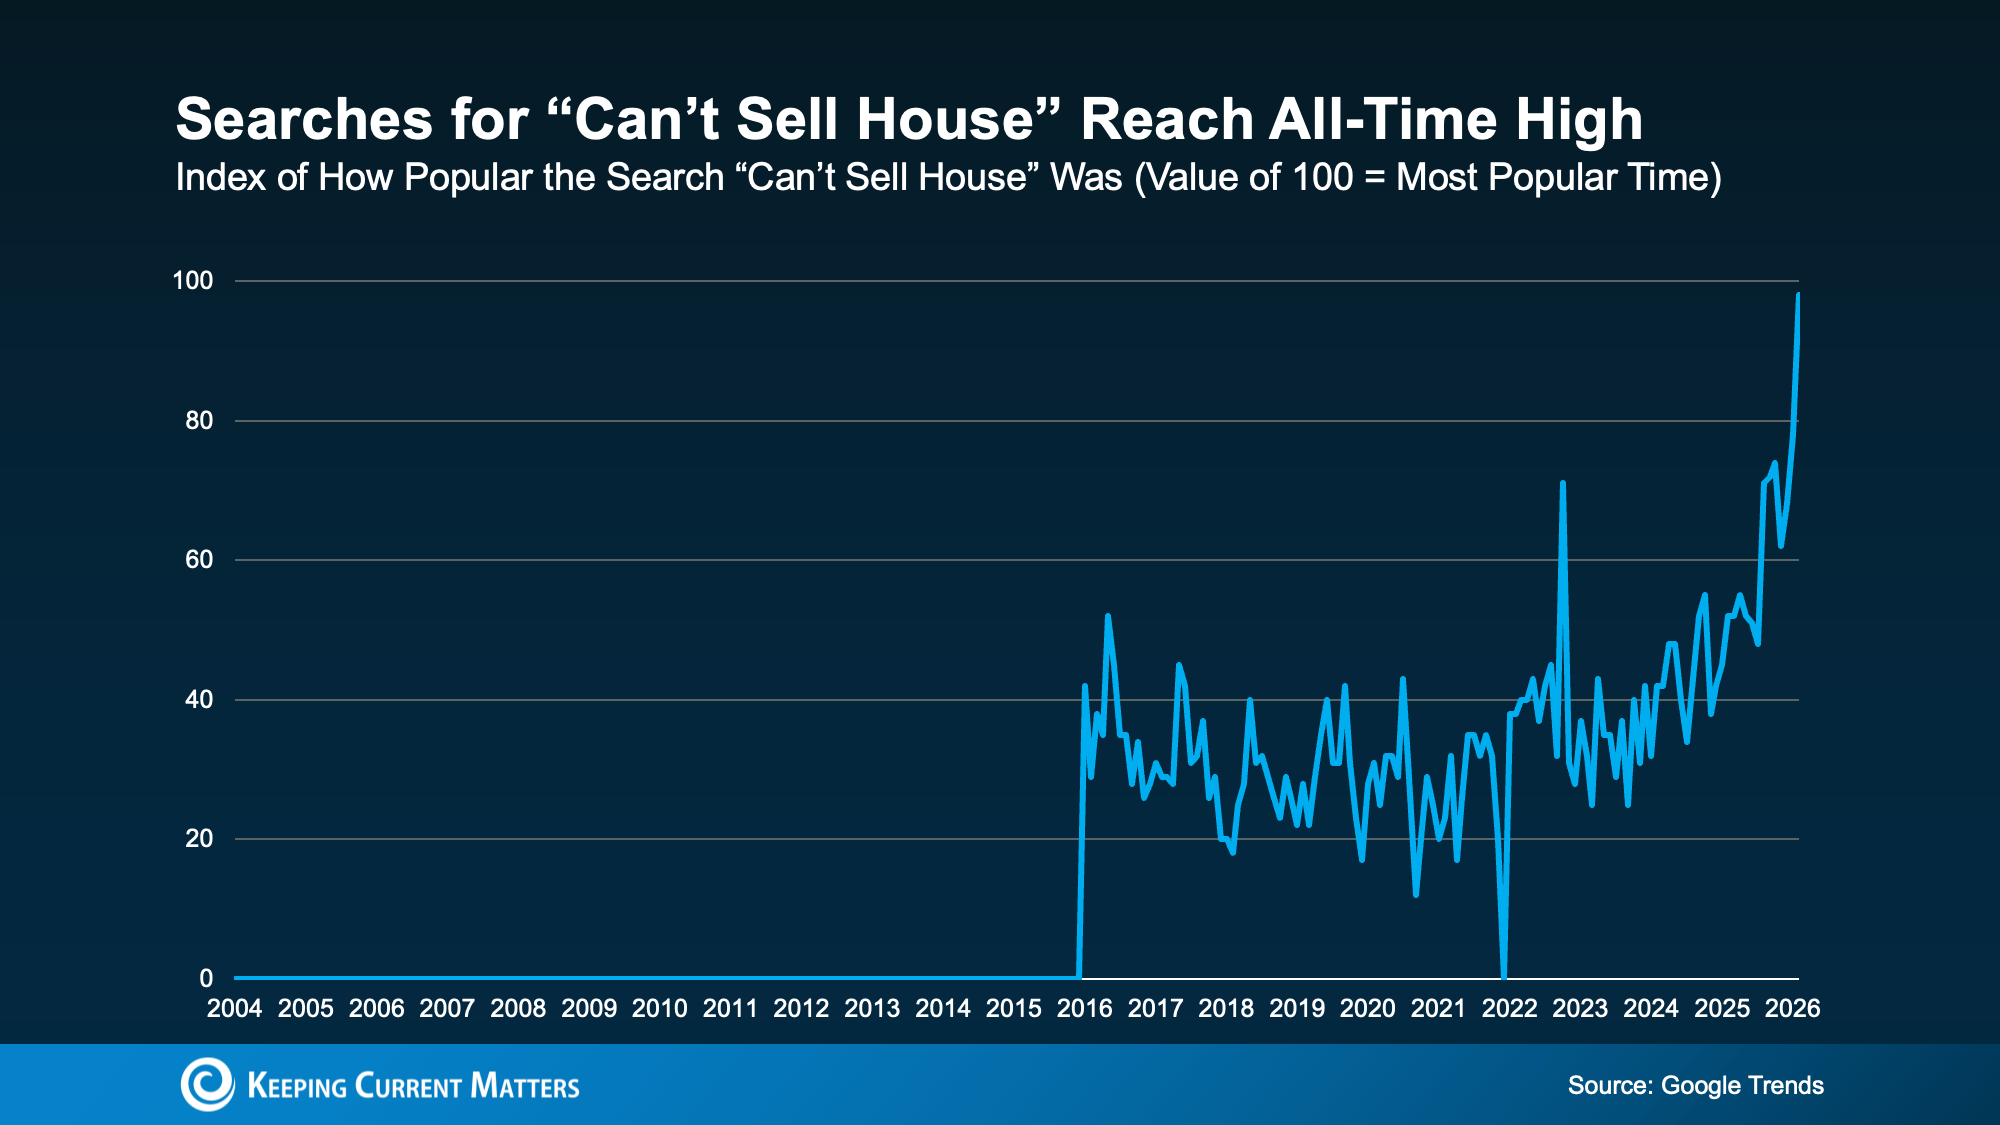
Online searches for “can’t sell house” just hit an all-time high according to Google Trends. So, if your house has been sitting on the market without any bites, you’re not the only one. But it’s also not the end of the road. 

Homes are selling every day, so you can turn this around. You just need to take another look at your approach.

a graph of a house priceIf you’re feeling this pain, know this: an online search engine isn’t where you should go for your answers. It’s much better to talk to your agent. Because a search engine doesn’t know your market or your house. But your agent does.

While a quick search or an AI platform may give you some tips on what to try, only an expert agent can actually diagnosis what’s going on – and how to fix it.

For example, your agent knows most homes that struggle to sell today are usually being held back by one (or more) of these three things.

1. Presentation: Buyers Will Compare Everything

When inventory was tight a few years ago, buyers overlooked imperfections because they had to, or they’d lose out to another bidder. Now? That’s no longer the case.

Today’s buyers scroll through dozens of listings in just minutes. They compare condition, updates, lighting, finishes, layout, and more – all side by side. If your home feels dated, cluttered, or in need of repairs, buyers will notice and it’ll knock your house right off their list of contenders.

This doesn’t mean you need a full renovation. But it does mean first impressions matter again. To compete today, you need curb appeal. Clean spaces. Neutral colors. Professional photos. If there are scuffs on the walls, obvious repairs, or too many outdated features, it could be what’s holding you back.

2. Pricing: If the Price Isn’t Compelling, It’s Not Selling

This is maybe the hardest one to hear, but what your neighbor sold their house for a few years ago isn’t necessarily the same price you’ll get today. As Selma Hepp, Chief Economist at Cotality, says:

“For sellers, the days of pricing aggressively and expecting instant offers are largely over. Homes that are well-priced and well-presented will still sell, but pricing discipline matters more than it did during boom years.”

Buyers are budget-conscious right now. If your home is priced based on outdated expectations instead of current demand, buyers may still look at your house online… but they likely won’t write an offer. Or, they’ll make an offer that you think is too low.

Pricing too high for this market is one of the top things sellers miss the mark on today. And those who aren’t willing to meet the market where it is or entertain offers may feel stuck.

3. Access: If Buyers Can’t See It, They Can’t Buy It

It sounds obvious but limited showing availability can kill your momentum. If your house isn’t easy to see because you’re restricting showings to evenings only, no weekends, or requiring a 24-hour notice, you’re cutting your buyer pool down by more than you may realize. 

And the more friction you create, the fewer buyers walk through the door.

In a market where buyers have more options, the last thing you want to do is give them a reason to skip your house. Availability matters because if no one sees it, no one buys it.

Don’t Let Search Results Decide Your Next Step

When your house isn’t selling, it’s tempting to spiral and wonder if it’s the market or if something’s wrong with your house. But instead of searching for answers online, here’s what to do.

Sit down with your agent and ask three honest questions:

  • What are buyers looking for in today’s market?
  • What feedback are we getting from showings?
  • Why do you think my house hasn’t sold yet?

That conversation will bring a lot more clarity than any search engine results.

Bottom Line

If your listing feels stuck, it’s not a sign you shouldn’t sell. It’s the market giving you feedback. And feedback is powerful when you use it.

Start with a real conversation with a real agent about what’s working and what’s not. Your agent will be able to tell you which small adjustments could totally change the momentum. Because in this market, the sellers who adapt are the ones who move.

March 27, 2026

You Can’t Control What’s Happening with Mortgage Rates. But You Can Control This.

You Can’t Control What’s Happening with Mortgage Rates. But You Can Control This.

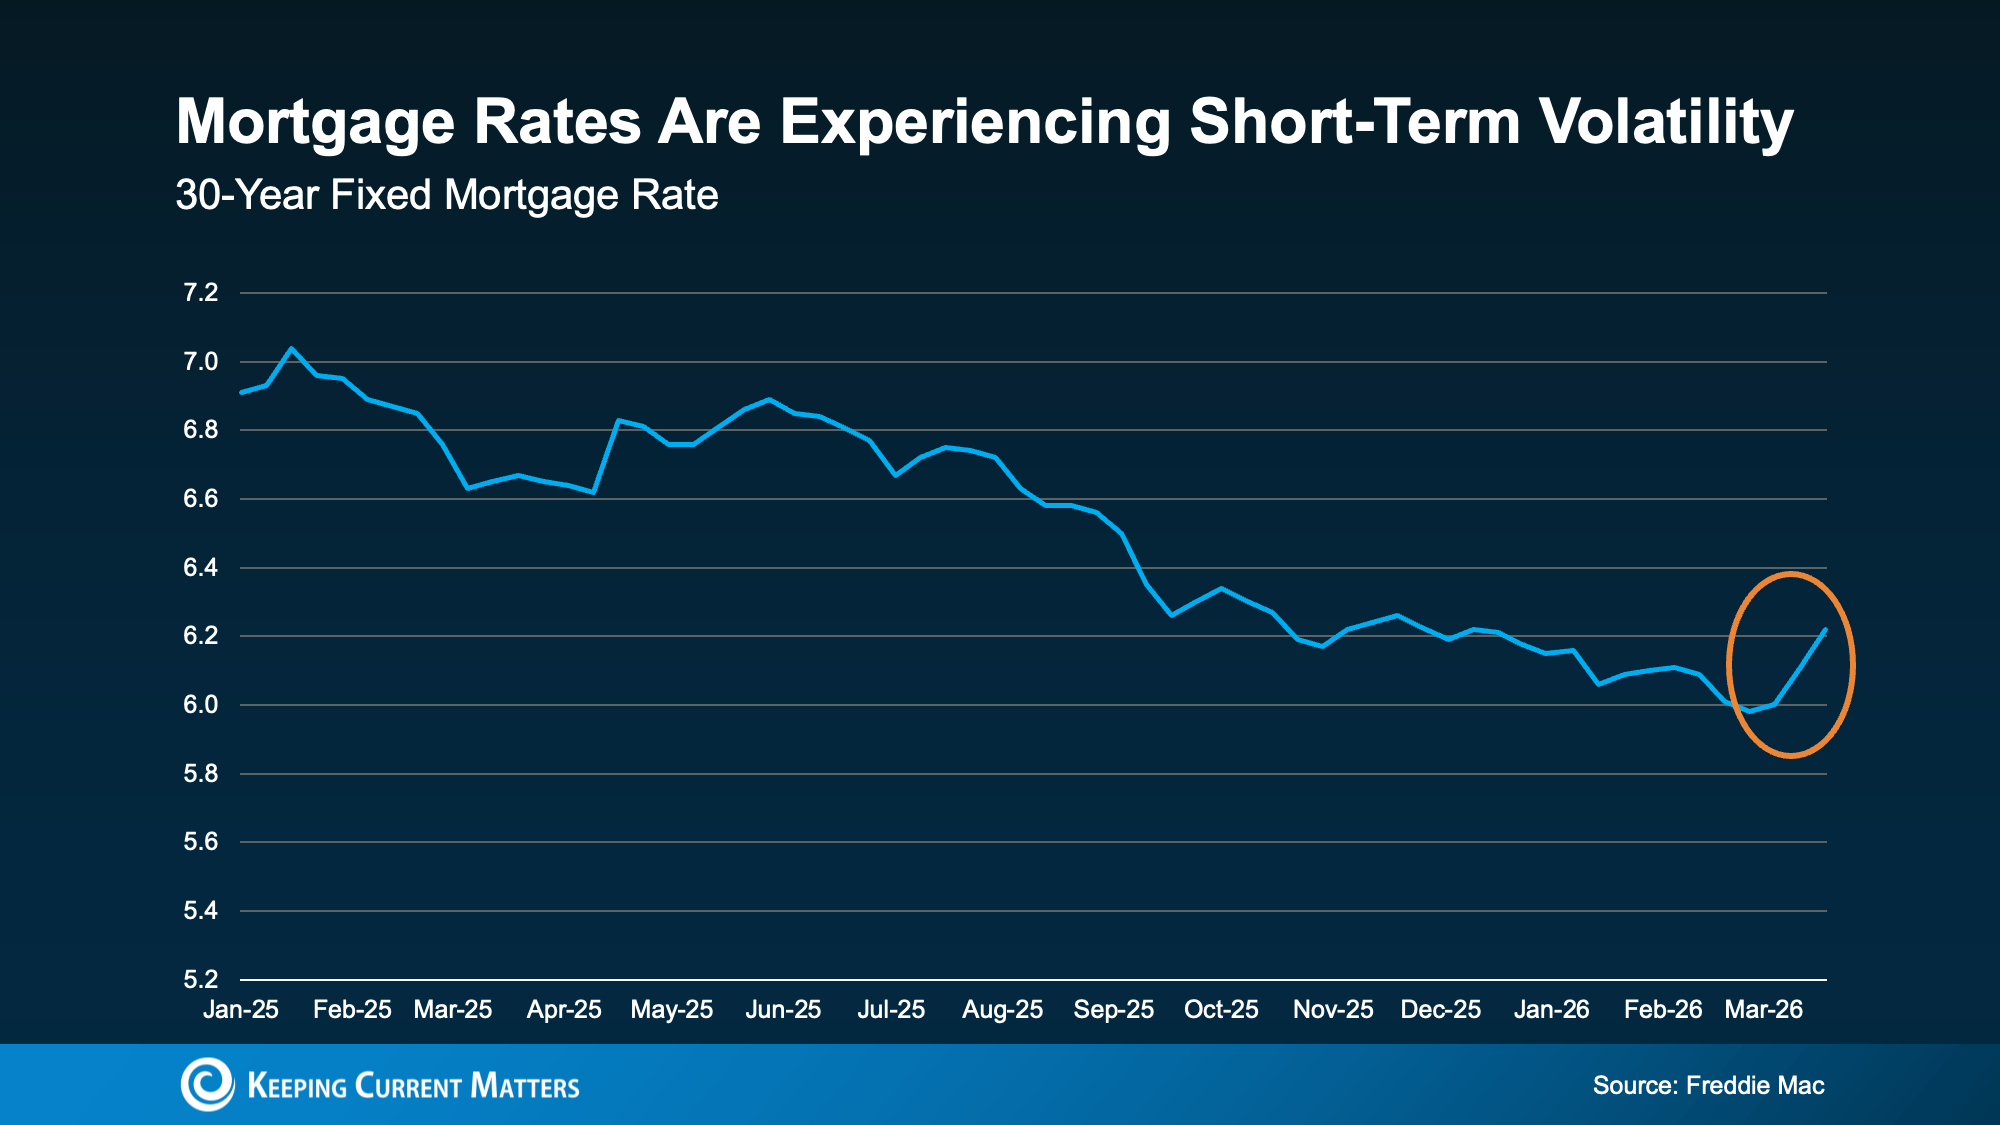
Mortgage rates have been volatile lately. And if you’re thinking about buying a home, that can make it harder to plan. But there are still things you can do to get the best rate possible in today’s market. It starts with having the right information.

So, what’s causing the bumps in rates? And what can you do about it? Let’s break it down.

Mortgage Rate Volatility Is Normal

Data from Freddie Mac shows the recent volatility. After trending down for well over a year, there was a rise this month (see graph below):

a graph showing a line of a moving rate


While it’s easy to be distracted by the changes, here’s what you need to remember.

It’s normal for rates to bounce around a bit here and there. For example, if you look back at the graph, you’ll see that even within the past year there have been times like this when rates inched up. We’re in one of those moments right now and you need to be aware of that.

Especially when there’s economic uncertainty or big global events happening, volatility like this is expected. As Investopedia explains:

“Mortgage rates don’t move in isolation. When global events inject uncertainty into financial markets . . . that can ripple through to borrowing . . . mortgage costs can respond quickly to geopolitical developments. As long as uncertainty remains elevated, rate swings may continue.”

And that’s one of the reasons why trying to time the market isn’t a wise move.

You can’t control what happens with mortgage rates. But there are still things you can do to help you get the best rate possible in today’s market. And here’s where to focus your effort.

Your Credit Score

Your credit score plays a big role in the rate you qualify for. Even a small improvement can make a noticeable difference in your monthly payment. As Bankrate puts it:

“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”

So, make sure you do what you can to keep your credit score up. If you’re not sure what your score is or how you can improve it, talk to a trusted loan officer.

Your Loan Type

There are also different types of home loans – and each one can have unique requirements, benefits, and rates for qualified buyers. The Consumer Financial Protection Bureau (CFPB) explains:

“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose.”

That’s why it’s so important to explore your options with a lender. You may even want to talk to multiple lenders to see how the options vary.

Your Loan Term

The length of your loan matters too. Most lenders typically offer 15, 20, or 30-year loans. Freddie Mac offers this advice:

“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”

Again, to figure out what makes the most sense for your budget and long-term goals, have a lender walk you through all your options.

Bottom Line

Thinking about buying right now? The best advice is to accept that you can’t control where rates are going to go from here.

What you can do is work with a trusted lender and take steps that’ll help you get the best rate possible.

So, if you want to move today, talk to an agent and a lender to make it happen. You just need to control the controllables and focus where it counts.

Posted in For Buyers
Jan. 11, 2026

Don't Let the Fear of a Buyer Backing Out Scare You Away from Selling

Don

There’s nothing quite like the excitement of getting an offer on your house. You’re one step closer to moving on to what’s next. But what happens if that buyer backs out or ghosts you before closing?

If you’ve been seeing headlines about more home sales falling through lately, that possibility may be keeping you up at night. And it’s true. According to Redfin and Cotality, canceled contracts have been on the rise.

But here’s what those headlines don’t always tell you…

Most sales still go through. Only 10-15% hit this snag. And even so, there are things you can do to help keep your sale from becoming one of them.

The key is knowing what tends to scare buyers away and getting ahead of those issues before they have a chance to derail your move.

What’s Behind the Rise in Canceled Contracts?

Today’s buyers are being more cautious. Mortgage rates are stretching budgets, and with more homes to choose from, buyers have more freedom to walk away if something doesn’t feel right. As Redfin explains:

“That gives house hunters more options and makes them more likely to walk away if an inspection uncovers problems, an appraisal comes in low or the seller doesn’t agree to concessions.”

That’s why an accepted offer isn’t always a guaranteed sale. But it doesn’t mean you should be afraid to put your house on the market, either.

It just means getting ahead of potential problems matters more than ever.

3 Things That Can Scare Off a Buyer (and How To Get Ahead of Them)

A Redfin survey asked real estate agents why some buyers are backing out. And their answers give you a short of cheatsheet into what could go sideways and how you can get ahead of those headaches (see graph below):

a graph of a survey

1. Inspection or repair issues (70.4%)

This is the big one. And the good news? It’s also one of the areas where you can be the most proactive.

One simple way to head this off is by getting a pre-listing inspection before your house goes on the market. That way, if something needs attention, you can decide whether to fix it upfront (before you sell), adjust your price, or disclose it and come in already prepared for what’s likely to pop up in negotiations. It’s a lot better to find the skeletons in the closet before a buyer does.

2. Buyer financing falls through (27.8%)

Even buyers who are pre-approved can run into financing issues before closing. And with mortgage rates putting extra pressure on affordability, some buyers are finding it harder to make the numbers work.

While you can’t control whether a buyer’s loan goes through, you can work with your agent to look closely at their financing before accepting an offer. And if affordability is the concern, your agent can help you explore whether incentives like closing cost credits or a mortgage-rate buydown could make a difference.

3. The buyer can’t sell their current home (21%)

Sometimes, your buyer needs to sell their house before they can buy yours. And if their sale falls through, yours could be affected too.

That’s why it’s important to understand any home-sale contingencies before accepting an offer. Your agent can help you look at where the buyer is in their own selling process and what protections you may want in place.

The goal isn’t to eliminate every possible risk. It’s to avoid being caught off guard by the ones you can plan for.

Don’t Let the What-Ifs Keep You Up at Night 

Just remember when you read headlines about canceled deals, they don’t give you the full picture. Most home sales still make it to closing.

And if a sale does fall through, that doesn’t automatically mean your house won’t sell. Sometimes a buyer’s circumstances change. Sometimes an issue comes up that can be addressed before the next offer.

What matters is having an agent who knows how to spot potential problems early, help you navigate negotiations, and keep your sale moving forward.

Because while you can’t control every twist and turn, you can control how prepared you are.

Bottom Line

There's no need to let the fear of a buyer backing out hold you back. While no sale comes with guarantees, a little preparation upfront can go a long way toward making the whole process smoother.

If you're ready to make a move, talk to a local agent about whether a pre-listing inspection makes sense for you.

Posted in For Sellers
Jan. 30, 2024

2 Reasons Why Today’s Mortgage Rate Trend Is Good for Sellers

2 Reasons Why Today’s Mortgage Rate Trend Is Good for Sellers

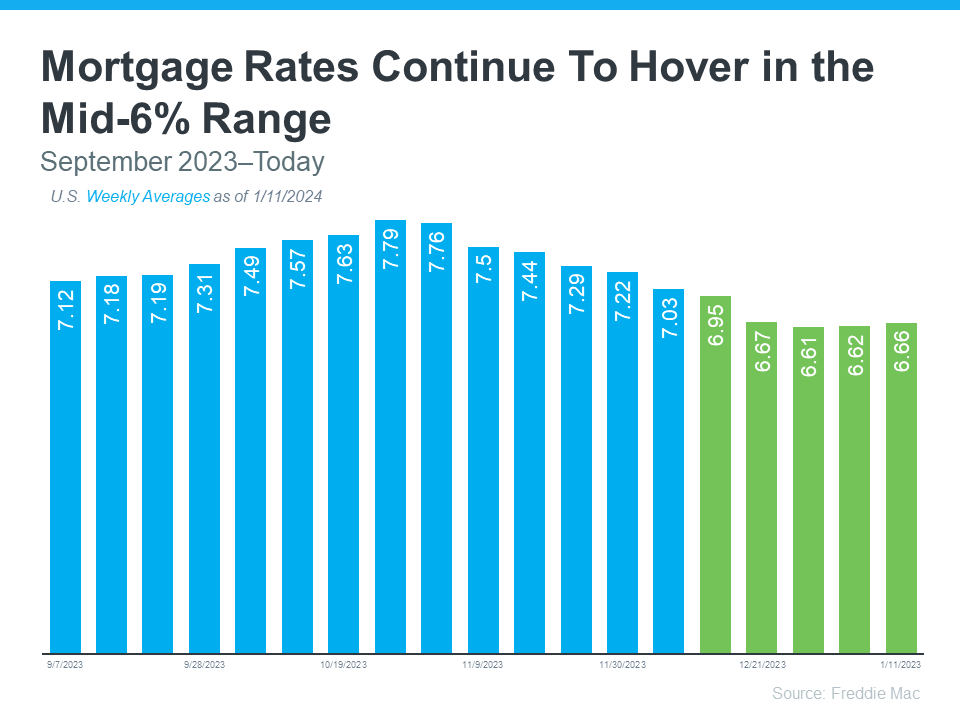
If you’ve been holding off on selling your house to make a move because you felt mortgage rates were too high, their recent downward trend is exciting news for you. Mortgage rates have descended since last October when they hit 7.79%. In fact, they’ve been below 7% for over a month now (see graph below):

And while they’re not going back to the 3% we saw during the ‘unicorn’ years, they are expected to continue to go down from where they are now in the near future. As Dean Baker, Senior Economist at the Center for Economic Research, explains:

“It also appears that mortgage rates are now falling again. They will almost certainly not fall to pandemic lows, although we may soon see rates under 6.0 percent, which would be low by pre-Great Recession standards.”

Here are two reasons why this recent trend, and the expectation it’ll continue, is such good news for you.

You May Not Feel as Locked-In to Your Current Mortgage Rate

With mortgage rates already significantly lower than they were just a few months ago, you may feel less locked-in to the current mortgage rate you have on your house. When mortgage rates were higher, moving to a new home meant possibly trading in a low rate for one up near 8%.

However, with rates dropping, the difference between your current mortgage rate and the new rate you’d be taking on isn’t as big as it was. That makes moving more affordable than it was just a few months ago. As Lance Lambert, Founder of ResiClub, explains:

“We might be at peak “lock-in effect.” Some move-up or lifestyle sellers might be coming to terms with the fact 3% and 4% mortgage rates aren’t returning anytime soon.”

More Buyers Will Be Coming to the Market

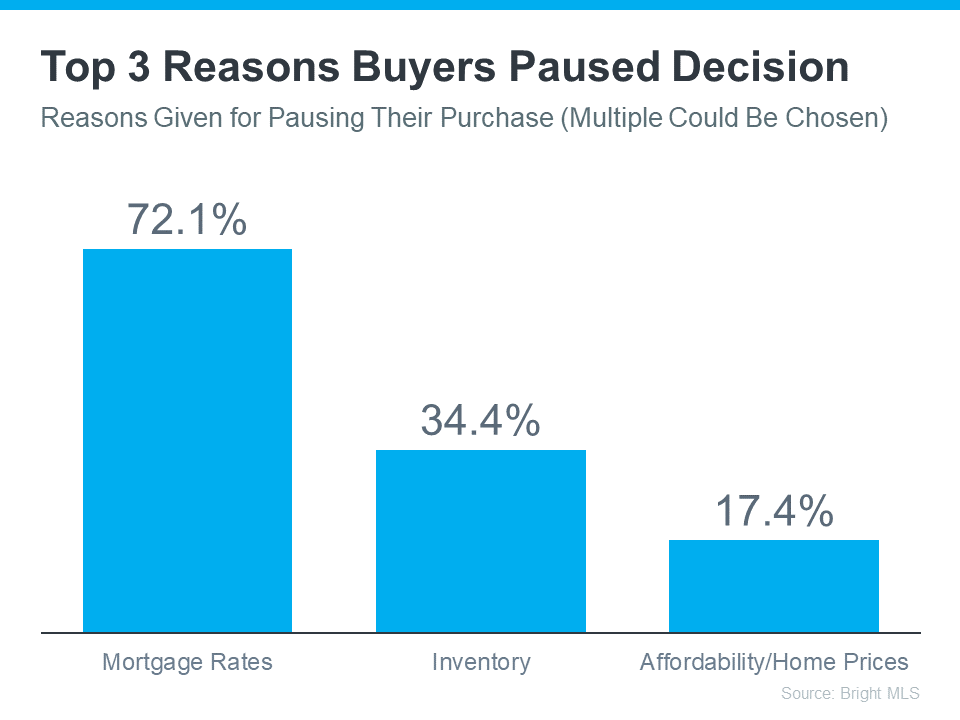
According to data from Bright MLS, the top reason buyers have been waiting to take the plunge into homeownership is high mortgage rates (see graph below):

Lower mortgage rates mean buyers can potentially save money on their home loans, making the prospect of purchasing a home more attractive and affordable. Now that rates are easing, more buyers are likely to feel they’re ready to jump back into the market and make their move. And more buyers mean more demand for your house.

Bottom Line

If you’ve been waiting to sell because you didn’t want to take on a larger mortgage rate or you thought buyers weren’t out there, the recent decline in mortgage rates may be your sign it’s time to make your move. When you’re ready, connect with a local real estate agent.

Jan. 29, 2024

Why You May Want To Seriously Consider a Newly Built Home

Why You May Want To Seriously Consider a Newly Built Home

Are you putting off your plans to sell because you’re worried you won’t be able to find a home you like when you move? If so, it may be time to consider a newly built home and the benefits that come with one. Here’s why.

Near-Record Percentage of New Home Inventory

Newly built homes are becoming an increasingly significant part of today’s housing inventory. According to the most recent report from the National Association of Home Builders (NAHB):

“Newly built homes available for sale accounted for 31% of total homes available for sale in November, compared to an approximate 12% historical average.”

That means the percentage of the total homes available to buy that are newly built is well over two times higher than the norm. And even more new homes are on the way.

Recent data from the Census shows there’s been an uptick in both housing starts (where builders break ground on more new homes) and housing completions (homes where construction just wrapped).

And while some people may worry builders are building too many homes, that isn’t a concern – if anything, the recent increase is really good news. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

“Even more home building will be needed with the housing shortage persisting in most markets . . . Another 30% rise in home construction can easily be absorbed in the marketplace . . .”

How This Helps You 

Since the supply of existing homes for sale is still low right now, the increase of new-home construction can be a game changer because it gives you more options for your search.

Picture yourself in a home that’s new from the ground up: new appliances, fresh paint, fewer maintenance needs because everything is new, and so much more. Doesn’t that sound nice?

And it may be more within reach than you ever imagined. In addition, some builders are offering things like mortgage rate buy-downs for homebuyers right now. This can help offset today’s affordability challenges while also getting you into your dream home. In a recent article, Patrick Duffy, Senior Real Estate Economist at U.S. News, explains:

“Builders have been using mortgage interest rate buydowns for many years as a sales incentive whenever interest rates are relatively high, . . .Today more builders are offering rate buydowns for the entirety of the loan, allowing buyers to finance more home for the same payment amount.”

Just remember, the process of buying from a builder is different from buying from a home seller, so it’s important to partner with a trusted real estate agent who knows the local market. They’ll be your go-to resource for coordinating with the builder, reviewing contracts, and more.

Bottom Line

If you’re trying to sell so you can make a move but you’re having a hard time finding a home you like, connect with a local real estate agent to explore all of your options, including the newly built homes in our area.

Jan. 28, 2024

Homeownership Is Still at the Heart of the American Dream

Homeownership Is Still at the Heart of the American Dream

Buying a home is a powerful decision, and it remains at the heart of the American Dream. Unlike renting, owning a home means more than just having a place to live – it offers a sense of belonging, stability, and freedom. According to Nicole Bachaud, Senior Economist at Zillow:

“The American Dream is still owning a home. There’s a lot of pent-up demand for ownership; that isn’t going to go away.”

Let’s explore just a few of the reasons why so many Americans continue to value homeownership. 

The Financial Benefits of Owning a Home

One possible reason homeownership is viewed so highly is because owning a home is a significant wealth-building tool. That may be why Jessica Lautz, Deputy Chief and VP of Research at the National Association of Realtors (NAR), says:

“Homeownership is the number one way to build wealth in America.”

Over time, owning a home not only helps boost your own net worth, but it also sets future generations up for success as you pass that wealth down. Habitat for Humanity explains:

“Overall, homeownership promotes wealth building by acting as a forced savings mechanism and through home value appreciation. Homeowners make monthly payments that increase their equity in their homes by paying down the principal balance of their mortgage. . . . In addition, owning a home promotes intergenerational homeownership and wealth building. Children of homeowners transition to homeownership earlier — lengthening the period over which they can accumulate wealth . . .”

It can also provide meaningful financial stability compared to renting. When you buy with a fixed-rate mortgage, you can lock in your monthly housing payments for the length of your home loan.

The Non-Financial Benefits of Homeownership

But, owning a home offers more than just financial benefits—it benefits you socially and emotionally too. Your home provides feelings of achievement, responsibility, and more. In a recent survey, Fannie Mae outlines just a few of these more emotionally-driven benefits, including:

“The top three were having control over what you do with your living space (94%) to having a sense of privacy and security (91%) and having a good place for your family or to raise your children (90%) . . .”

What Does That Mean for You?

If your idea of the American Dream involves greater freedom, security, and prosperity, homeownership could be a key player in bringing that dream to life. And with mortgage rates now on a downward trend, it might be a good time for you to consider making a move.

If you’re ready and able to buy, know that there are incredible benefits waiting at the end of your journey. You’ll gain more than just a home – it’s a place to grow your wealth and call your very own. Like Ksenia Potapov, Economist at First American says:

“…homeownership remains an important driver of wealth accumulation and the largest source of total wealth among most households.”

Bottom Line

Buying a home is a powerful decision and the cornerstone of the American Dream. If finding a place to call your own is part of your dream for this year, connect with a local real estate advisor to start the process today.

Jan. 27, 2024

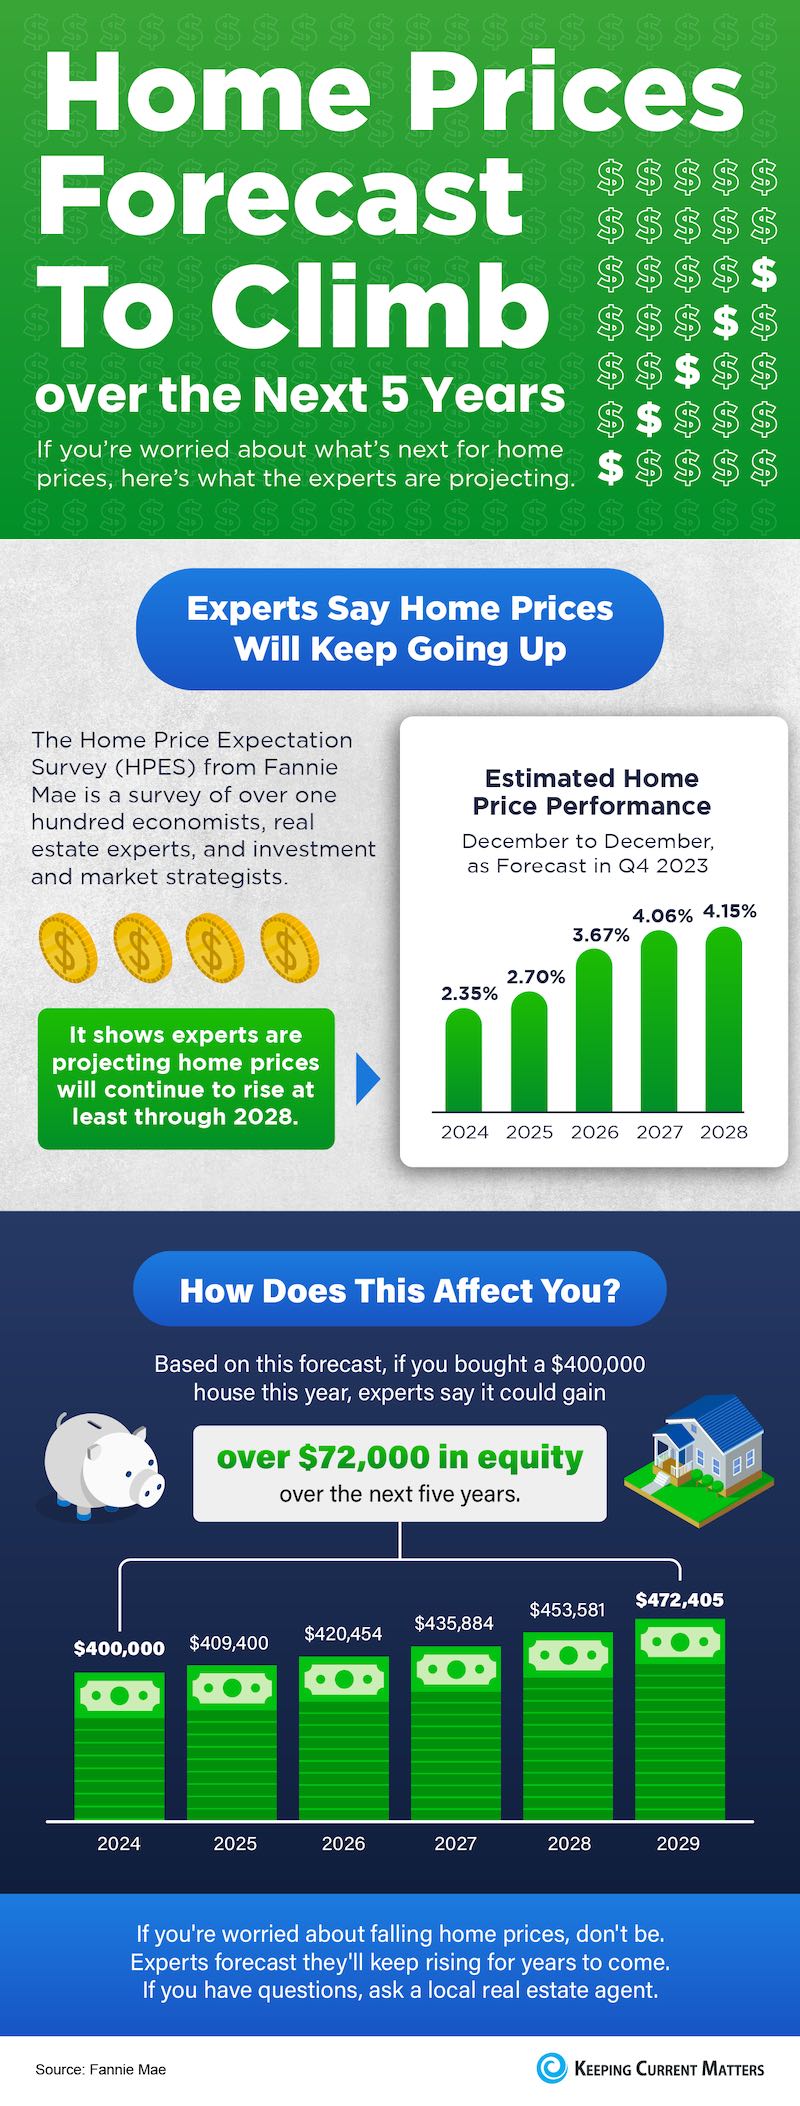
Home Prices Forecast To Climb over the Next 5 Years [INFOGRAPHIC]

Some Highlights

  • If you’re worried about what’s next for home prices, know the HPES shows experts are projecting they’ll continue to rise at least through 2028.
  • Based on that forecast, if you bought a $400,000 house this year, experts say it could gain over $72,000 in equity over the next five years. 
  • If you're worried about falling home prices, don't be. Many experts forecast they'll keep rising for years to come. If you have questions, ask a local real estate agent.
Jan. 26, 2024

Avoid These Common Mistakes After Applying for a Mortgage

Avoid These Common Mistakes After Applying for a Mortgage


If you’re getting ready to buy a home, it’s exciting to jump a few steps ahead and think about moving in and making it your own. But before you get too far down the emotional path, there are some key things to keep in mind after you apply for your mortgage and before you close. Here’s a list of things to remember when you apply for your home loan.

Don’t Deposit Large Sums of Cash

Lenders need to source your money, and cash isn’t easily traceable. Before you deposit any cash into your accounts, discuss the proper way to document your transactions with your loan officer.

Don’t Make Any Large Purchases

It’s not just home-related purchases that could disqualify you from your loan. Any large purchases can be red flags for lenders. People with new debt have higher debt-to-income ratios (how much debt you have compared to your monthly income). Since higher ratios make for riskier loans, borrowers may no longer qualify for their mortgage. Resist the temptation to make any large purchases, even for furniture or appliances.

Don’t Cosign Loans for Anyone

When you cosign for a loan, you’re making yourself accountable for that loan’s success and repayment. With that obligation comes higher debt-to-income ratios as well. Even if you promise you won’t be the one making the payments, your lender will have to count them against you.

Don’t Switch Bank Accounts

Lenders need to source and track your assets. That task is much easier when there’s consistency among your accounts. Before you transfer any money, speak with your loan officer.

Don’t Apply for New Credit

It doesn’t matter whether it’s a new credit card or a new car. When your credit report is run by organizations in multiple financial channels (mortgage, credit card, auto, etc.), it will have an impact on your FICO® score. Lower credit scores can determine your interest rate and possibly even your eligibility for approval.

Don’t Close Any Accounts

Many buyers believe having less available credit makes them less risky and more likely to be approved. This isn’t true. A major component of your score is your length and depth of credit history (as opposed to just your payment history) and your total usage of credit as a percentage of available credit. Closing accounts has a negative impact on both of those parts of your score.

Do Discuss Changes with Your Lender

Be upfront about any changes that occur or you’re expecting to occur when talking with your lender. Blips in income, assets, or credit should be reviewed and executed in a way that ensures your home loan can still be approved. If your job or employment status has changed recently, share that with your lender as well. Ultimately, it’s best to fully disclose and discuss your intentions with your loan officer before you do anything financial in nature.

Bottom Line

You want your home purchase to go as smoothly as possible. Remember, before you make any large purchases, move your money around, or make major life changes, be sure to consult your lender – someone who’s qualified to explain how your financial decisions may impact your home loan.