Real Estate & Community News

May 12, 2026

Why Staging Your House Could Pay Off This Spring

Why Staging Your House Could Pay Off This Spring

Selling your house this season? You’ve probably heard you should stage it before it hits the market. But what does that really mean – and is it worth the effort?

The short answer is “yes,” especially right now.

With more houses for sale this year, you’re likely wondering how to make the most money possible without your house sitting on the market. The answer is staging. It can help your house stand out, bring in stronger offers, and sell faster. As Nadia Evangelou, Principal Economist at the National Association of Realtors (NAR), puts it:

“Staging matters. Preparing the home to be ‘buyer-ready’ attracts more buyers, especially now that inventory has increased.”

Here’s what staging actually involves and what it could do for your sale.

What Is Home Staging?

Home staging is the process of preparing your house, so it appeals to as many buyers as possible. That usually means decluttering, deep cleaning, rearranging furniture, and adding simple touches that help each room feel bright, open, and welcoming.

The goal is to help buyers fall in love with the space and picture themselves living there, which makes them more likely to make an offer.

Why Staging Is Worth the Effort

Staged houses tend to perform better on almost every metric that matters when you sell. According to Redfin, staged homes have been shown to sell up to 73% faster than unstaged homes. And they often close in under a month, compared to anywhere from two to three months for vacant ones.

There’s also a strong return on the money you spend.

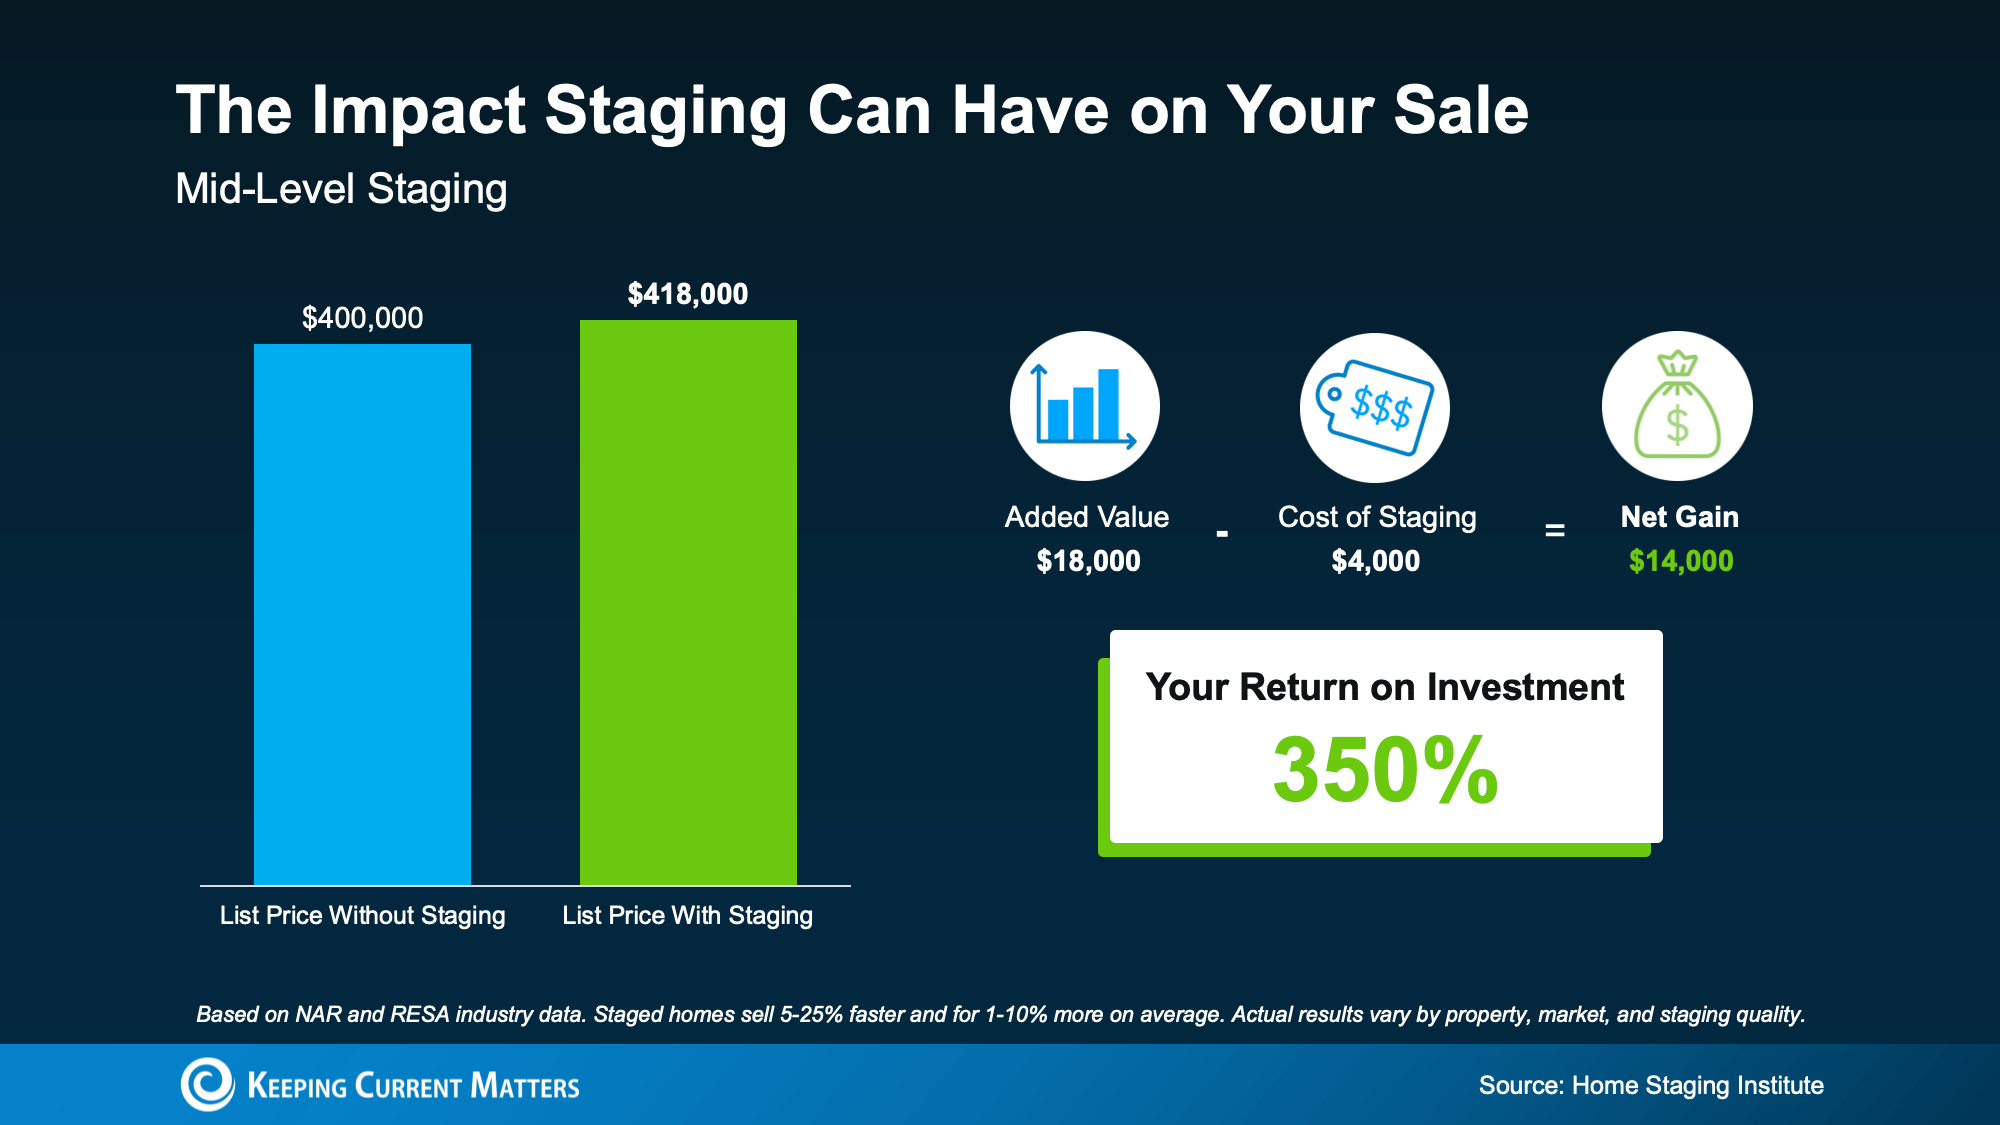
The Home Staging Institute says mid-level staging can deliver a 350% return on investment. On a $400k home, that turns the typical $4k cost into roughly $18k in added value when you sell (see graph below):
a screenshot of a sales report

By that estimate, that’s an extra potential profit of about $14k – a meaningful boost when you’re trying to maximize what you walk away with at closing.

Your Staging Options

And just in case you’re seeing that $4k upfront investment above and thinking, “I’m not going to spend that,” here’s what you should know.

Staging doesn’t always have to mean hiring a full crew or filling your house with rented furniture. There are a few different paths you can take, depending on your budget and timeline. So, you could spend a lot less and still get a good return. 

Here are a few options:

  • Professional staging. A stager handles everything from layout to décor, often bringing in their own inventory. According to the Home Staging Institute, costs typically range from $500 to $5k or more, depending on the size of your house.
  • Virtual staging. Digital furniture and styling are added to your listing photos, which can be a budget-friendly option for vacant houses.
  • DIY staging. If your budget is tight and your home only needs minor updates, decluttering, deep cleaning, and arranging furniture for flow can still make a real difference.

Your agent can help you figure out which approach fits your house, your market, and your goals.

Agents see what buyers respond to in open houses and showings every week, so they can give you specific, personalized recommendations on what’s worth your time and money (and what isn’t).

That way you can get the most bang for your buck – no matter your budget.

Bottom Line

With more homes for sale right now, making a strong first impression matters. Staging can help your house sell faster and for more – and there's an option for almost every budget.


If you're getting ready to list, connect with a local real estate agent to talk through what level of staging makes the most sense for your house.
Posted in For Sellers
May 11, 2026

3 Things That Are Not Going To Happen in Today's Housing Market

3 Things That Are Not Going To Happen in Today

There’s a lot of uncertainty right now and that’s leading to some dramatic headlines. And if you’re thinking about buying a home, that can make you feel a little less sure about your decision.

A recent study by CNBC asked homebuyers what they’re most worried about, and three themes kept coming up again and again:

  • Mortgage rates
  • The number of homes for sale
  • Home prices

But a lot of what you may be hearing on those is based more on misconceptions. Not facts. So, let’s break it down and separate fact from fiction.

Misconception #1: “I’ll Just Wait, Because Mortgage Rates Are Going To Fall Dramatically”

One idea doing its rounds on social is that mortgage rates are going to drop dramatically soon. So, it’s better to wait to buy.

But is that really what’s expected?

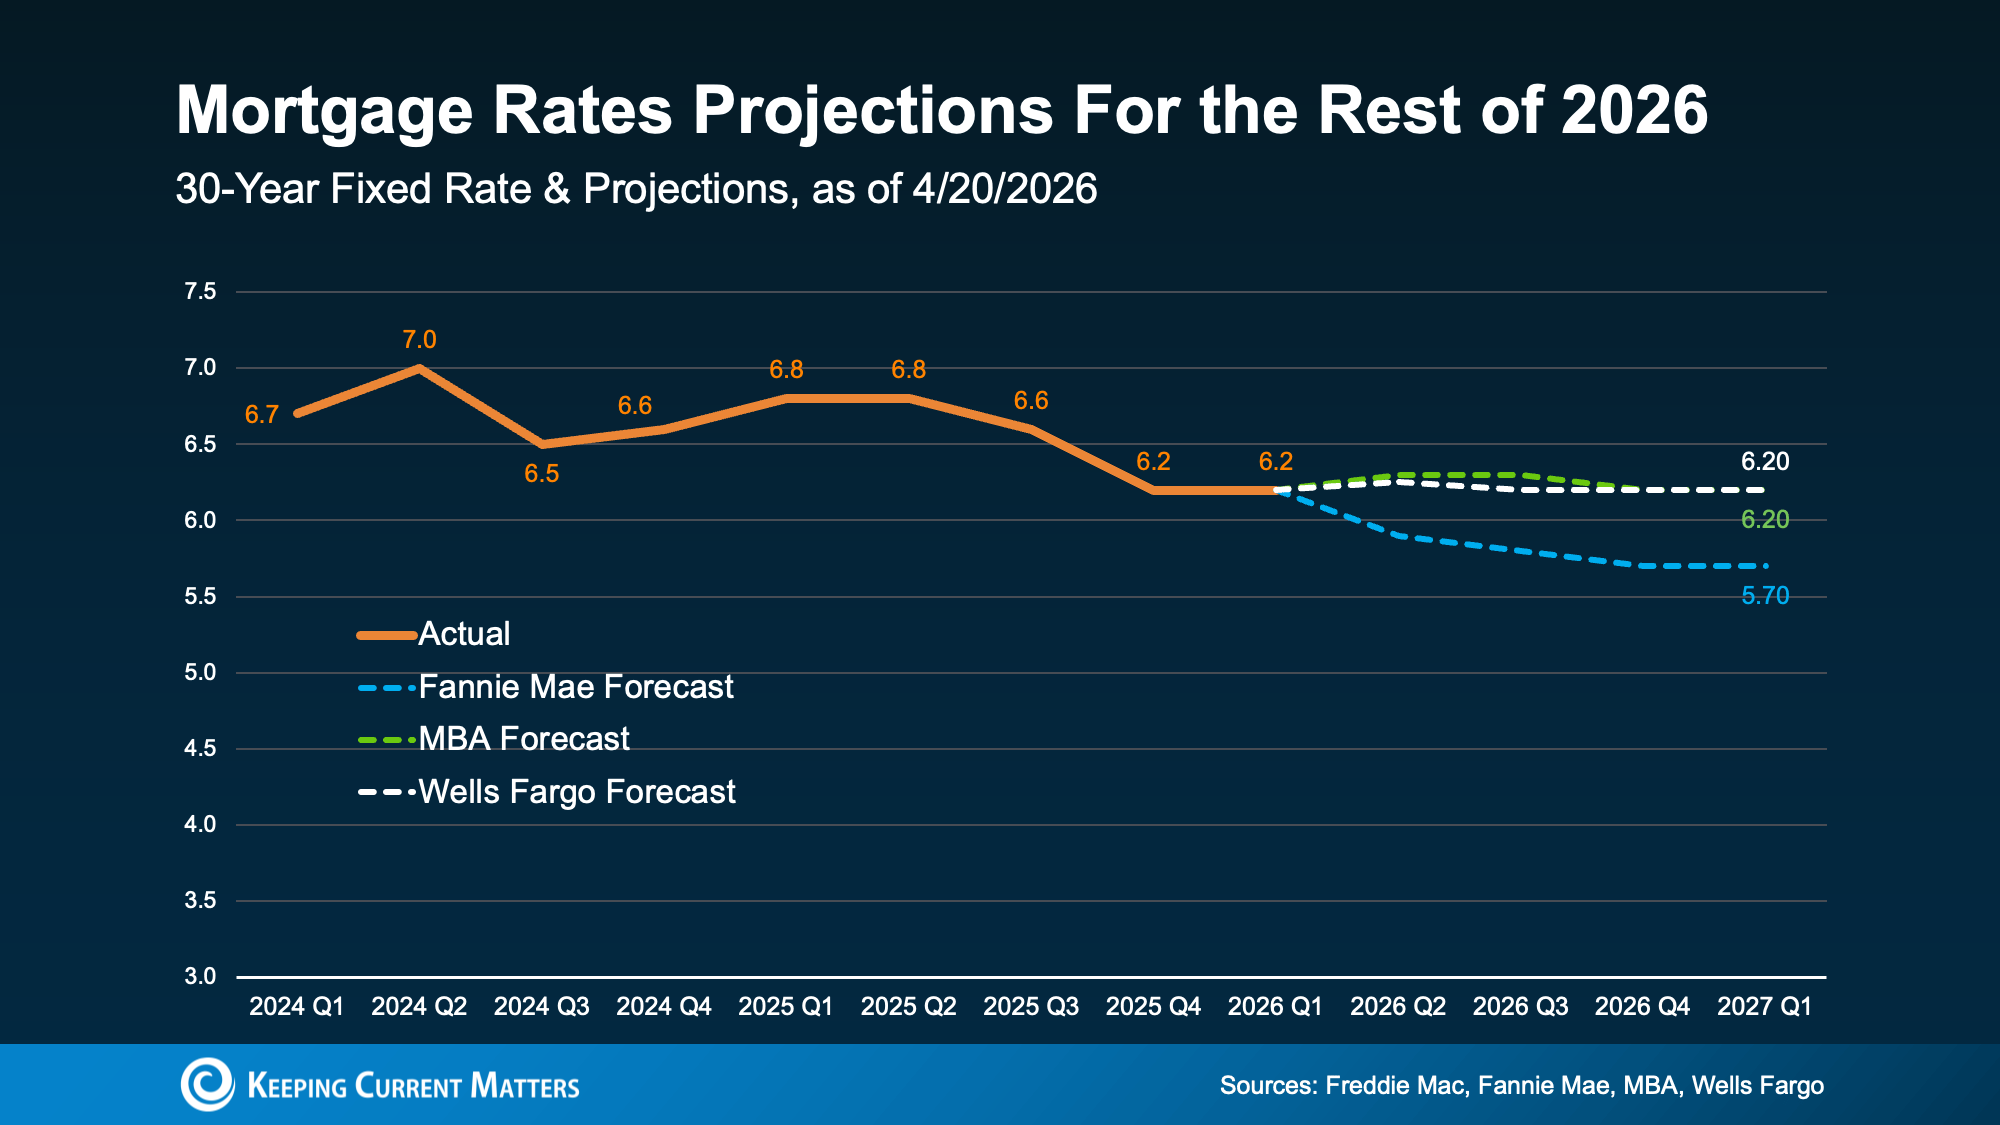
While mortgage rates have come down a bit in the last few weeks, forecasts don’t show a major drop ahead. The most likely scenario is that rates stay somewhere in the low 6% range this year. 

And that’s not a big change from where rates are now (see graph below): 

a graph with numbers and lines

Of course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:

“Mortgage rates aren’t expected to change much over the next several quarters . . .”

Not to mention, even with rates where they are today, it’s already more affordable than a year ago. So, even if they don’t change much, it’s still better than it was.

Misconception #2: “There Are Too Many Homes for Sale Right Now”

You’ve probably heard inventory is up. And nationally, it is. The number of homes for sale is 8% higher than this time last year. But that’s not a bad thing. In fact, it’s one of the reasons buyers have a bit more breathing room right now.

The problem is the headlines are making something good, sound bad. They’re focusing on how this is the most inventory we’ve had since 2019 or how many homes builders are building. And that can make it sound like the number of homes for sale is rising too far, too fast.

But that’s not what the bigger picture shows.

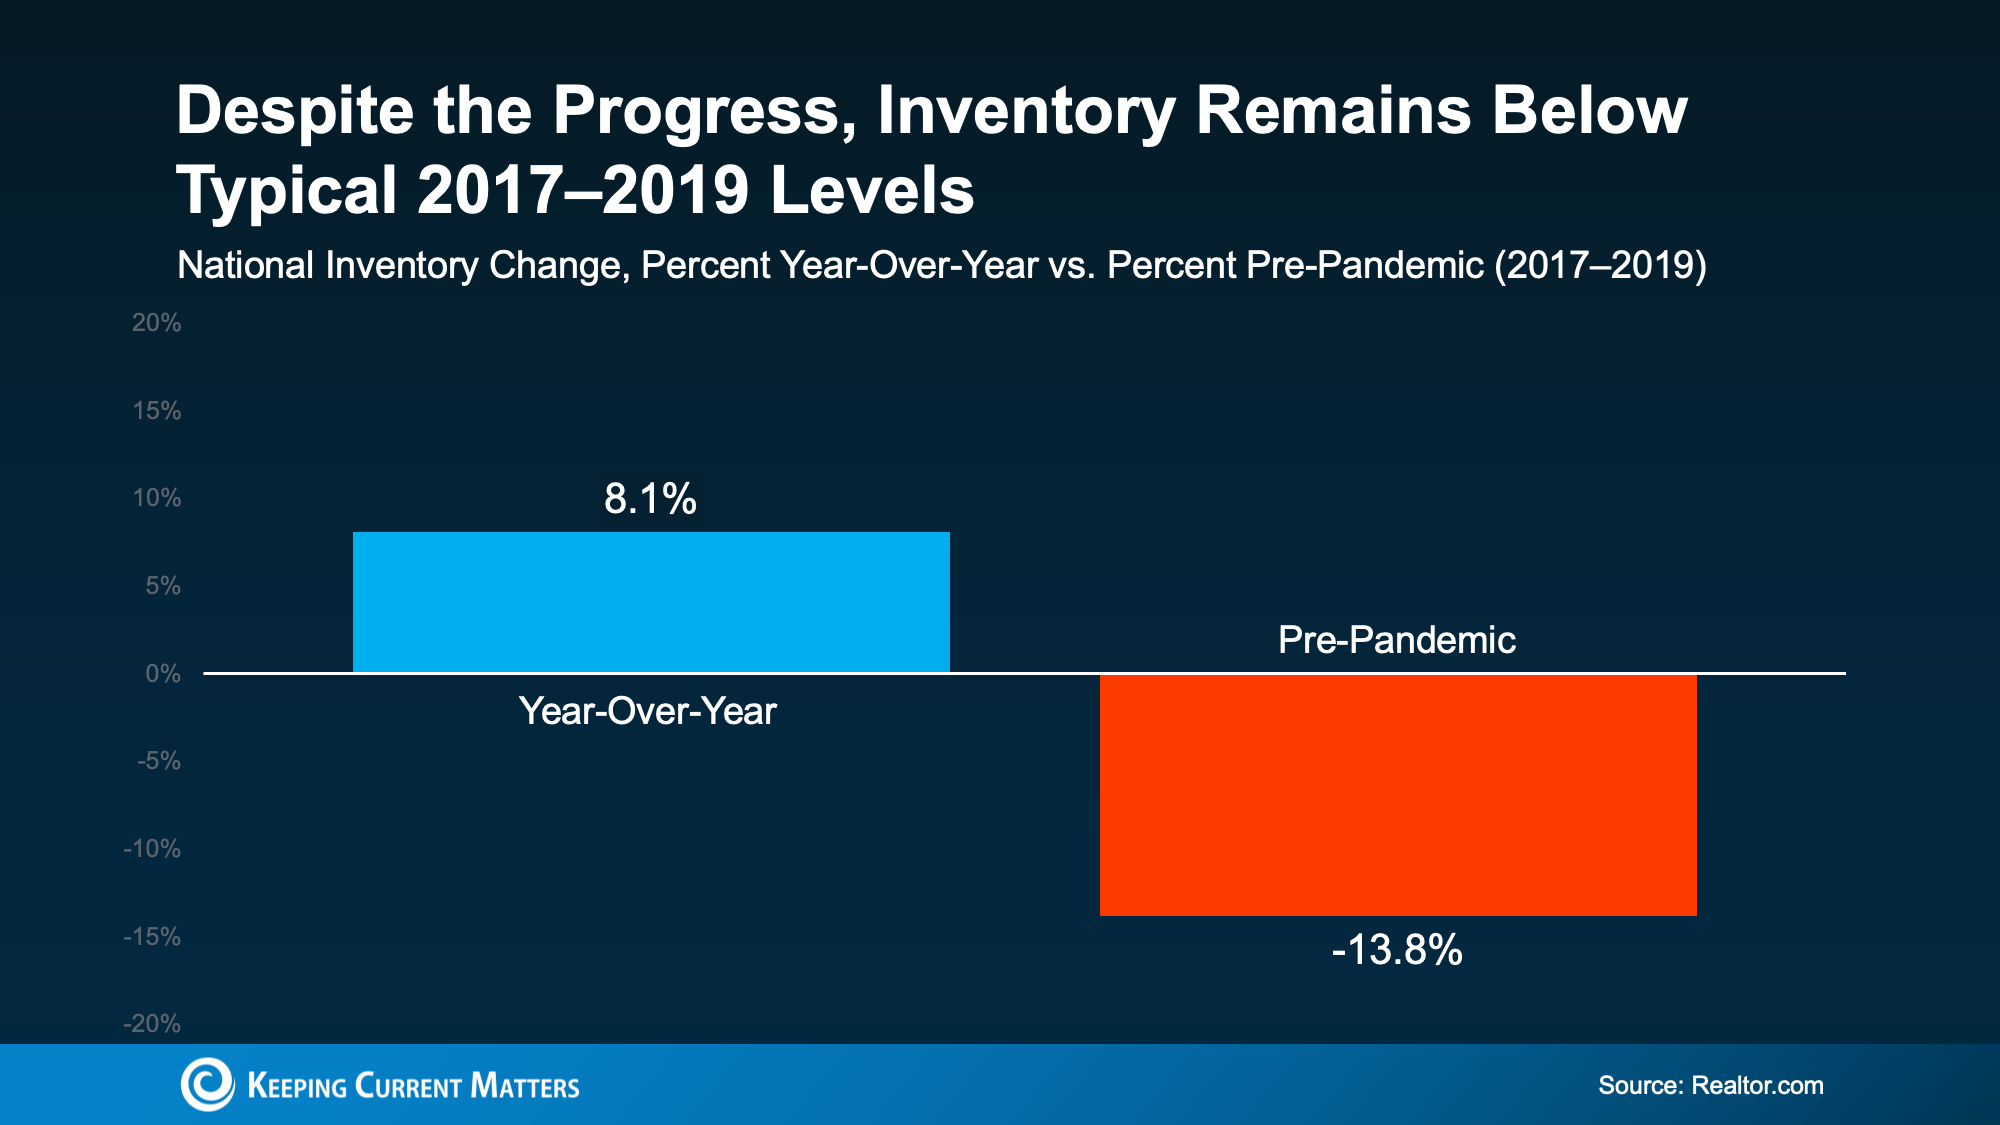
Data from Realtor.com proves that, even though inventory is up compared to last year, it’s still nearly 14% lower than it was during the last normal housing market (2017-2019):

While it can vary a lot based on where you live, only 9 states have more inventory than pre-pandemic today. That’s a key reason why there still aren’t enough homes for sale to trigger something like the crash back in 2008.

Misconception #3: “Home Prices Are About To Crash”

You’ve probably seen this one, too. The confusion is coming from the fact that some metros are experiencing slight price declines. And influencers are running with that and saying prices are crashing. But that’s not the reality.

Most areas are seeing prices rise, not fall. And that’s because:

  • Many homeowners aren’t selling because they don’t want to give up the low mortgage rate they locked in a few years ago. And that’s keeping a lid on how much inventory can grow.
  • Since inventory is still below pre-pandemic norms, there aren’t enough homes for sale to cause a price crash.
  • And even in markets with more inventory, some sellers are choosing to pull their homes off the market instead of cutting prices.

And those are 3 big reasons prices aren’t headed for a crash. 


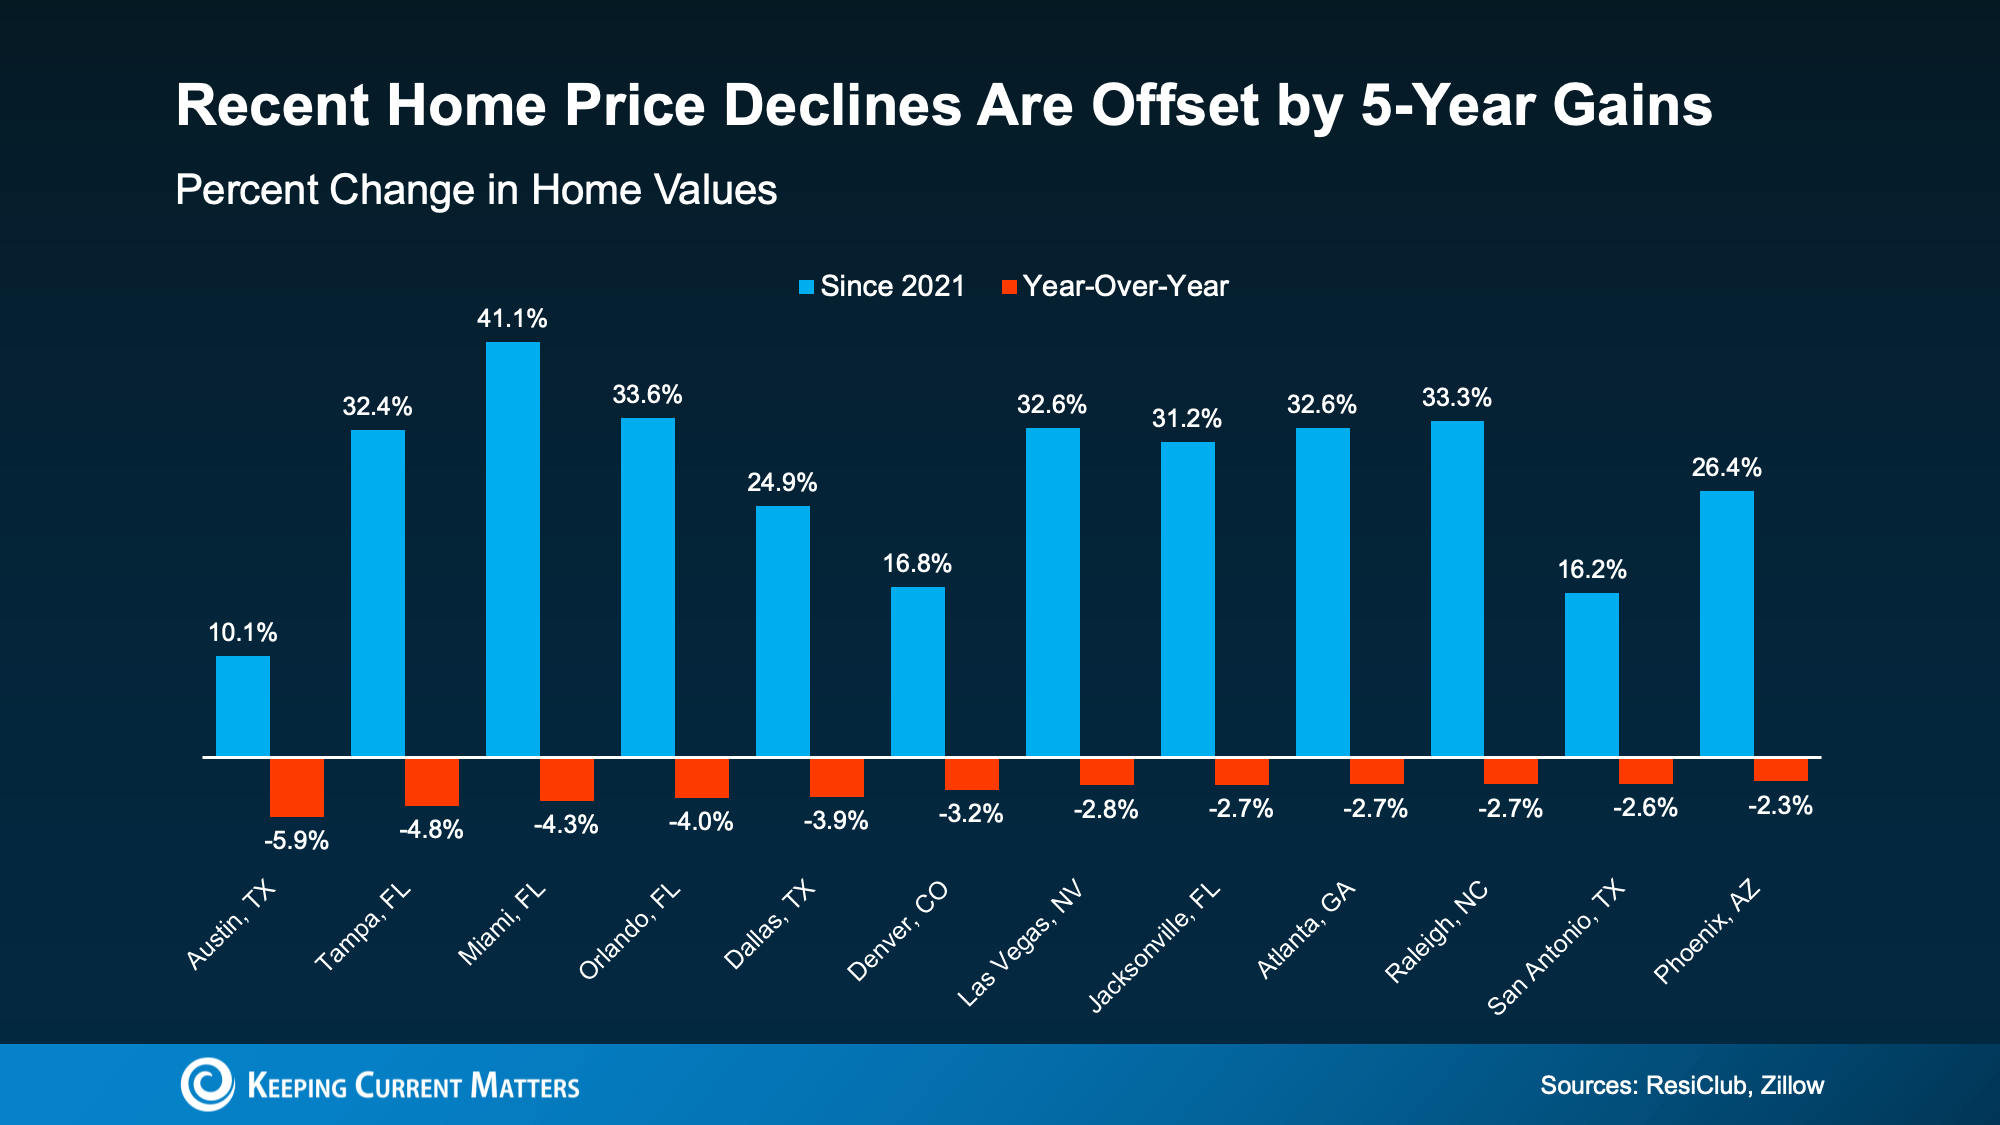
And even in the markets experiencing mild declines, the drops aren’t enough to cancel out the big gains most homeowners have seen in the last 5 years (see graph below):

That’s not a crash. That’s just prices moderating after a few record-breaking years.

Bottom Line

Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent.

Connect with a local agent so you have someone to separate fact from fiction today.

Posted in For Buyers, For Sellers
May 9, 2026

The Secret To Selling Fast, No Matter the Market

The Secret To Selling Fast, No Matter the Market

When you put your house on the market, you don’t just want it to sell. You want it to sell fast. But the thing is, nationally, it’s taking a little longer to sell lately. And that slowdown can feel frustrating if you want a fast process. Here’s what you need to realize.

In every market right now, there’s one clear exception:

Well-priced, well-presented homes are still selling, and it’s often faster than you’d expect.

If you can tap into that, you can still set yourself up to move quickly, too. Here’s how to get it done.

How Long It Takes To Sell Today

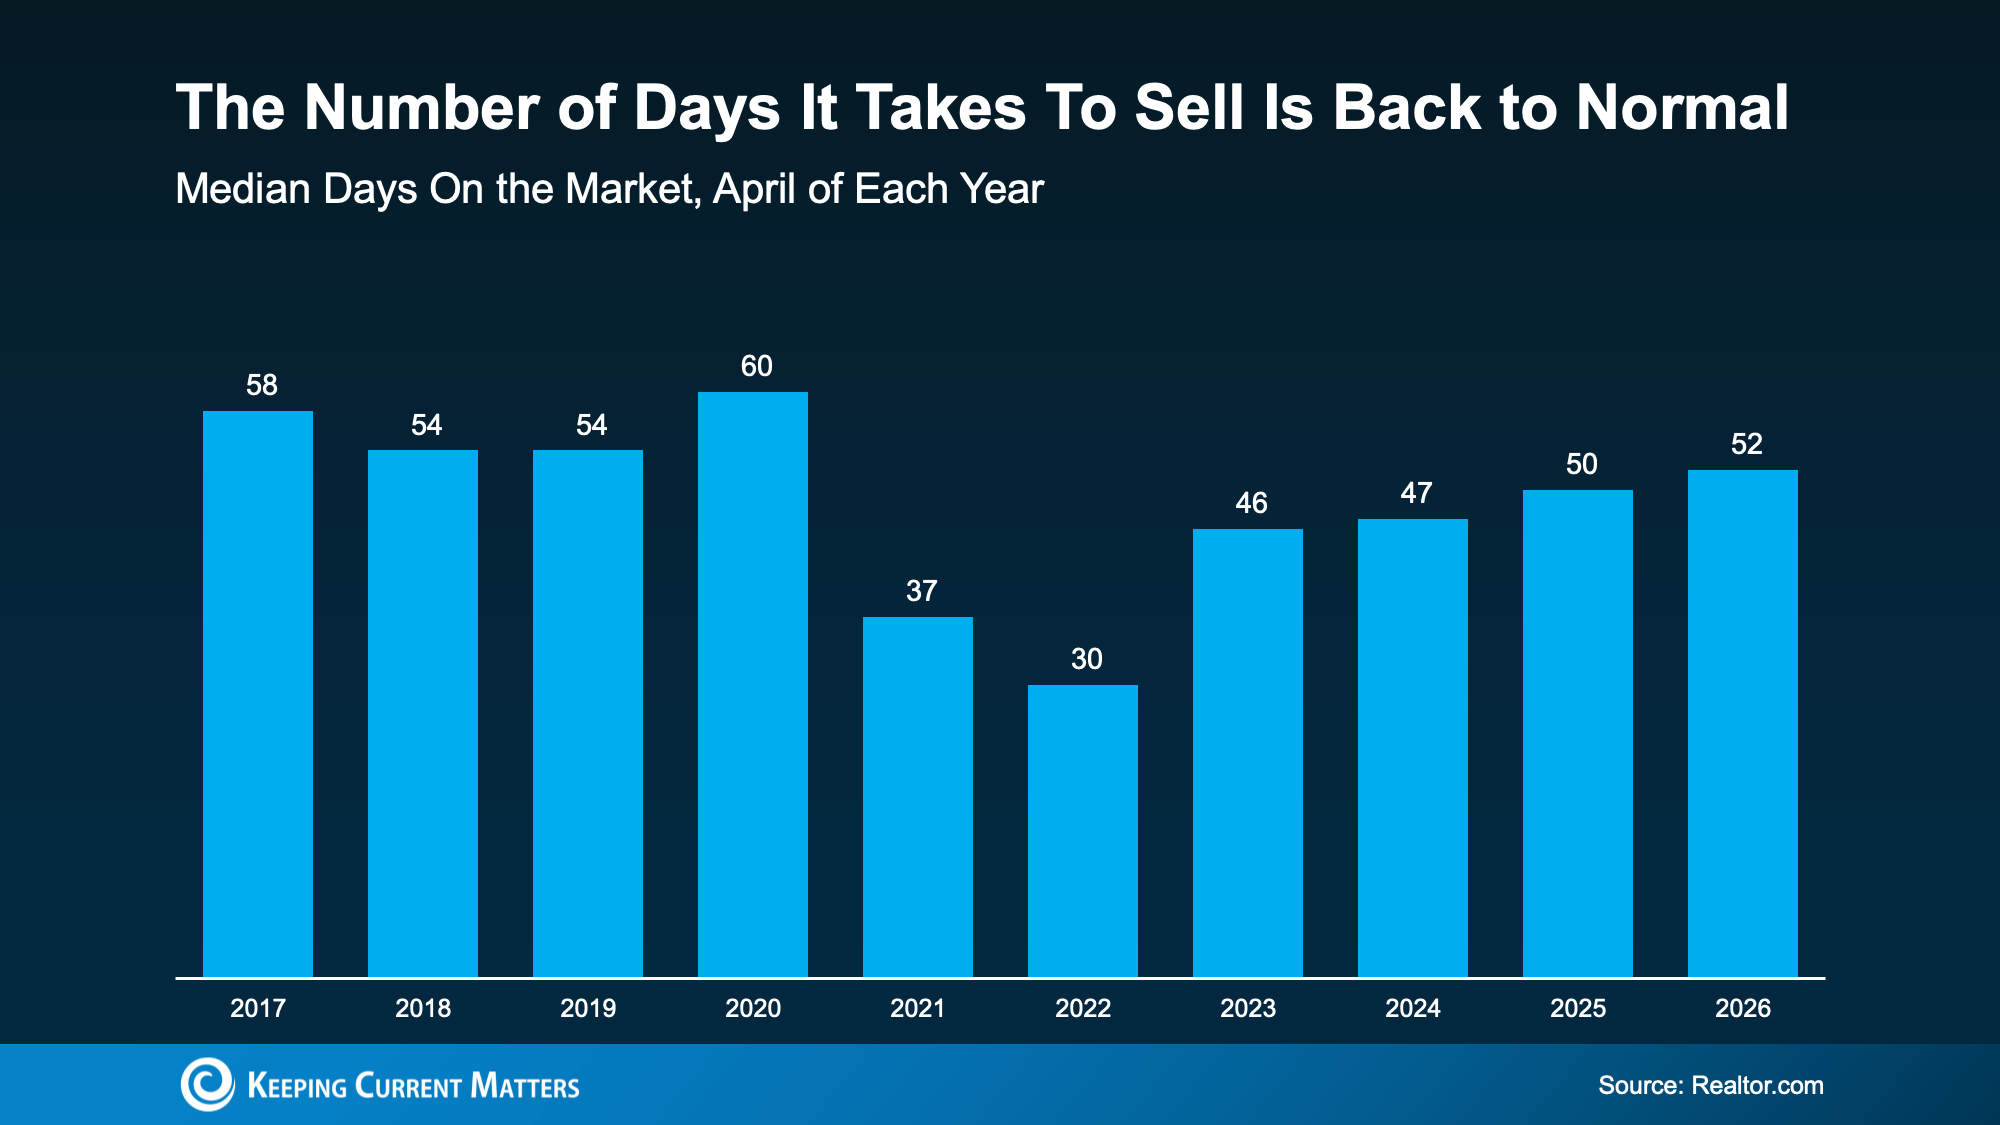
According to Realtor.com, homes are selling in about 52 days right now. That’s how long the process takes from the day it hits the market until closing day.

And while that may sound slow to you, it’s not slow. It’s normal.

That’s because it’s pretty much right in line with what it was during the last normal years in the market (see 2018-2019 in the graph below):

a graph of blue bars

It just feels slow when you’re eager to move – or when you think back a few years to when homes seemed to sell almost instantly.

But here’s what matters most. The market is normalizing. Not at a standstill.

This is the norm for timing from start to finish. You may have an accepted offer in hand even faster than this.

Markets Where Homes Still Sell Quickly, Even Now

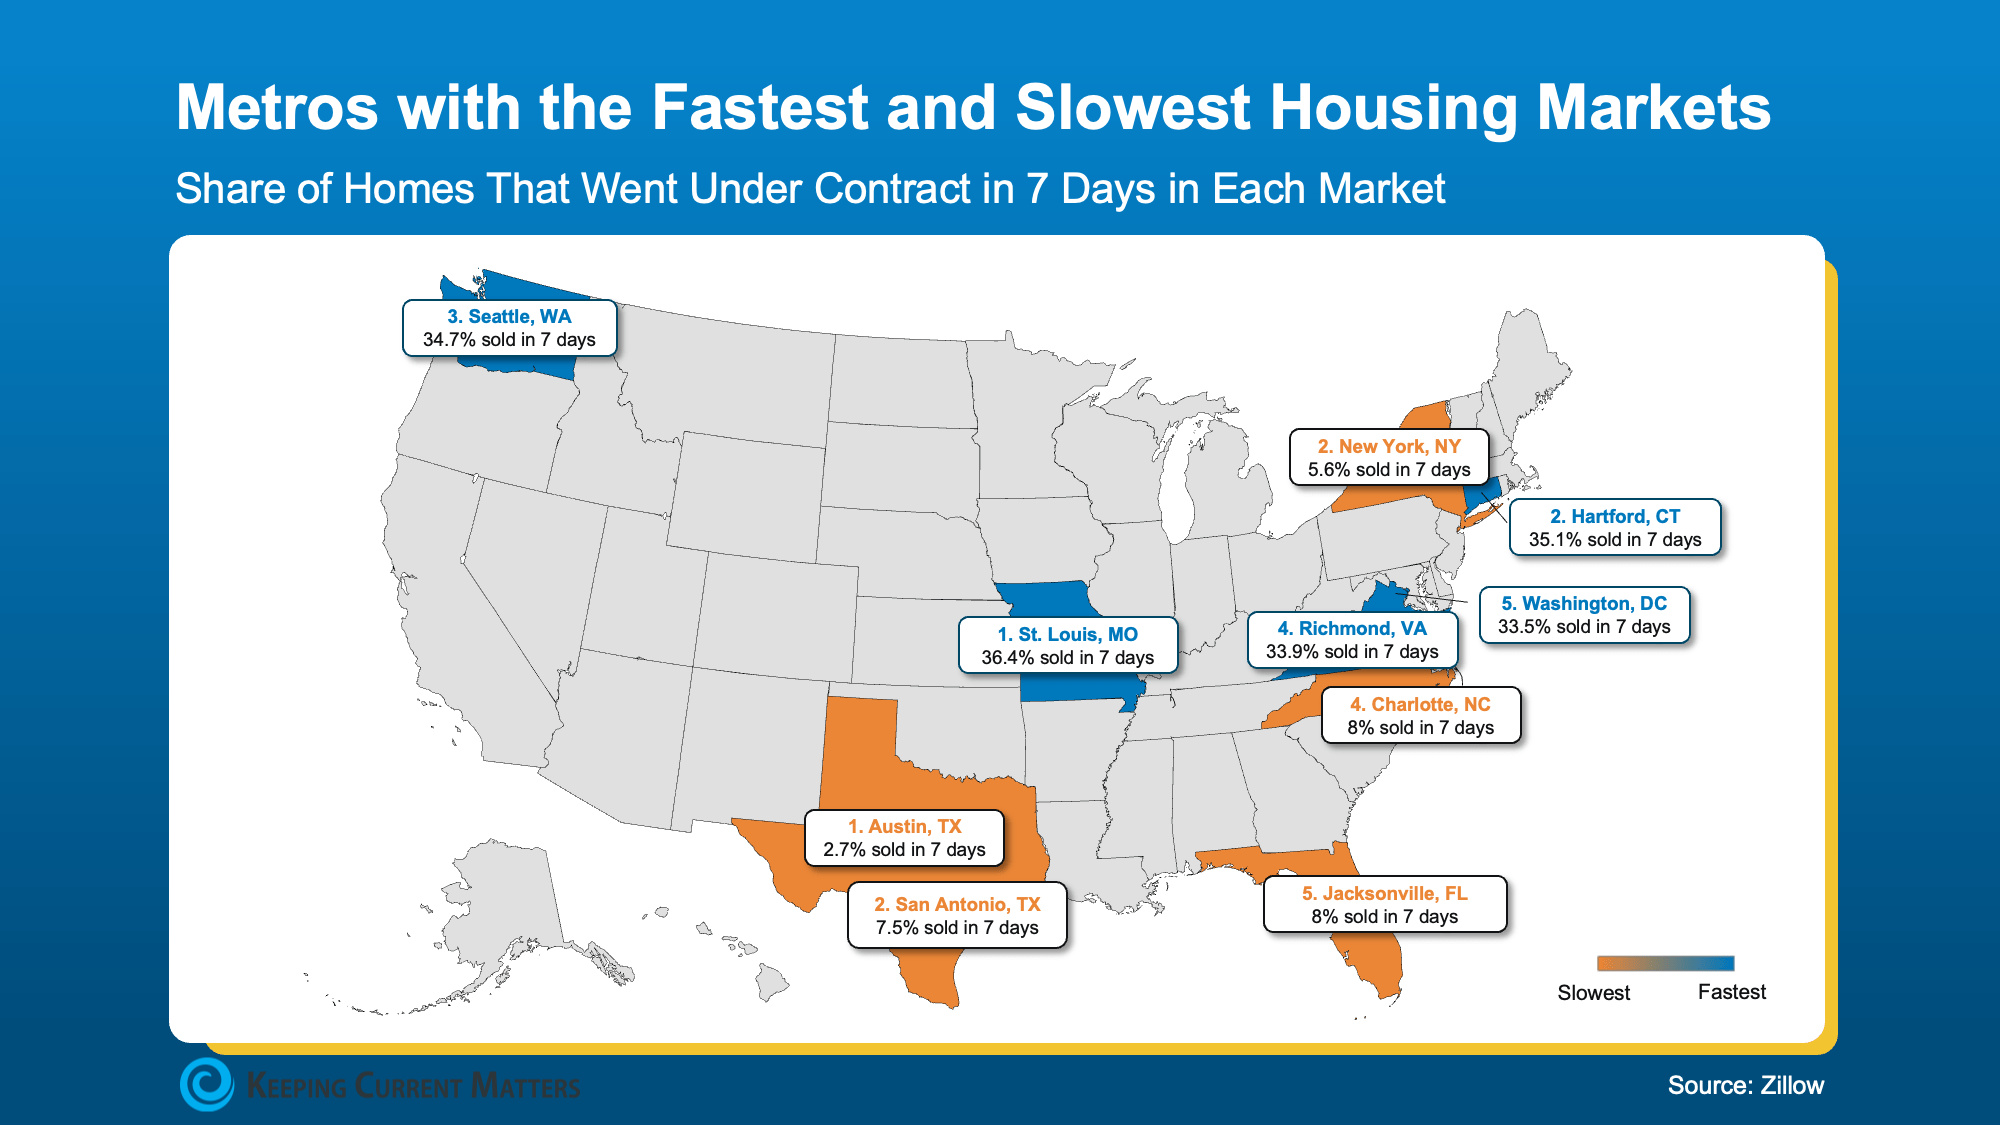
Zillow says the typical home will go “pending” or “under contract” in 19 days. Some homes even see it happen in as little as 7 days. It just depends on where you are – and how you prep your house.

So, don’t let the slowing pace of sales stress you out. Homes can still sell fast, if they’re positioned right.


Just to show you, here’s a quick look at some of the markets that are moving faster than the norm, according to Zillow (see map below). This’ll show you how different it can be based on where you live.

a map of the united states with numbers and a price tag

The key things you need to remember when looking at this visual:

  • It varies a lot based on where you live. Within the same state, individual neighborhoods or pockets may sell much faster than the norm.
  • Even in slower moving states, you can still sell quickly. As the map shows, in those places there are still homes that go under contract in as little as a week.

So don’t worry about if your state made either list. As Orphe Divounguy, Senior Economist at Zillow, says:

“The cream of the crop is still selling fast, even in markets that have slowed considerably. . .”

The Big Reasons Some Homes Sit, and Some Sell Fast

And here’s the big secret. While location can definitely play a role, it’s not just about location. It’s about strategy.

Today’s buyers are paying attention to condition. They’re comparing photos, upgrades, layout, location, and price. And they’re choosing homes that feel move-in ready and well worth the value.

The homes that check those boxes? They’re not sitting for long – no matter where they are.

As the Wall Street Journal (WSJ) explains:

“. . . some homes are still flying off the shelves. These houses are often in the Midwest or Northeast, where the lack of new construction keeps a lid on supply. Certain homes in other markets are selling quickly, too, often when a home is move-in ready.”

Because in any market – hot or not – if a home is overpriced, needs too much work, or just doesn’t meet current buyer expectations, it’s not going to sell. 

In this market, the sellers who win are the ones who get real about their house. They’re honest about how their home compares to other listings, realistic about price, and they work with an agent who truly understands today’s market and what it takes to sell.

When your agent knows how to price strategically, spotlight the strengths of your home, and move quickly when the market gives clear signals, that’s when the results follow.

Bottom Line

Today's housing market rewards the right strategy. Because even in a slower area, the homes that are priced realistically and positioned well are still selling – sometimes faster than you may expect.

Connect with a local agent if you’re ready to make yours one of them.

Posted in For Sellers
May 7, 2026

Could Co-Buying Be the Answer for Some First-Time Buyers?

Could Co-Buying Be the Answer for Some First-Time Buyers?

For a lot of would-be first-time buyers, affordability is the thing that’s standing in the way. But some buyers are getting creative and finding a way to still make the numbers work – and that’s through co-buying.

The Dream Is Still Alive. The Math Just Isn’t Working for Everyone.

Young people haven’t given up on the dream of owning a home – not even close. According to FirstHome IQ, homeownership still ranks among the top life goals for the next generation.

The problem? 73% of Gen Z and millennial buyers cite affordability as the reason for not making homeownership a priority. And it shows. First-time buyers now make up just 21% of all home purchases, the lowest share since the National Association of Realtors (NAR) started tracking the data in 1981.

But still, some buyers are making it happen. And a portion of them are turning to co-buying to get their foot in the door.

So, What’s Co-Buying?

Co-buying means purchasing a home with someone else, like a friend, sibling, or unmarried partner. You combine incomes, split the down payment, and share monthly costs. For some people, it’s a creative way to turn “someday” into a concrete move-in date that’s just around the corner.

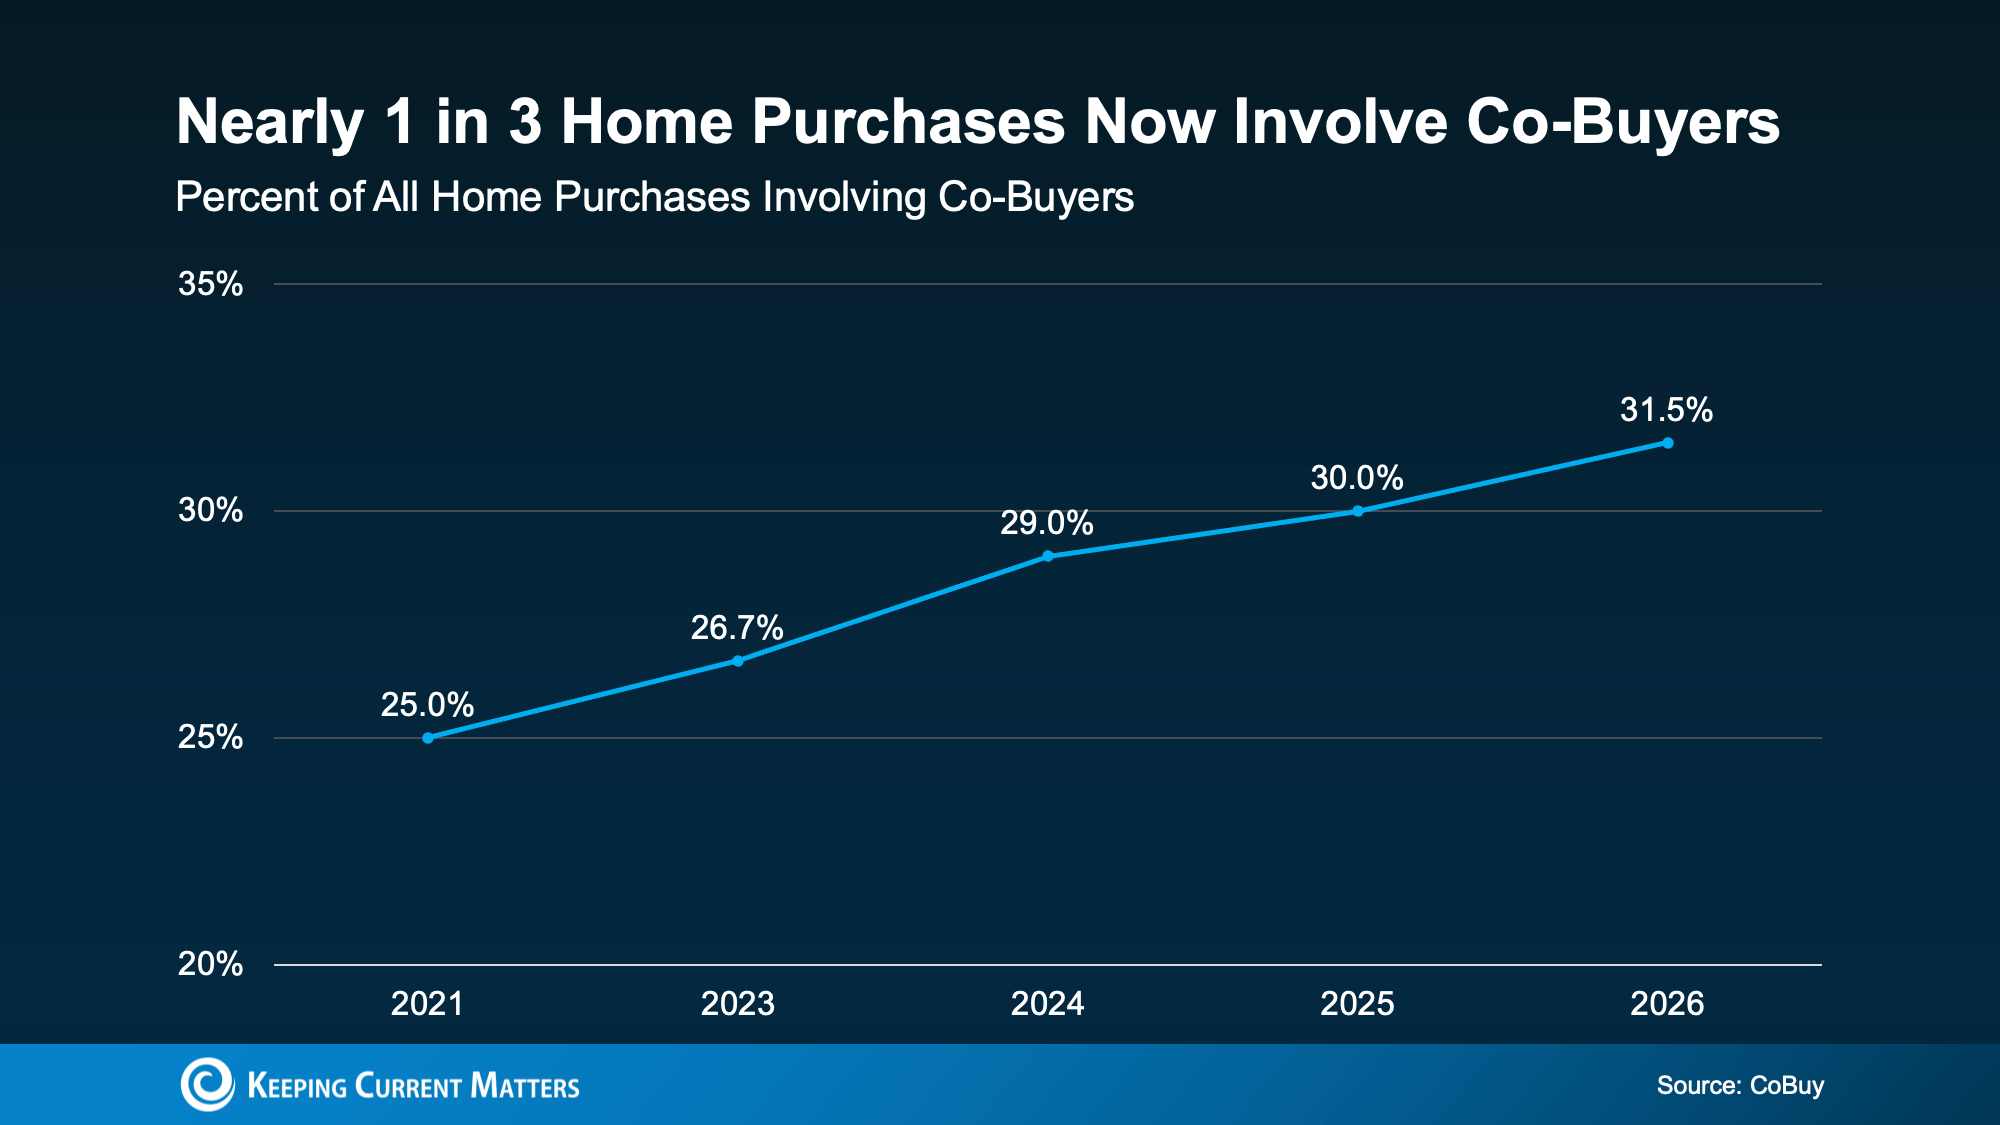
And it’s catching on fast, just look at where things stand today. According to CoBuy.io, 64 million Americans now co-own a home with someone they’re not married to. In fact, 31.5% of home purchases involve co-buyers (see graph below):

Why It Works

Here are just a few of the top reasons buyers are going this route, according to NerdWallet:

  • Quicker path to homeownership: If owning a home is a serious goal for you, buying with someone else can help make that reality on a shorter timeline. Two or more people can save up a down payment a lot faster than one. That’s less time waiting and more time building equity in a place that’s yours.
  • More purchasing power: With multiple incomes going toward the home purchase, you might be able to afford a nicer home or live in a more popular neighborhood. Sometimes teaming up means getting the home you actually want, not just the one you can barely afford on your own.
  • Easier loan qualification: Added income from more than one buyer can also help with your debt-to-income (DTI) ratio, which the lender will calculate based on all the borrowers.
  • Lower housing costs: Splitting up a mortgage payment multiple ways could maybe even make owning less expensive than renting. Plus, sharing costs can make repairs or renovations more manageable, too.

Things To Keep in Mind

If you’re considering going this route, there are some things you’ll want to think over. For starters, co-buying works best with people you trust and share financial goals with. So, before moving forward, make sure everyone agrees on how costs are split, who handles what, and what happens if one person wants to sell down the road.

That’s why a written co-ownership agreement can be a smart move. It keeps everyone on the same page and helps avoid headaches down the line. Think of it less like a legal formality and more like a game plan for your new investment.

Bottom Line

Affordability challenges are real, but they don't have to mean waiting indefinitely. Co-buying is helping some first-time buyers stop waiting and start putting down roots.

If you're curious whether it could work for your situation, talk with a local real estate agent. Reach out today and figure out your path to homeownership together.

Posted in For Buyers
May 3, 2026

Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t.

Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t.

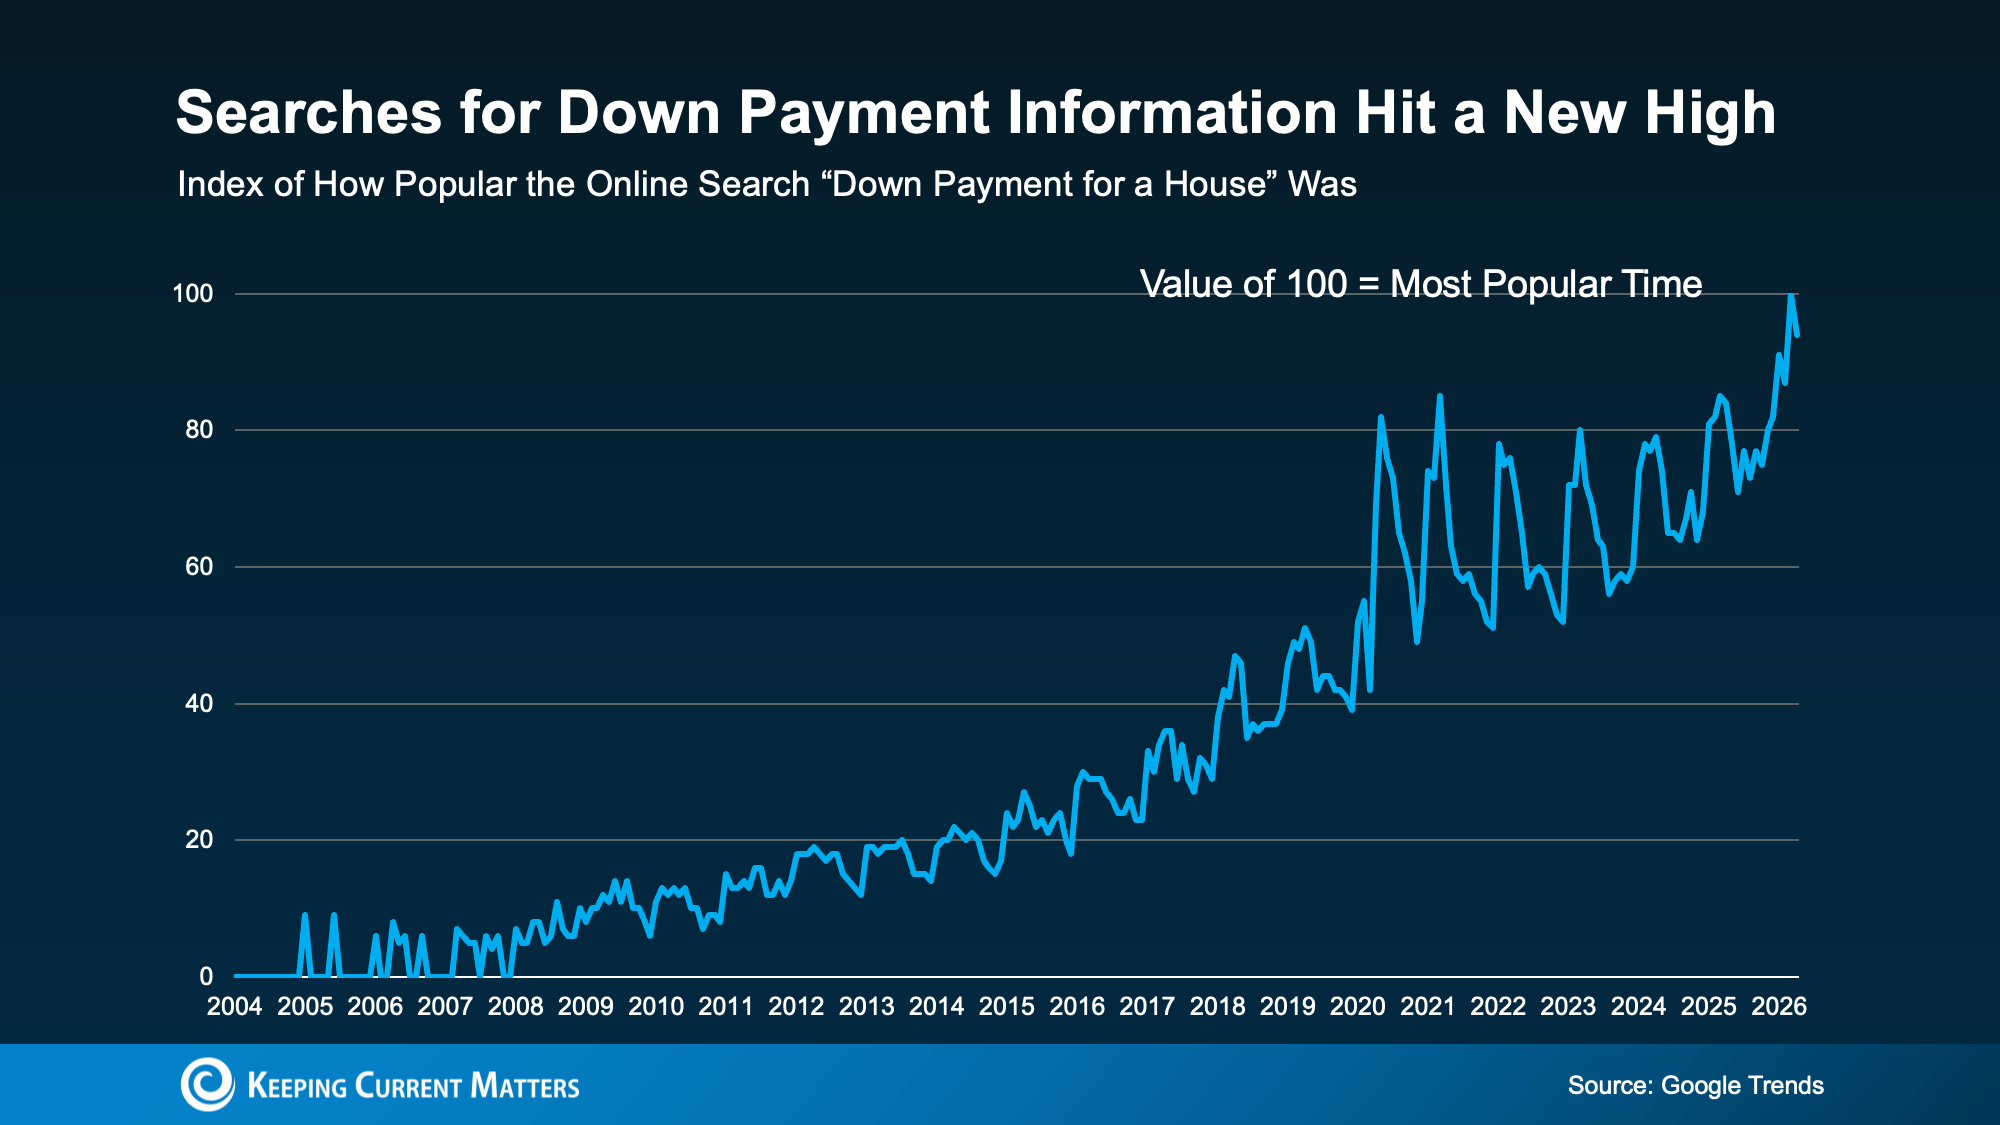
According to Google Trends, online searches for down payment information recently hit an all-time high. And that’s a clear sign more buyers are trying to figure out what they really need to save before making a move (see graph below):

a graph of a line graph

If you’re wondering the same thing, you can always turn to the internet for answers. But a lot of the time, it’s better to ask a local expert. Because here’s what a pro would tell you.

The 20% Down Payment Myth

The idea that you need 20% down to buy a home is one of the biggest misconceptions around the homebuying process. And the data debunks the myth.

While there are benefits to putting that much money down, most first-time buyers put down far less.

Here’s why. Unless it’s stated by your lender, you typically don’t have to have a 20% down payment. There are even some loan options designed to help you get into a home with a much smaller upfront cost. As the Mortgage Reports explains:

“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available, and you don’t need to put down the traditional 20% . . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . .

For example, FHA loans allow down payments as low as 3.5%, while VA and USDA loans offer zero down payment options for qualified applicants, like Veterans.

And those options are just one reason so many first-time buyers are able to buy without a 20% down payment.

What Buyers Are Actually Putting Down

So, if buyers aren’t doing 20%, how much do they actually put down?

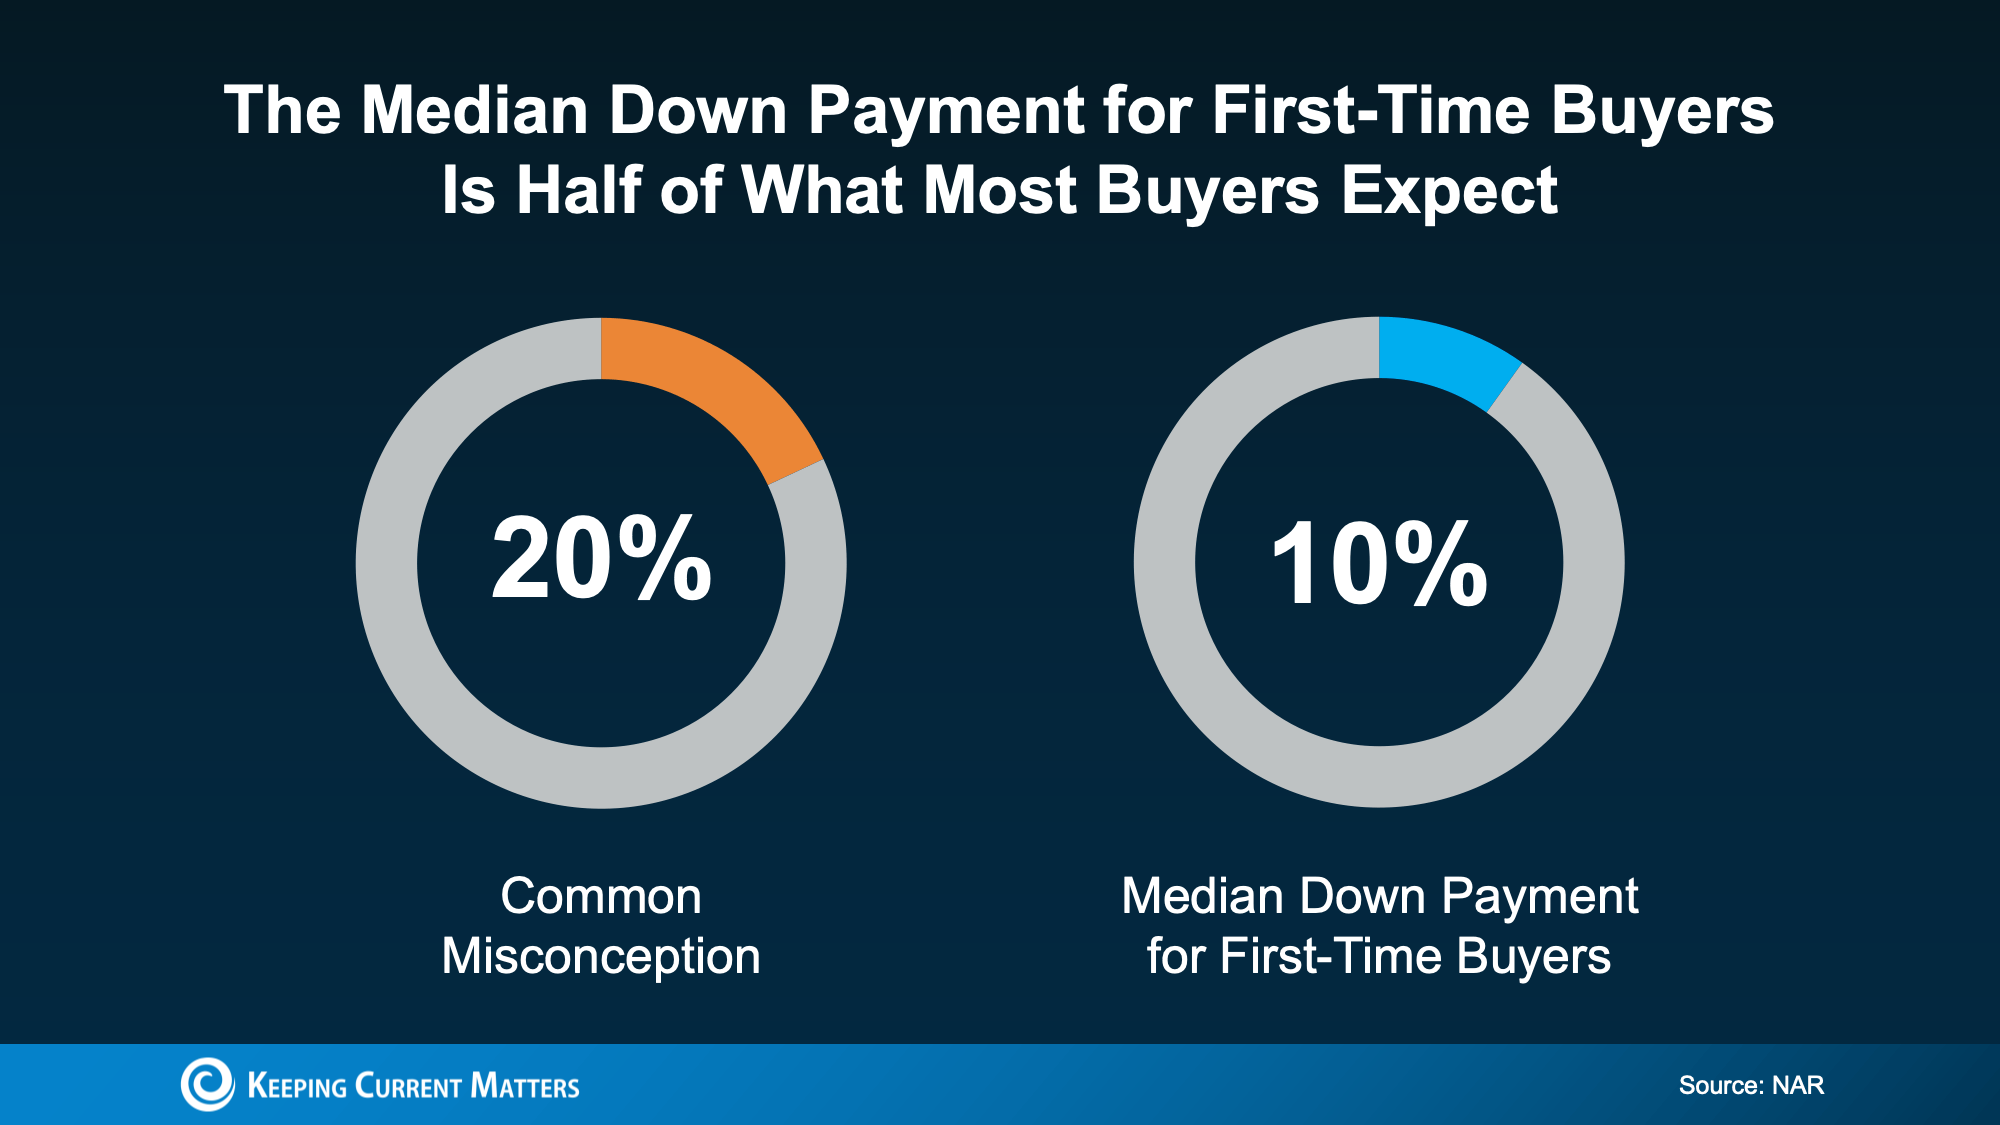
According to the National Association of Realtors (NAR), the median down payment for first-time homebuyers is only 10%. That’s half of what you probably expected.

a diagram of a pie chart

That means if you’re aiming to save 20% because you think you have to, you may be setting a timeline that’s longer than necessary.  

And here’s some more good news. It’s not only that you may be able to buy with less money down than you thought, but there are also options to help you get to your down payment goal even faster.

Why You Should Look into Down Payment Assistance Programs

There are a lot of programs designed to help you save for a down payment – and they can make a big difference in how fast you hit your savings target. Unfortunately, buyers don’t realize how many there are, or that they may qualify for help.


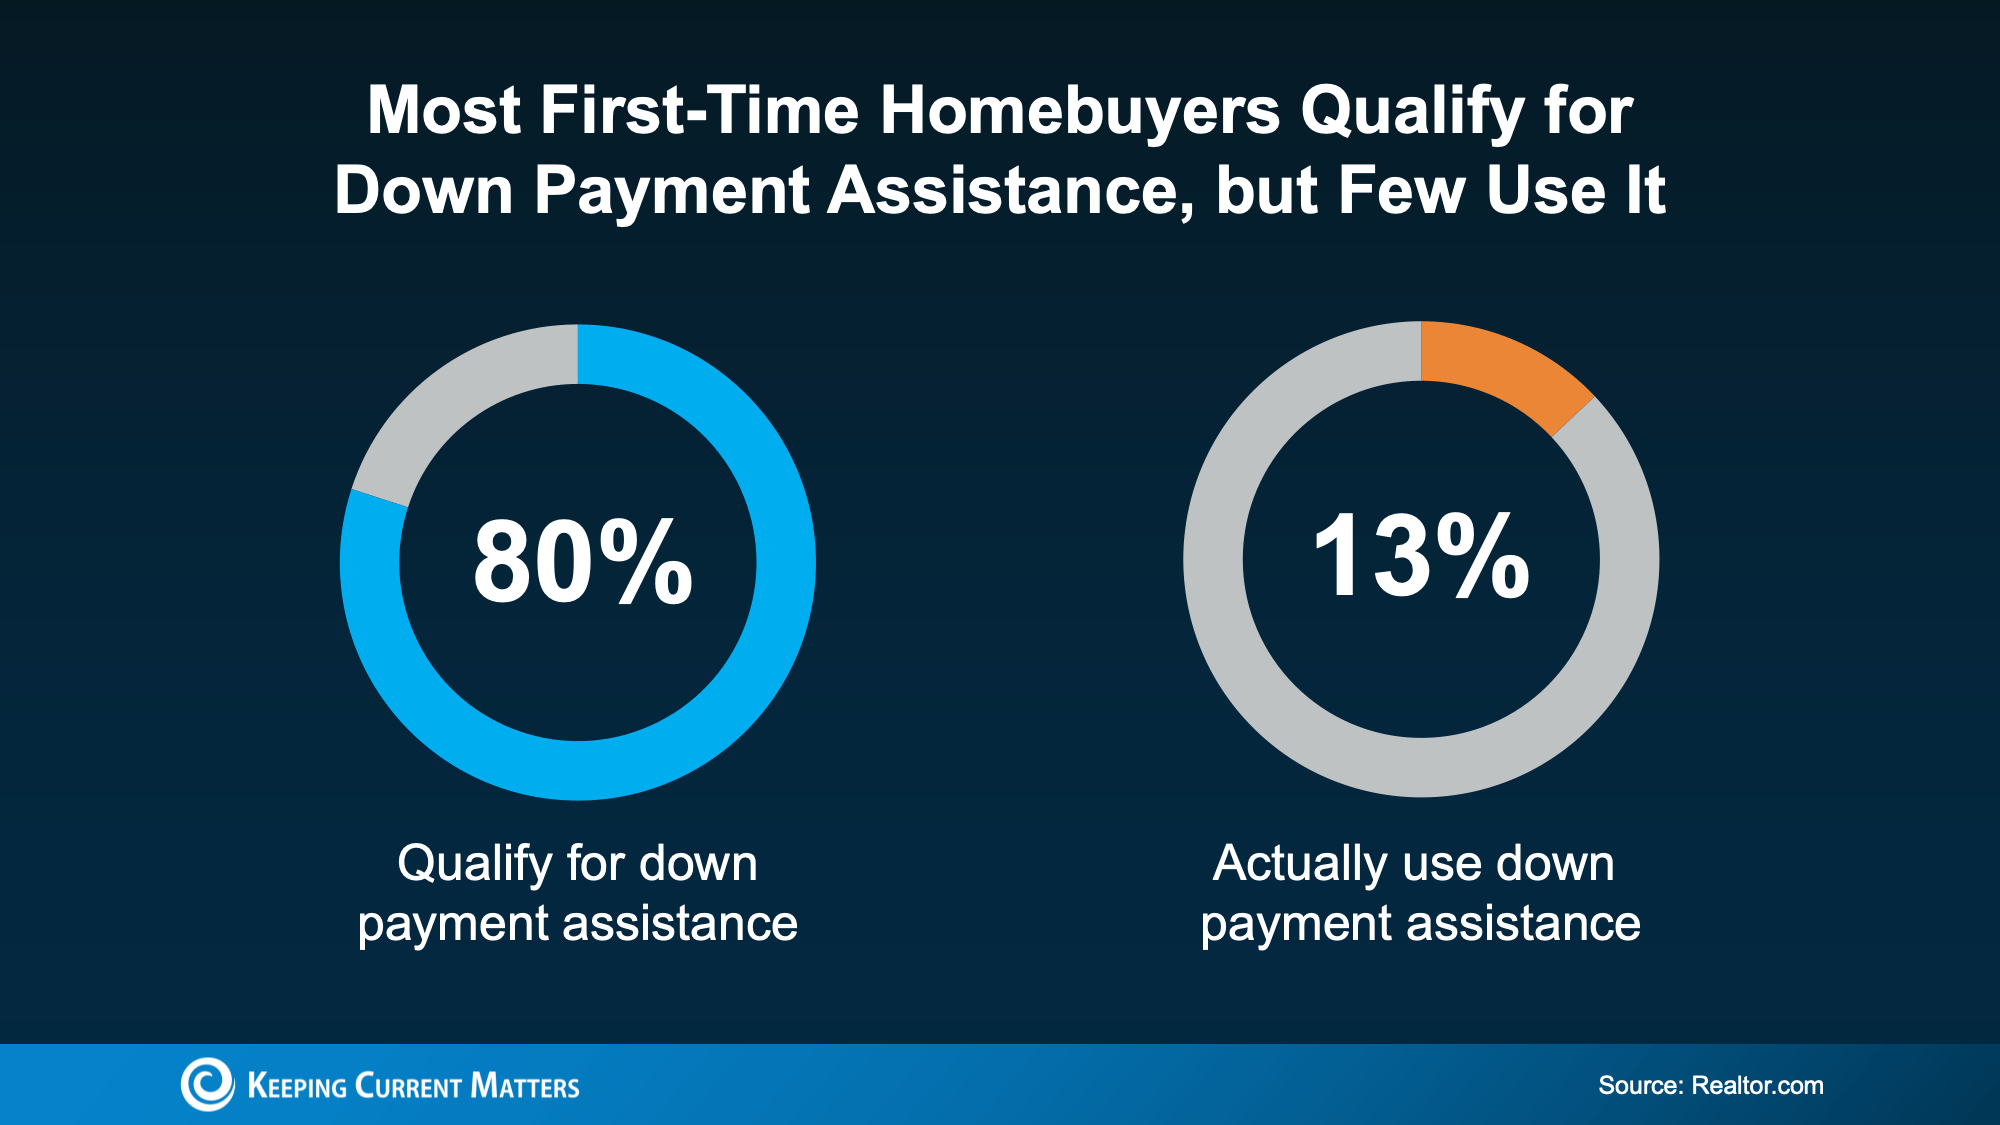
Research from Realtor.com shows almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% actually use it (see chart below)

a blue and orange pie chart

And that’s another big miss holding would-be buyers like you back.

In the U.S., there are over 2,600 homeownership programs available, many offering significant financial support. As Down Payment Resource shares:

With an average benefit of $18,000, down payment assistance (DPA) remains one of the most essential tools for addressing the nation’s affordability challenges. Programs continue to expand in scope, serving a broader range of incomes, property types and borrower needs, including first-generation, military and repeat buyers.

Imagine how much further your savings could go with an extra $18,000 you can use to buy. In some cases, you may even be able to stack multiple programs, giving what you’ve saved an even bigger boost.

Bottom Line

The simple truth is: most first-time buyers don’t put 20% down. And if you’ve been waiting to buy until you have that saved, you may be setting a timeline that’s longer than necessary.

To find out what you really need to save and if you qualify for any help, connect with a trusted lender who can walk you through your options. You may be able to buy sooner than you thought.

Posted in For Buyers
May 1, 2026

Stay or Sell? How To Make the Right Call as You Age

Stay or Sell? How To Make the Right Call as You Age

At some point, as you start thinking about the years ahead, this question tends to come up:

“Could I stay here long-term… or would it make more sense to move?”

It’s not always urgent. It often shows up in small moments, like going up and down the stairs, keeping up with the maintenance, or just thinking about what the next chapter of your life might look like in this home.

And for most people, the answer is simple. They want to stay.

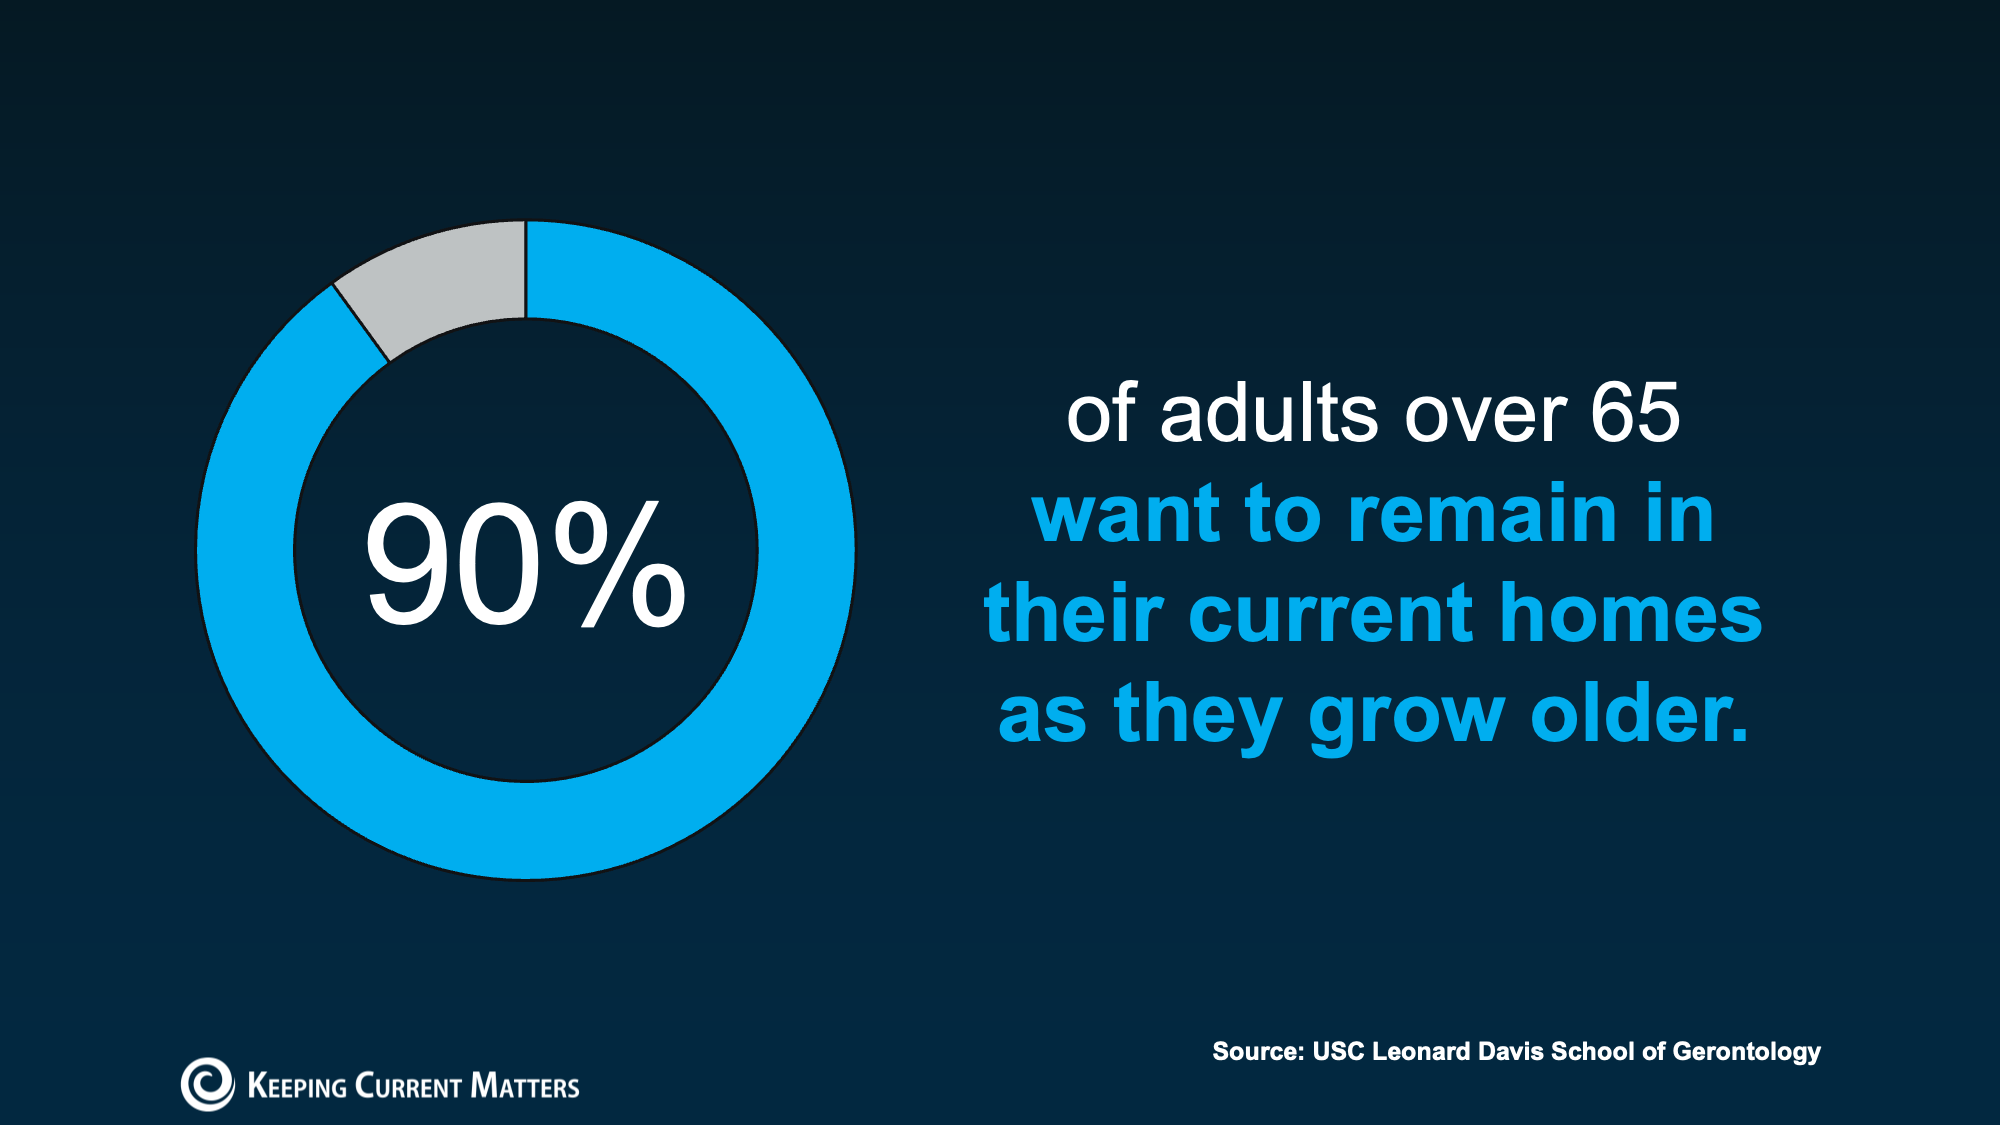
The USC Leonard Davis School of Gerontology found about 90% of adults over 65 prefer to stay in their homes as they get older (see below):

a blue circle with white text

But even if staying feels like the right answer, it’s still worth thinking ahead about what that might actually look like. That’s where the right agent can really help.

What You Need To Plan for If You’re Staying in Your Home

Aging in place is definitely possible. But it’s better if you have a plan. And here’s why. The home that once worked perfectly may need to change with you over the years. And it’s easier if you can anticipate those expenses.

  • Sometimes that means small updates: like adding grab bars in the shower.
  • Other times, you’ll have to make bigger decisions: like reworking layouts or moving key spaces to the first floor.

Some of those changes are going to be simple. Others can be a meaningful investment. And that’s why thinking about it early matters. Not because you need to decide anything right now, but because it gives you time.

  • Time to understand what your home may need.
  • Time to explore your options.
  • Time to find the right contractors.
  • Time to space out the expense of the upgrades.

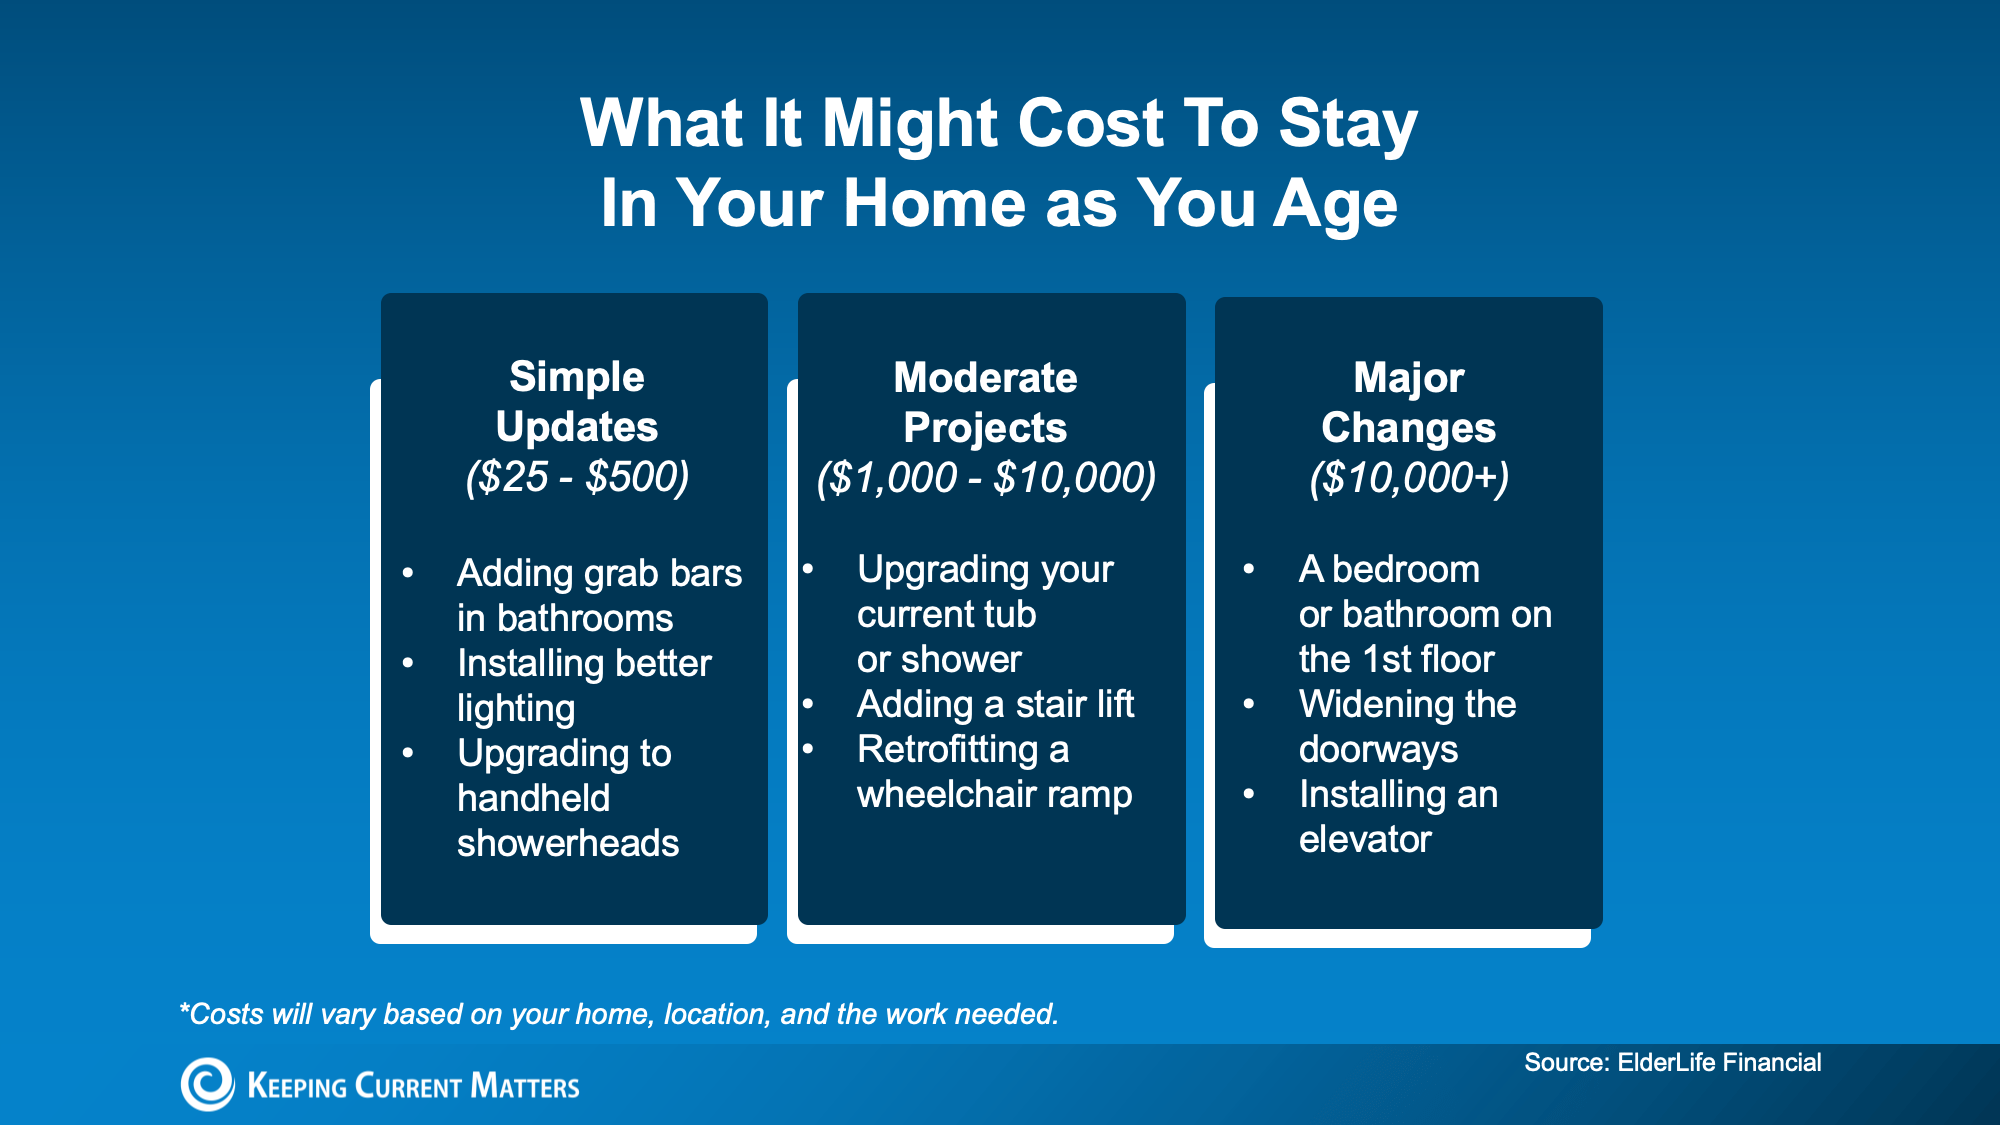
According to ElderLife Financial, here’s a rough baseline of what it could cost depending on what needs to be done (see below):

a blue and white rectangular sign

And don’t worry. If your heart is really set on staying, but the costs feel like a concern, it helps to know you have options. Depending on your situation, there may be financial assistance programs available, along with tools like home warranties to help manage unexpected costs.

Just remember, if you’re thinking about making updates, it’s always worth having a quick conversation before you start. A real estate agent can help you understand which changes tend to make sense for your situation and how they may impact your home’s value based on your local market.

When Moving Might Make More Sense

But staying isn’t always the best fit for every situation. According to Pegasus Senior Living:

“While most seniors hope to age in place, practical considerations sometimes make selling a home the wiser choice.”

Sometimes, it comes down to a simple shift: when the home that once made life easier, starts to make it harder.

That might look like:

  • Maintenance or yardwork that’s starting to feel overwhelming
  • Stairs or layouts that are getting harder to manage day-to-day
  • Or needing more support or care or being too far from loved ones

And sometimes, it’s not about necessity at all. It’s about lifestyle. Some homeowners just don’t want to live through major renovations. Others are ready to simplify, downsize, or move somewhere that better fits this next chapter, whether that’s a smaller home, a 55+ community, or a place closer to family. 

For them, moving simply means making daily life easier.

Bottom Line

There’s no one-size-fits-all answer here.

Some people stay and make updates. Others move to simplify things. Either can be the right choice. The goal isn’t to pick one today. It’s to understand your options early, so when the time comes, you feel confident instead of rushed.

And if you ever want a sounding board to think through what the future could look like for you, a local real estate agent is there to help.

Posted in For Sellers
April 30, 2026

Is Late May the Best Time To List Your House?

Is Late May the Best Time To List Your House?

You may have heard April 12-18 was the “best week” to list your house. That’s based on a report from Realtor.com. But now that it’s passed, you may be wondering if you missed your moment.

Here’s the good news – you didn’t. 

Because the reality is, there isn’t just one perfect week to sell your house this Spring. There’s a window. And right now, you’re still in it.

Your Window To Sell Is Still Wide Open

Here’s why. Different organizations run studies like this every year. And they don’t always land on the exact same week. That’s okay. It’s because they’re using different research methods and even different definitions of what “best” means.

But the fact that the results vary points to a larger trend. While there may be sweet spots, the entire Spring season gives sellers an opportunity to get some of the best conditions (and best sales prices) of the year.

And it’s definitely not too late to jump in.

Why Listing in Late May Is the Perfect Play

According to Zillow, the best time to list your house this year is the last 2 weeks of May. And that’s approaching fast.

Based on their analysis, this is the ideal time to do it if you want to make top dollar. Because, in this 2-week window, homes sell for more. Sometimes, quite a bit more.

Depending on where you are and the price point in your area, some homeowners may even net tens of thousands of dollars extra in this sweet spot. As Zillow explains:

“Why late spring? Buyer demand typically peaks before Memorial Day. Families want to move during the summer and settle in before the new school year. More buyers shopping at once can spark competition and lift prices.”

And they’re not the only ones saying listing in May could be the key to selling for more. ATTOM Data analyzed almost 52 million home sales over the past 10 years and found sellers in May are achieving some of the highest returns.

That means the ideal window this year is very much still open.

What This Means for You 

If your goal is to sell for the strongest possible price, this is where timing and strategy come together. And you want to be sure you’re ready to make the most of it.

So, what should you be doing right now?

When prepping for a fast-moving window like this, you don’t want to waste time or money on the wrong prep work. And your agent is your go-to to make sure you’re focusing on the right things.

They’ll be able to tell you if the “best week” is slightly different in your market. And what quick repairs or updates can help you get a higher price, without taking a ton of time or effort.

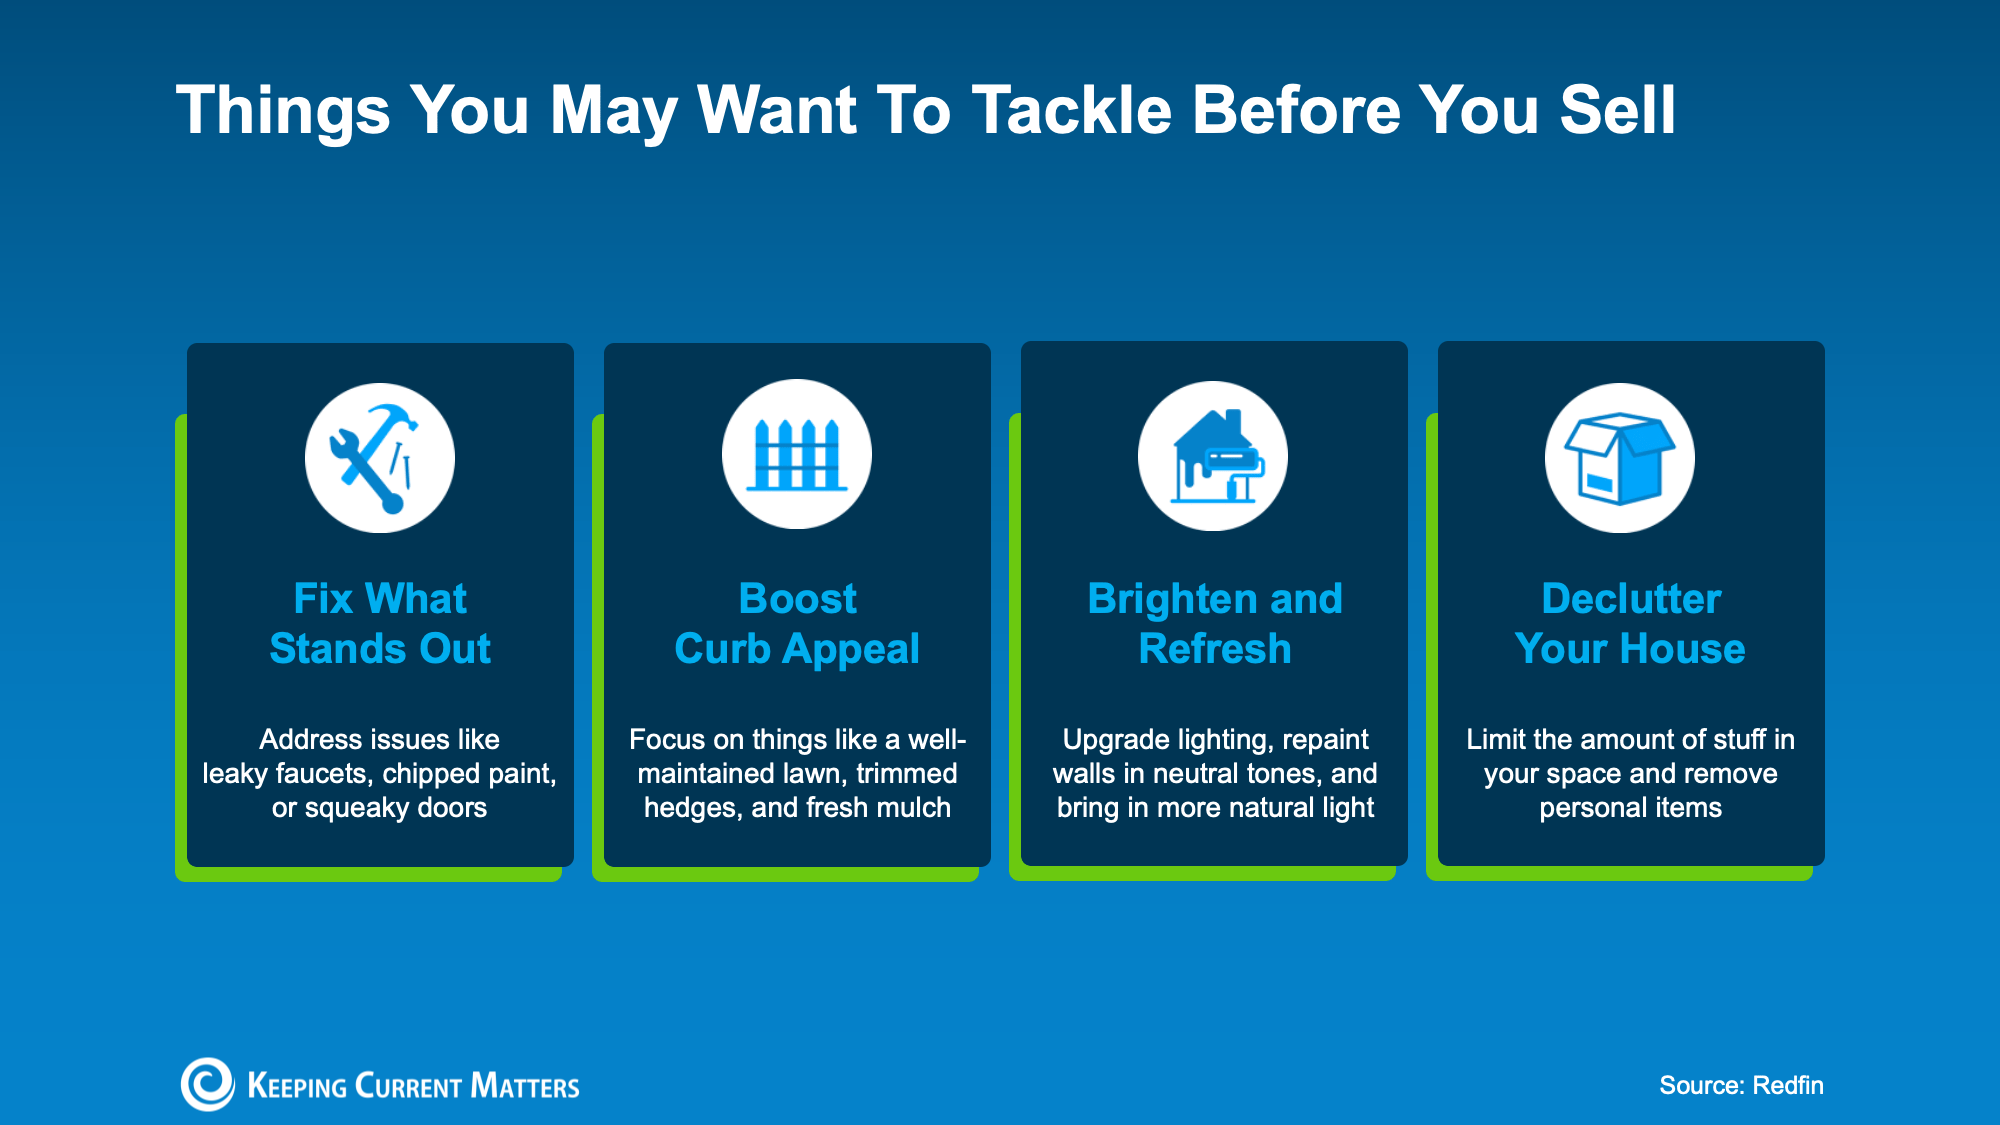
Here’s a quick example of things an agent may recommend based on information from Redfin:

At the end of the day, when your prep time’s short, doing the right things matters more than doing more things.

Bottom Line

Zillow says the best time to list your house is just around the corner. Are you ready to make the most of it?


If you want to take advantage of this Spring sweet spot and get top dollar for your house, talk to a local agent about what you need to do now to get ready to hit the market.

Posted in For Sellers
April 16, 2026

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking.

With today’s home prices and mortgage rates, renting can feel like the easier path. In some cases, it might even seem like the only realistic option right now. And if that’s where you are, there’s nothing wrong with that.

But if you’re weighing the decision, there’s one part of the conversation that doesn’t get talked about enough.

It’s what each choice does for your future.

What Renting Really Gets You (And What It Doesn’t)

Depending on your situation, renting does have some advantages:

  • Lower upfront costs.
  • Less responsibility.
  • More flexibility to move when you want.

But even with those benefits, a Bank of America survey found 70% of aspiring homeowners worry about what long-term renting means for their future. And that concern comes down to one thing: you’re not building anything for your future. As Yahoo Finance explains:

“Paying rent doesn’t build equity. You get a place to live, but no ownership stake, no price appreciation, and no asset to leverage for future borrowing or investment.”

So, while renting may feel easier, the flexibility you get comes at a cost.

How Homeownership Builds Your Wealth Over Time

On the other hand, owning a home is one of the most consistent ways people build wealth over time. Why? When you’re a homeowner, you gain something called equity. That’s the difference between what your home is worth and what you owe.

That equity grows with every monthly payment you make. It also gets a boost as home values go up through the years – and it adds up quicker than you may think.

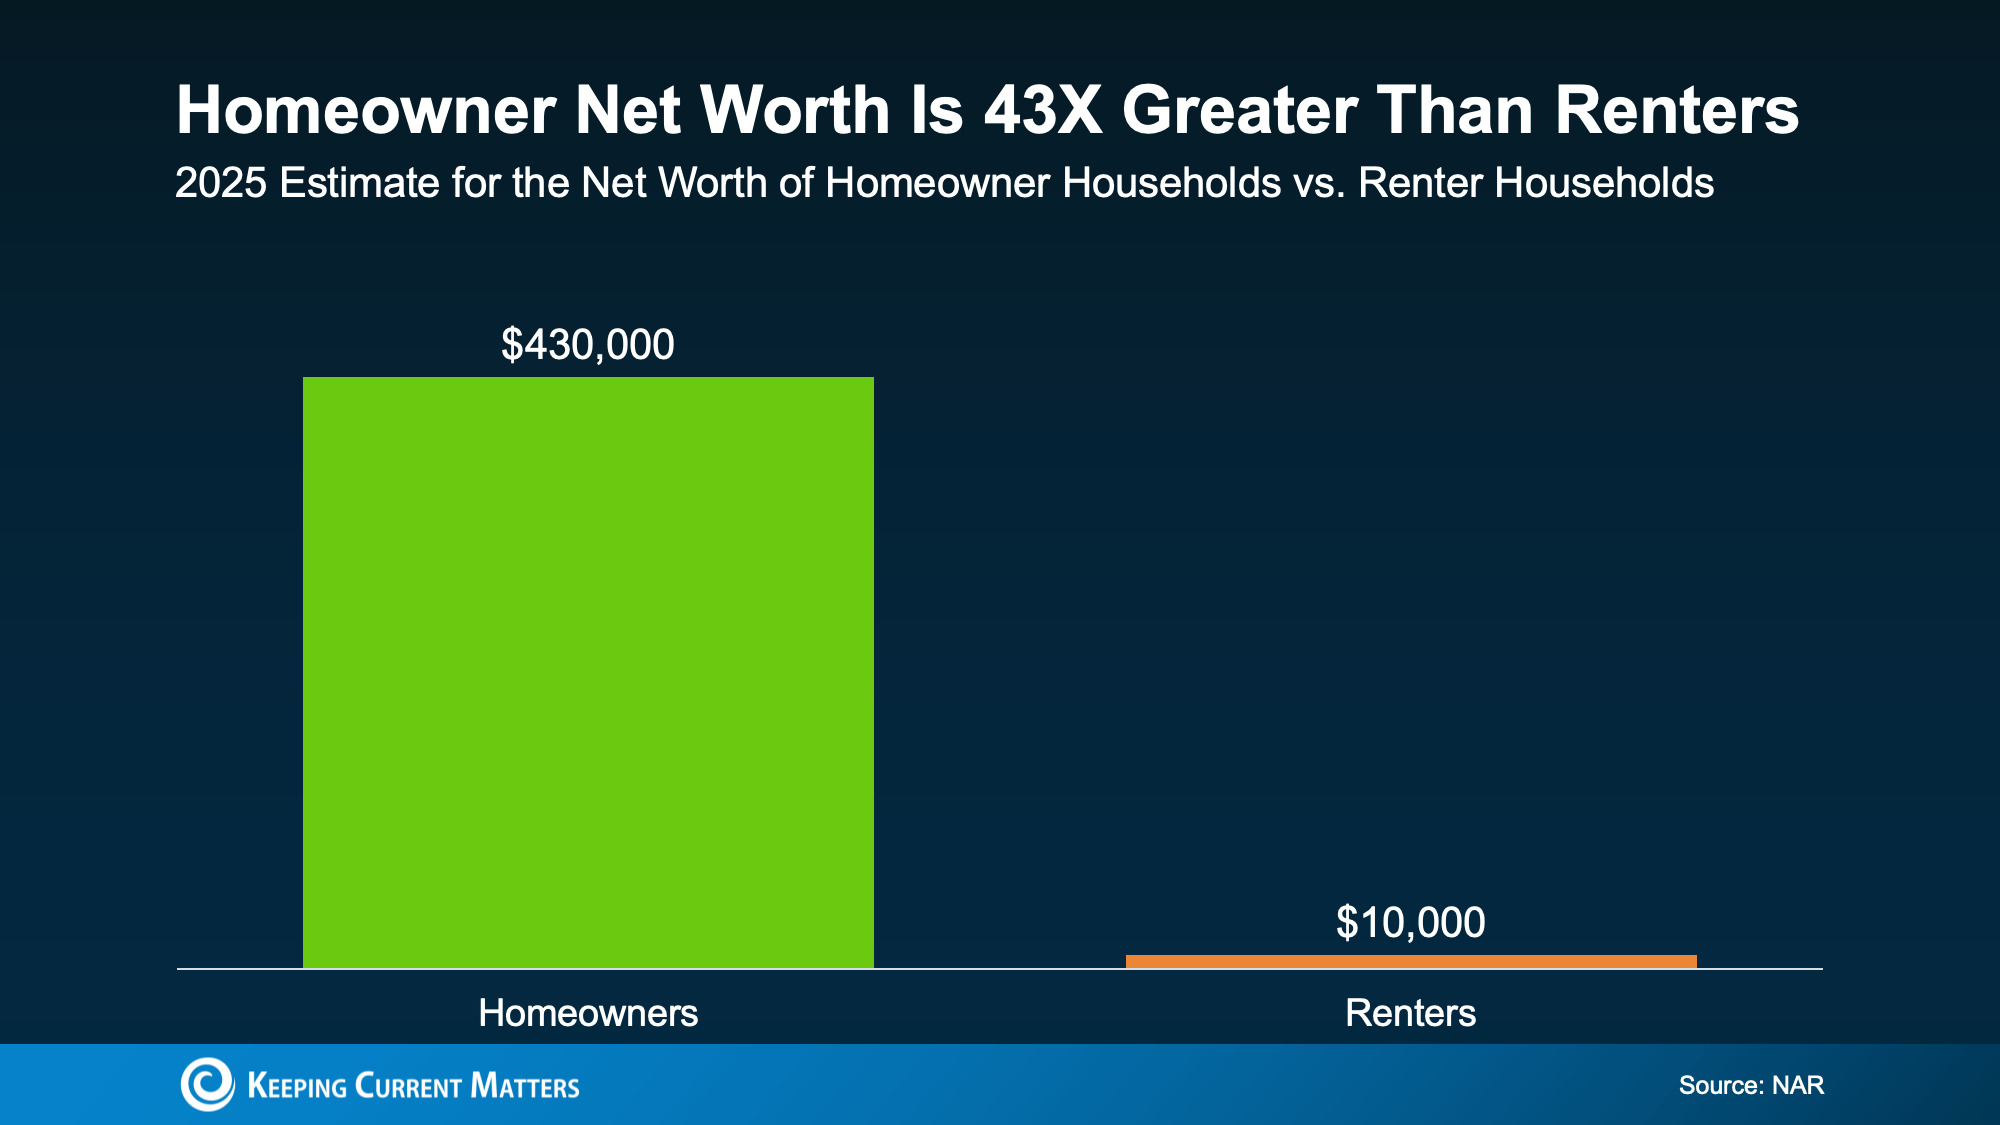
Today, the National Association of Realtors (NAR) says the average homeowner’s net worth is 43X greater than that of a renter:

a graph of a number of people

The dollars in the visual don’t lie. On average, here’s how net worth compares:

  • Homeowners: $430k
  • Renters: $10k

And it’s not because homeowners make wildly different decisions day to day. It’s because over time, one path builds something, and the other doesn’t.

So sure, buying comes with some upfront costs and more responsibility. But it’s basically a savings account you can live in.

The Gap Is Growing Over Time

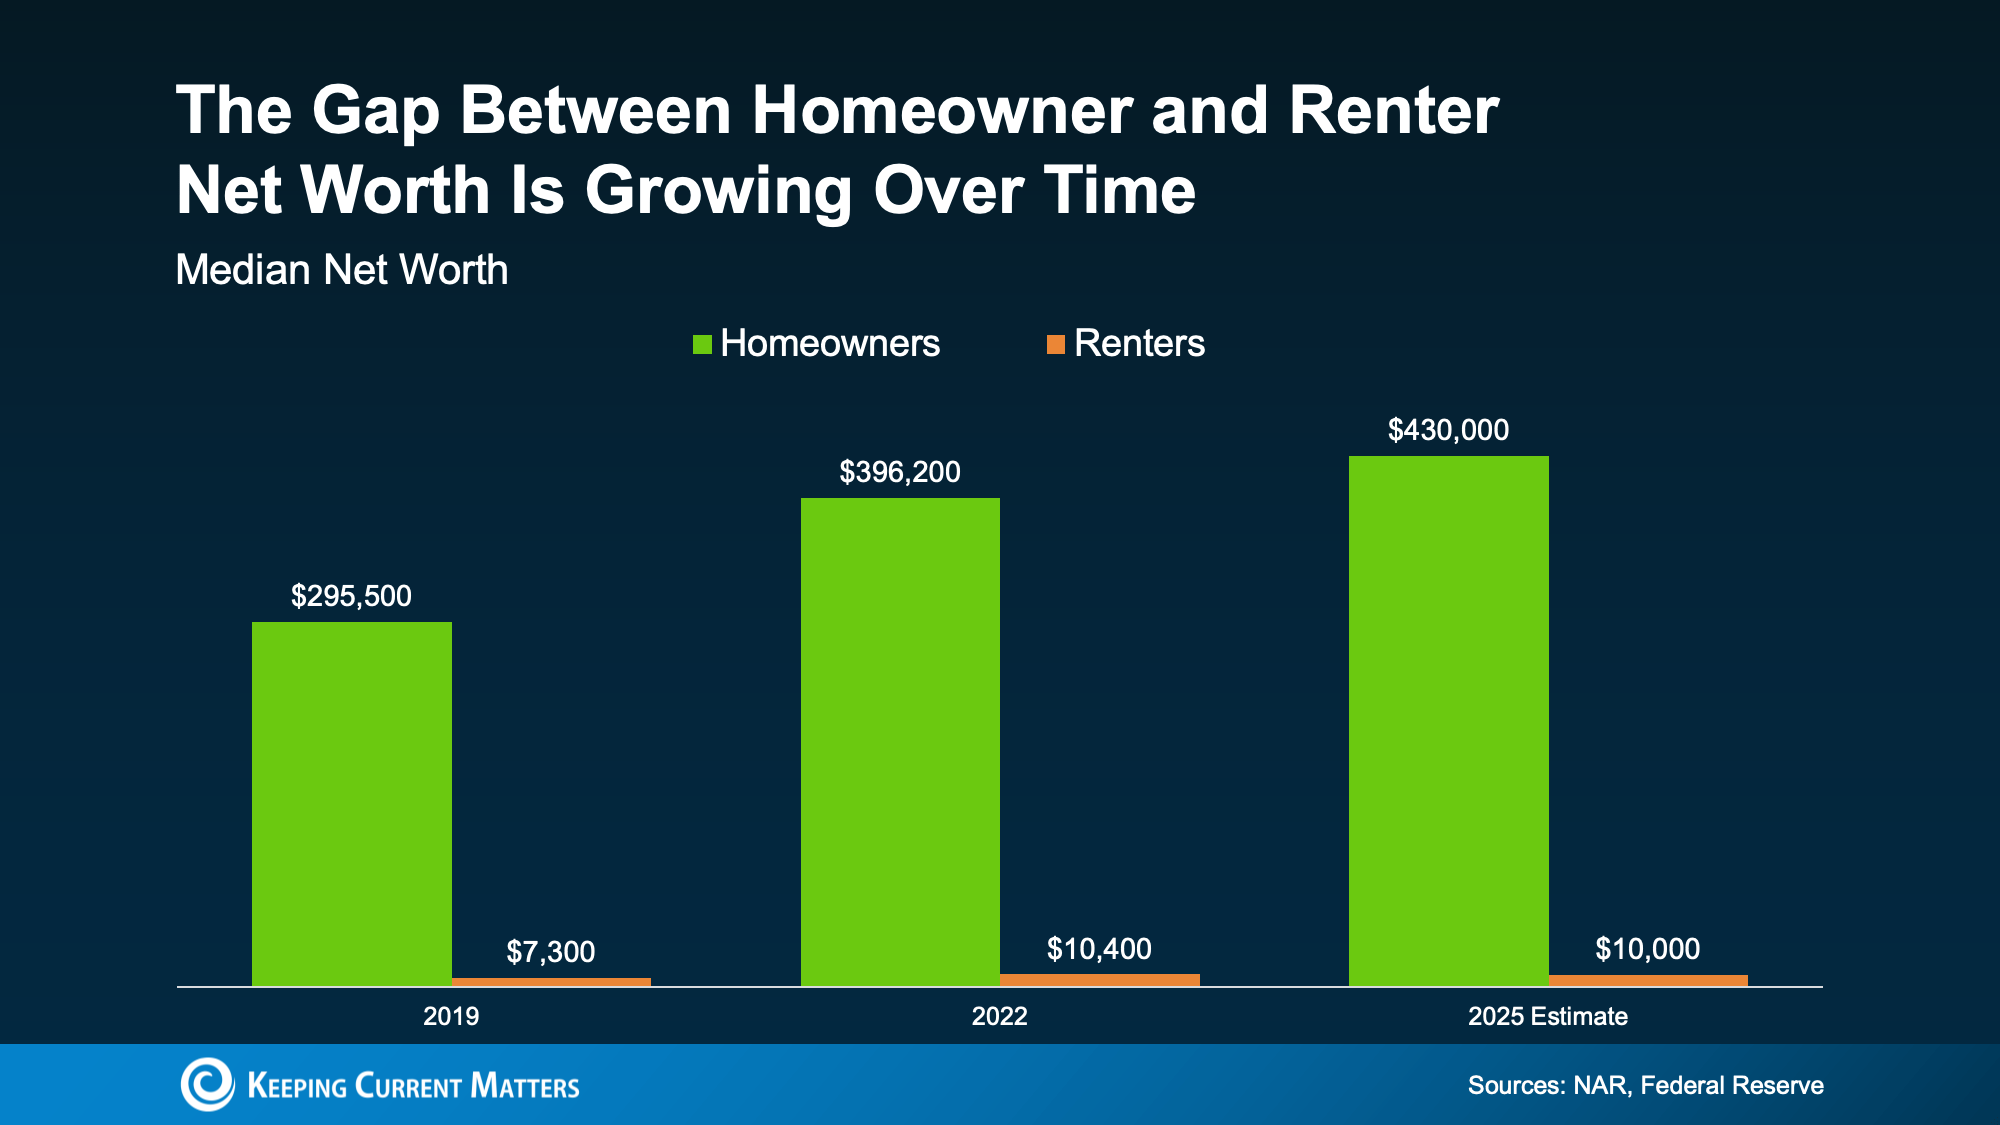
And here’s something else interesting. That net worth gap between renters and homeowners has been widening over time, not shrinking.


If you look back at the reports on net worth through the years, you can see the gap is growing as homeowners gain wealth and renters stay stuck in the rental trap (see graph below):

a graph of green and blue bars

Even in 2025, when home prices were moderating, homeowners still gained even more ground. And that tells you something important:

When you can afford it and you’re ready for the responsibility, history shows buying is usually worth it in the long run. Because either way, you’re paying for someone’s mortgage and building someone’s net worth.

When you rent, it’s your landlord’s mortgage – not yours. But when you buy? Your monthly payments help build equity.

The question is: whose do you want to pay? Yours or theirs?

So, Should You Buy a Home Now?

The short answer is, it depends on your situation.

While the long-term benefits of buying are clear, that doesn’t mean the timing is right for everyone right now. And that’s okay. You should only buy a home once you’re ready and the numbers work for you.

But whether you’re looking to buy now or planning for the future, the first step is the same. You should have a quick conversation with a local real estate agent about your goals, timeline, and budget.

They can help you run the numbers and see what’s realistic. You may find buying is closer than you thought. And if not, you’ll at least know exactly what it will take to get there.

Because the sooner you have a plan, the sooner you can decide when it makes sense, instead of wondering if it ever will.

Bottom Line

Renting may feel more do-able today. But over time, it could cost you.

If you want to ditch renting and start building something for your future, it starts with a simple conversation. Connect with a real estate agent to talk about your specific goals, and explore your options – so you’re ready when the time is right for you.

Posted in For Buyers
April 15, 2026

When Buying a Home Feels Out of Reach, Some Families Do This Instead.

When Buying a Home Feels Out of Reach, Some Families Do This Instead

When Buying a Home Feels Out of Reach, Some Families Do This Instead

For a lot of people, the math on buying a home just doesn’t really work right now. Maybe that’s how it feels for you too. You look at the cost of buying. Then you look at the cost of childcare. And it starts to feel like you have to choose one or the other.

But some families are finding a way to make both work by doing something a little different: teaming up to purchase a multi-generational home.

One Reason This Is Becoming More Common

It’s no secret that affordability has been a challenge in recent years. But for families with young kids, there’s an added layer that can make it feel even harder: childcare.

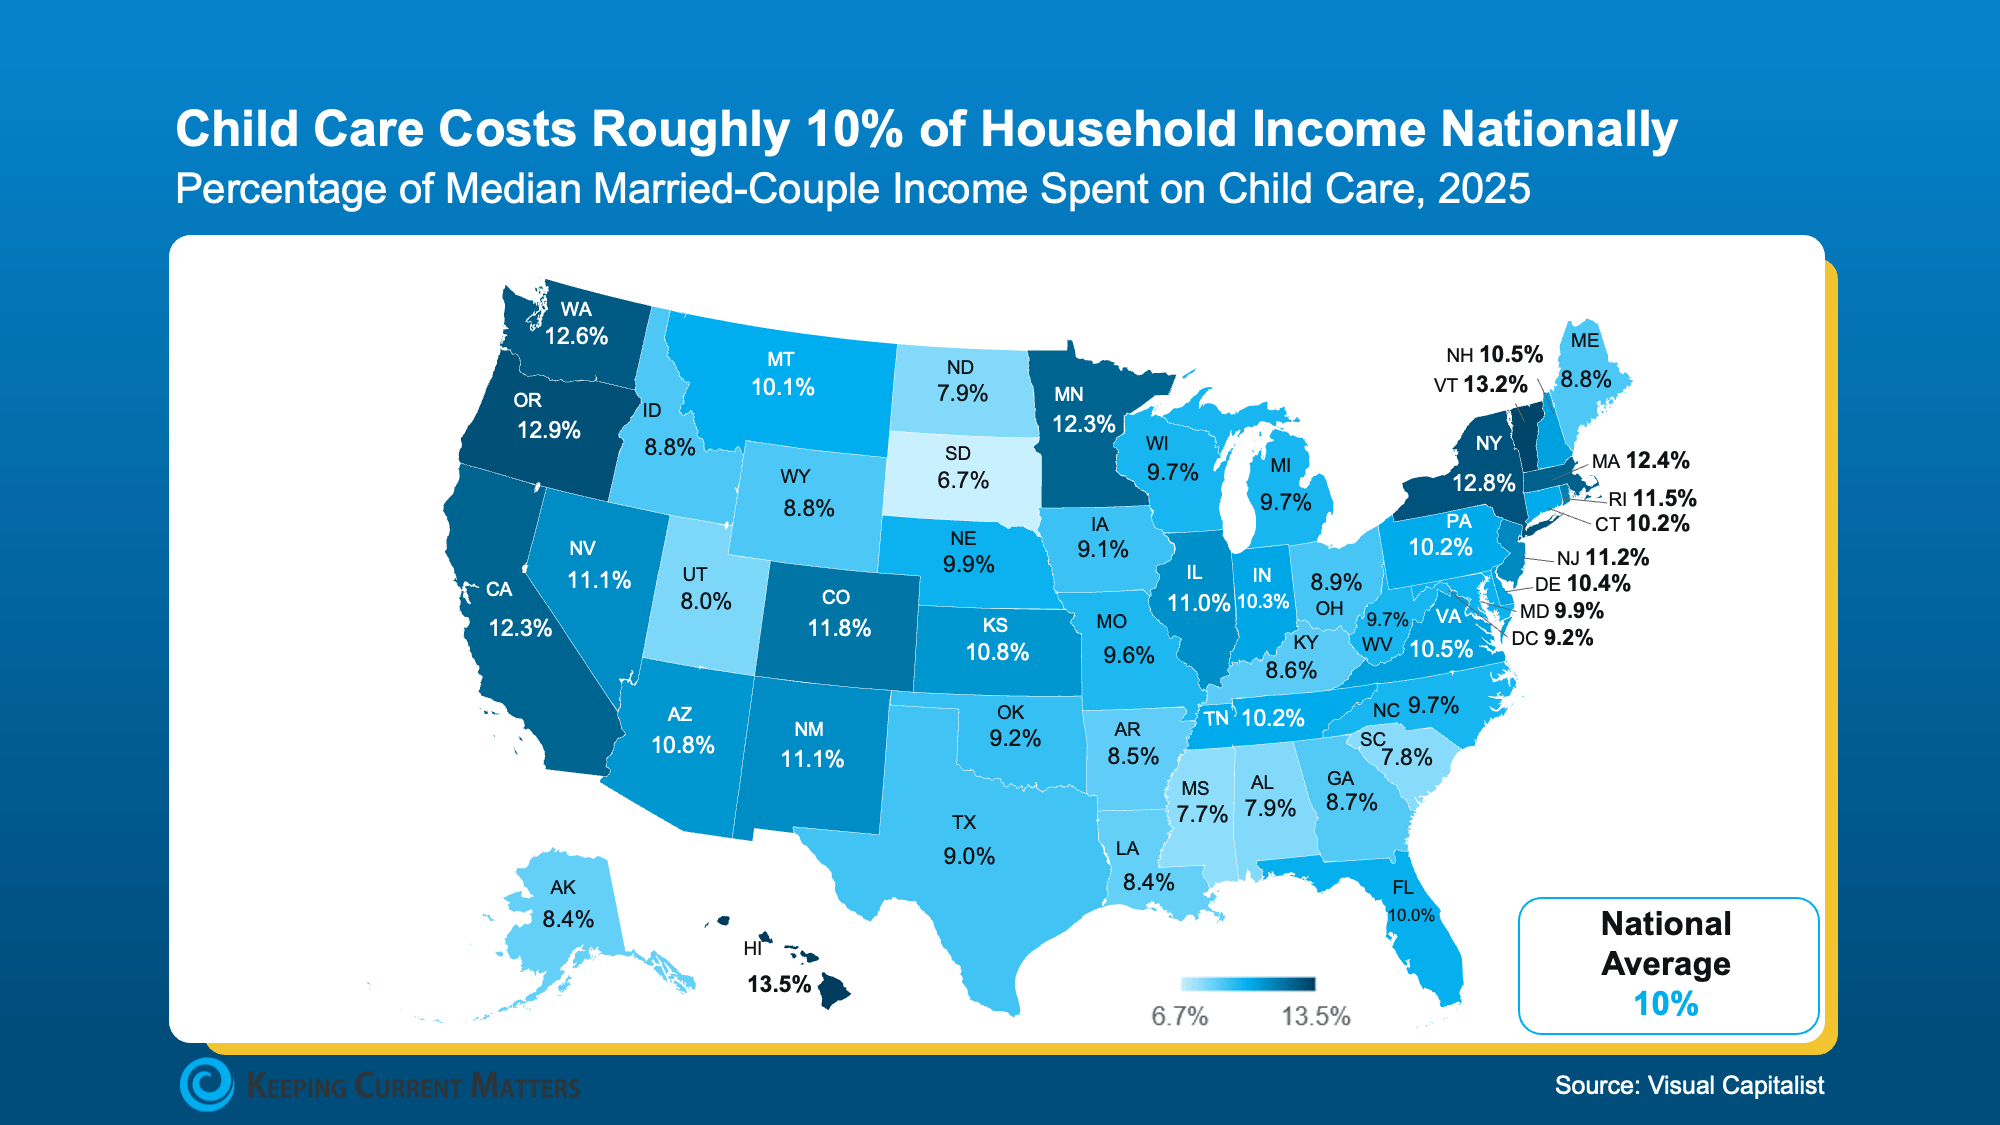
According to the Department of Health and Human Services, childcare should take up no more than 7% of your monthly income. But in reality, the average married couple spends closer to 10% (see map below):

a map of the united statesWhen you combine that with the cost of buying a home, it’s easy to see why things can feel stretched. That’s exactly why more families are starting to rethink how they approach both.

The Solution More People Are Turning To: Multi-Generational Living

One option gaining traction? Multi-generational living. That’s when parents, grandparents, or other relatives buy a house together and live under the same roof. And it’s not just about convenience anymore. It’s becoming a go-to strategy.

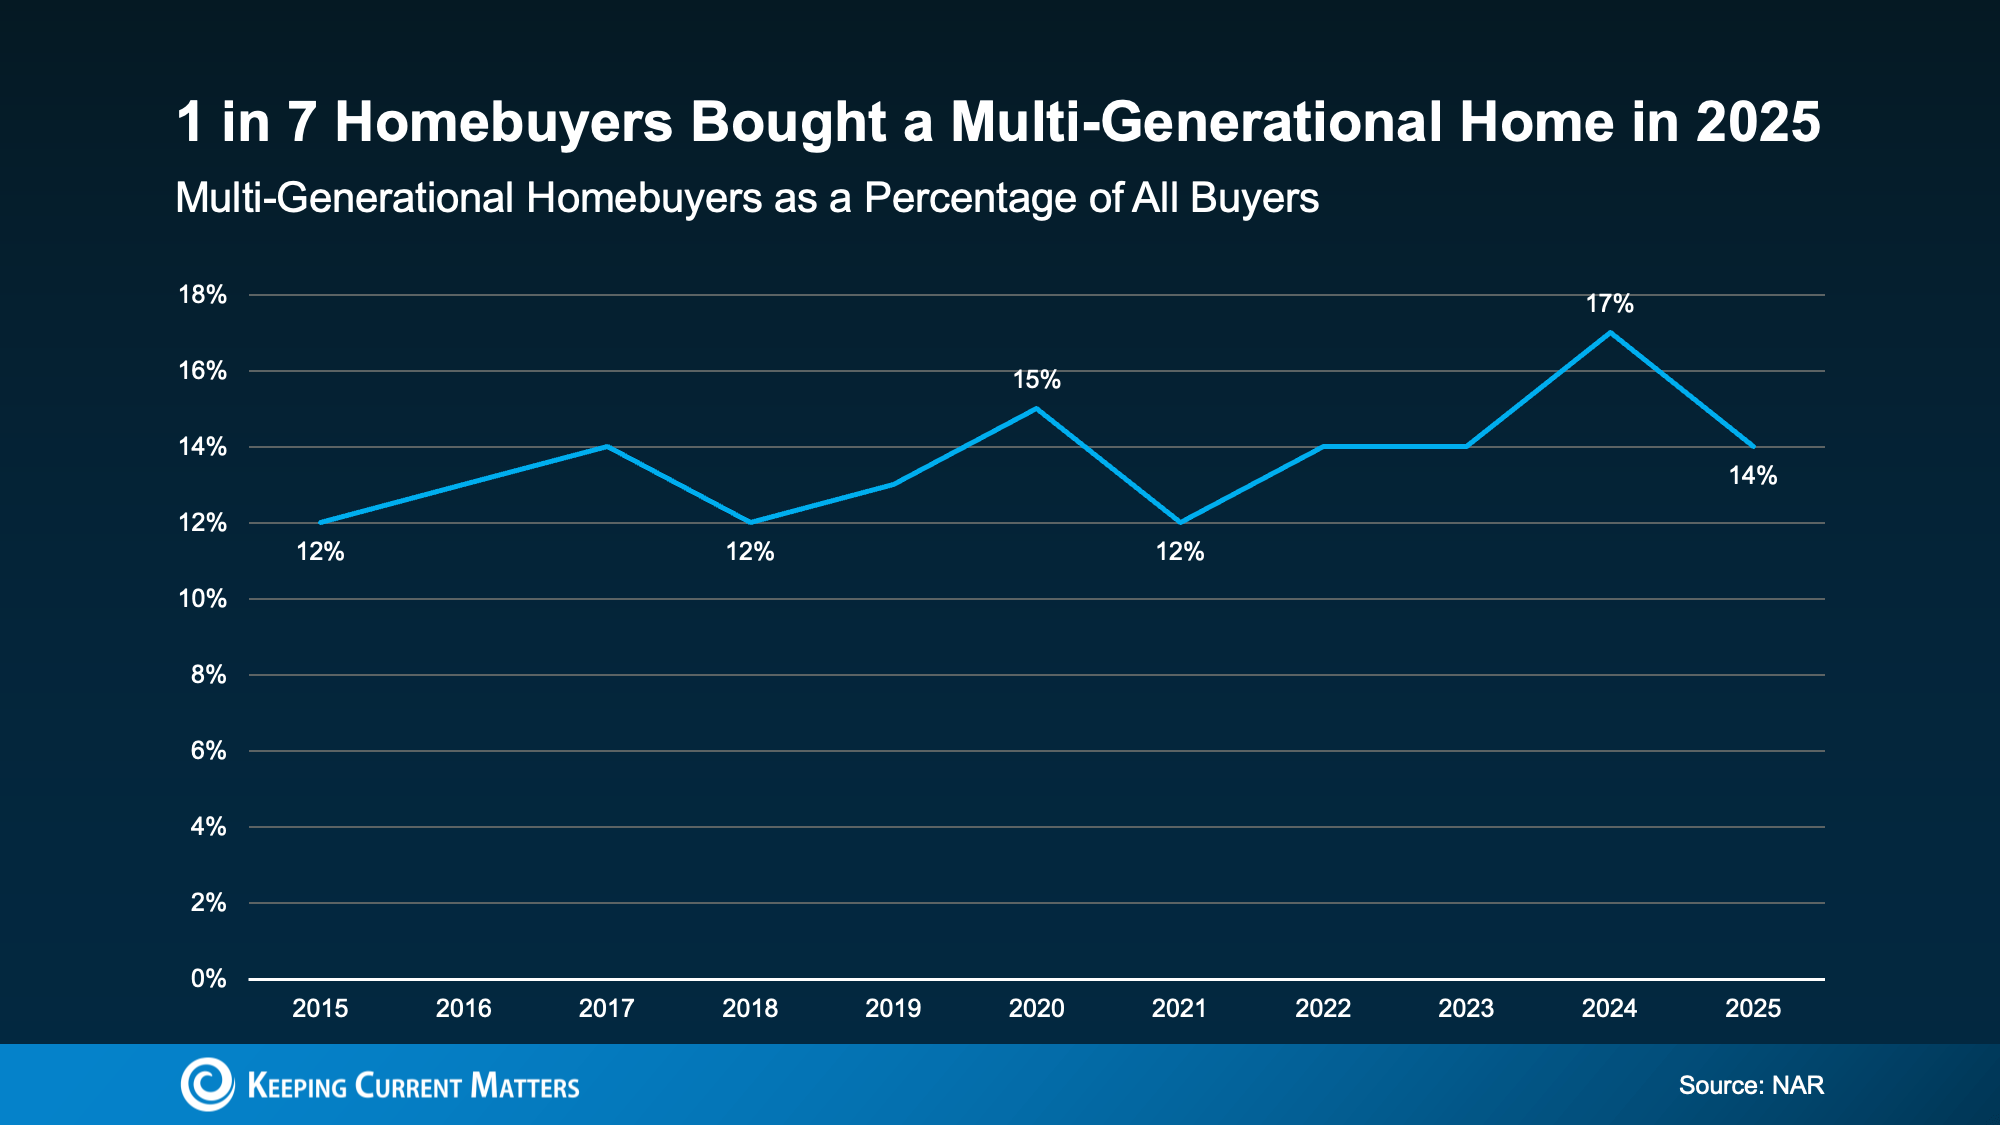
You can see it in the data. According to the National Association of Realtors (NAR), almost 1 in 7 homebuyers (14%) bought a multi-generational home in 2025 (see graph below):

a graph of a homebuyers bought a multi-generation homeAnd for the first time, childcare is showing up as a key reason why they chose this option. As NAR explains:

“This year’s report features two new primary reasons for purchasing a multi-generational home: grandchildren living in the home (12%) and to help reduce the cost of childcare (6%).”

Why It Works

Buying a multi-generational home solves two big challenges at the same time.

  • First, it shares the financial responsibility. If you pool multiple incomes together, you may be able to afford a home you couldn’t have on your own.
  • Second, it can also solve the childcare puzzle. When grandparents or other relatives live in the home, they may be able to help with daily care – which can significantly reduce or even eliminate daycare costs.

And for many people, that combination is what finally makes their move possible.

If the costs of childcare and housing together have made buying feel out of reach right now, it may be worth exploring creative options like buying a home with your loved ones.

Bottom Line

If you want more information on multi-generational homes, talk to a local agent about what’s available in your area.

Sometimes the path to homeownership isn’t doing it alone. It’s doing it together.

Posted in For Buyers
April 13, 2026

Thinking About an Adjustable-Rate Mortgage? Here’s What You Need To Know.

Thinking About an Adjustable-Rate Mortgage? Here’s What You Need To Know.

Thinking About an Adjustable-Rate Mortgage? Here’s What You Need To Know.

If you’ve been looking for a home lately, you’ve probably felt how tough affordability still is. And that’s exactly why more buyers are opting for adjustable-rate mortgages, or ARMs.

Here’s what you need to understand about how they work, and whether they make sense for you.

What Is an Adjustable-Rate Mortgage?

Since a lot of people aren’t familiar with this type of loan, let’s start with a definition. This is how Business Insider explains the main difference between a fixed-rate mortgage and an adjustable-rate mortgage:

“With a fixed-rate mortgage, your interest rate remains the same for the entire time you have the loan. This keeps your monthly payment the same for years . . . adjustable-rate mortgages work differently. You’ll start off with the same rate for a few years, but after that, your rate can change periodically. This means that if average rates have gone up, your mortgage payment will increase. If they’ve gone down, your payment will decrease.”

Basically, one doesn’t change much over the life of your loan.

And one could change… either by a little, or a lot.

Of course, things like taxes or homeowner’s insurance can still have an impact on a fixed-rate loan, but the baseline of your mortgage payment is fairly steady. But the big difference is that with an ARM, your monthly payment could change over time.

Why Adjustable-Rate Mortgages Are Getting More Attention

So, why do some buyers choose this option? It’s simple. It’s because of the upfront savings. Business Insider explains it like this:

“Because ARM rates are typically lower than fixed mortgage rates, they can help buyers find affordability when rates are high. With a lower ARM rate, you can get a smaller monthly payment or afford more house than you could with a fixed-rate loan.

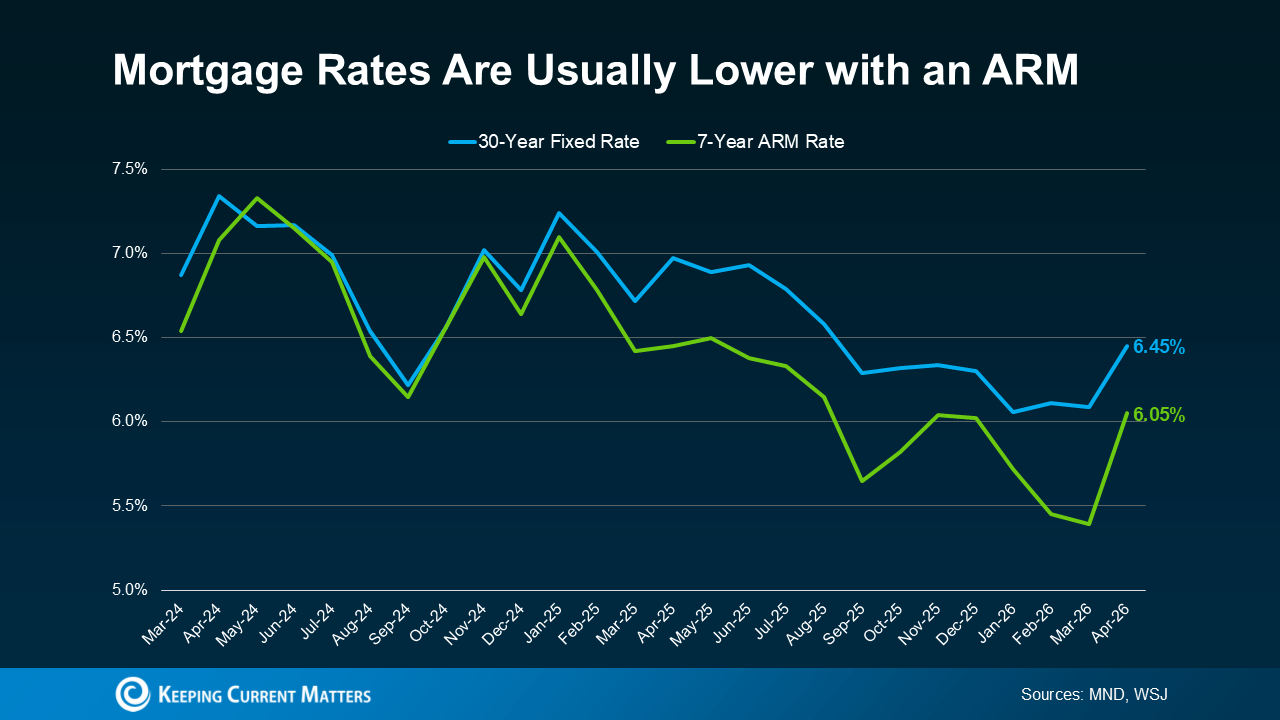
And right now, according to Mortgage News Daily and the Wall Street Journal, the upfront rate on an ARM is lower than a 30-year fixed mortgage (see graph below):

a graph with green and blue linesIf you’re wondering how that shakes out in real dollars and cents, here’s what Redfin says. According to their research, the typical buyer could save about $150 per month by taking out an ARM instead of a 30-year fixed mortgage.
For some people, that’s enough to make a difference.

More Buyers Are Choosing Adjustable-Rate Mortgages Today

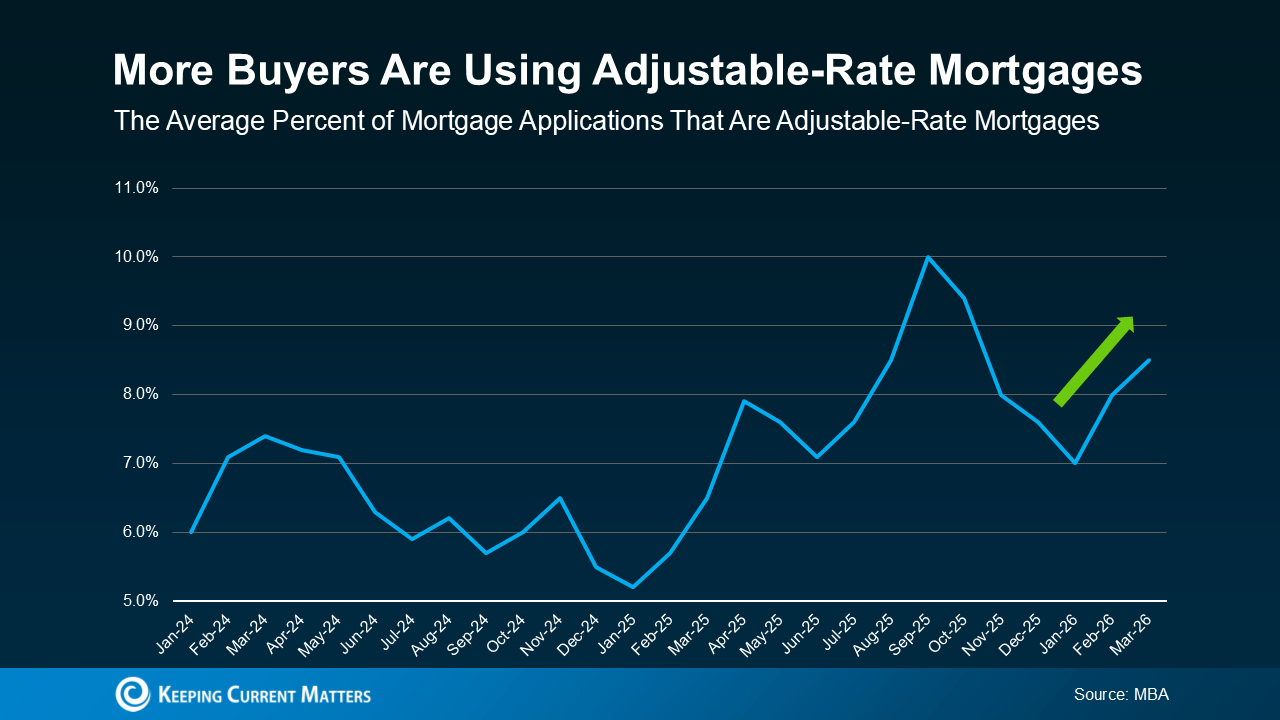
A growing number of buyers are willing to trade the uncertainty later for a lower payment now. Data from the Mortgage Bankers Association (MBA) shows the share of buyers choosing ARMs has increased, especially over the last few years (see graph below).

This doesn’t mean ARMs are becoming the go-to option for everyone. It only means some buyers are opting for this type of mortgage, so they can still buy today.

a graph with a line going upAnd if you remember the housing crash, seeing ARMs gain popularity again may raise concerns. But rest easy. Today’s ARMs aren’t the same.

Back then, some buyers were given loans they couldn’t afford once rates adjusted.

Today, lending standards are stricter, and lenders evaluate whether borrowers could still handle the payment if rates rise. So, the return of ARMs doesn’t signal another widespread crash. It just reflects how some buyers are adapting to today’s affordability challenges.

The Trade-Off – What You Need To Consider

If you’re considering an adjustable-rate mortgage yourself, just remember it really all depends on your situation and your risk tolerance.

An ARM may make sense if you plan to move before your rate would adjust or if you expect you’ll make a higher income in the future. But there are trade-offs you need to think through.

For example, once the fixed period ends, your rate can adjust, and your payment could increase, potentially by a meaningful amount depending on where rates are at that time.

And keep in mind, there’s also no guarantee mortgage rates will come down in the future, which means refinancing later isn’t always an option. That’s why it’s important to think through your plan, understand your long-term earning potential, and work closely with a trusted lender before you choose an ARM.

Bottom Line

ARMs are getting more attention again because they can make buying a home more affordable in the short term. But they’re not right for everyone.

The key is understanding how they work, what the risks are, and whether they fit your plan. And that’s why you need to talk to a trusted lender and financial advisor before you make any decisions.

Posted in For Buyers